Ceasefire Optionality
“A person who stands on his tiptoes cannot stand long and a person who is too proud of himself cannot set a good example.” — Lao Tzu.
“When a majority of the people are hungry and cold they will take by force what they need.” — Steinbeck, The Grapes of Wrath.
“The world might be closer to a full-on inflationary bust, the very worst environment for investors, than at any point in my career.” — Louis-Vincent Gave. He argues that the three assumptions that underpinned global portfolios — US Treasuries convert to energy, the US Navy controls sea lanes, and the US is a benevolent hegemon — are now dead, and that 3% energy in a portfolio no longer cuts it.
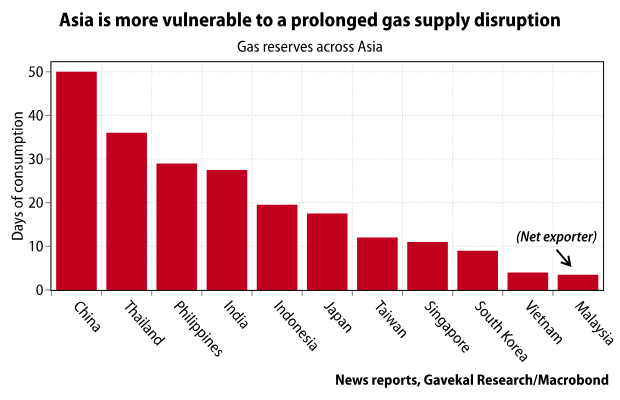
South Korea entered this crisis with 10 days’ worth of gas. China came in with 50. The difference is not luck — it is which assumptions you stopped believing.
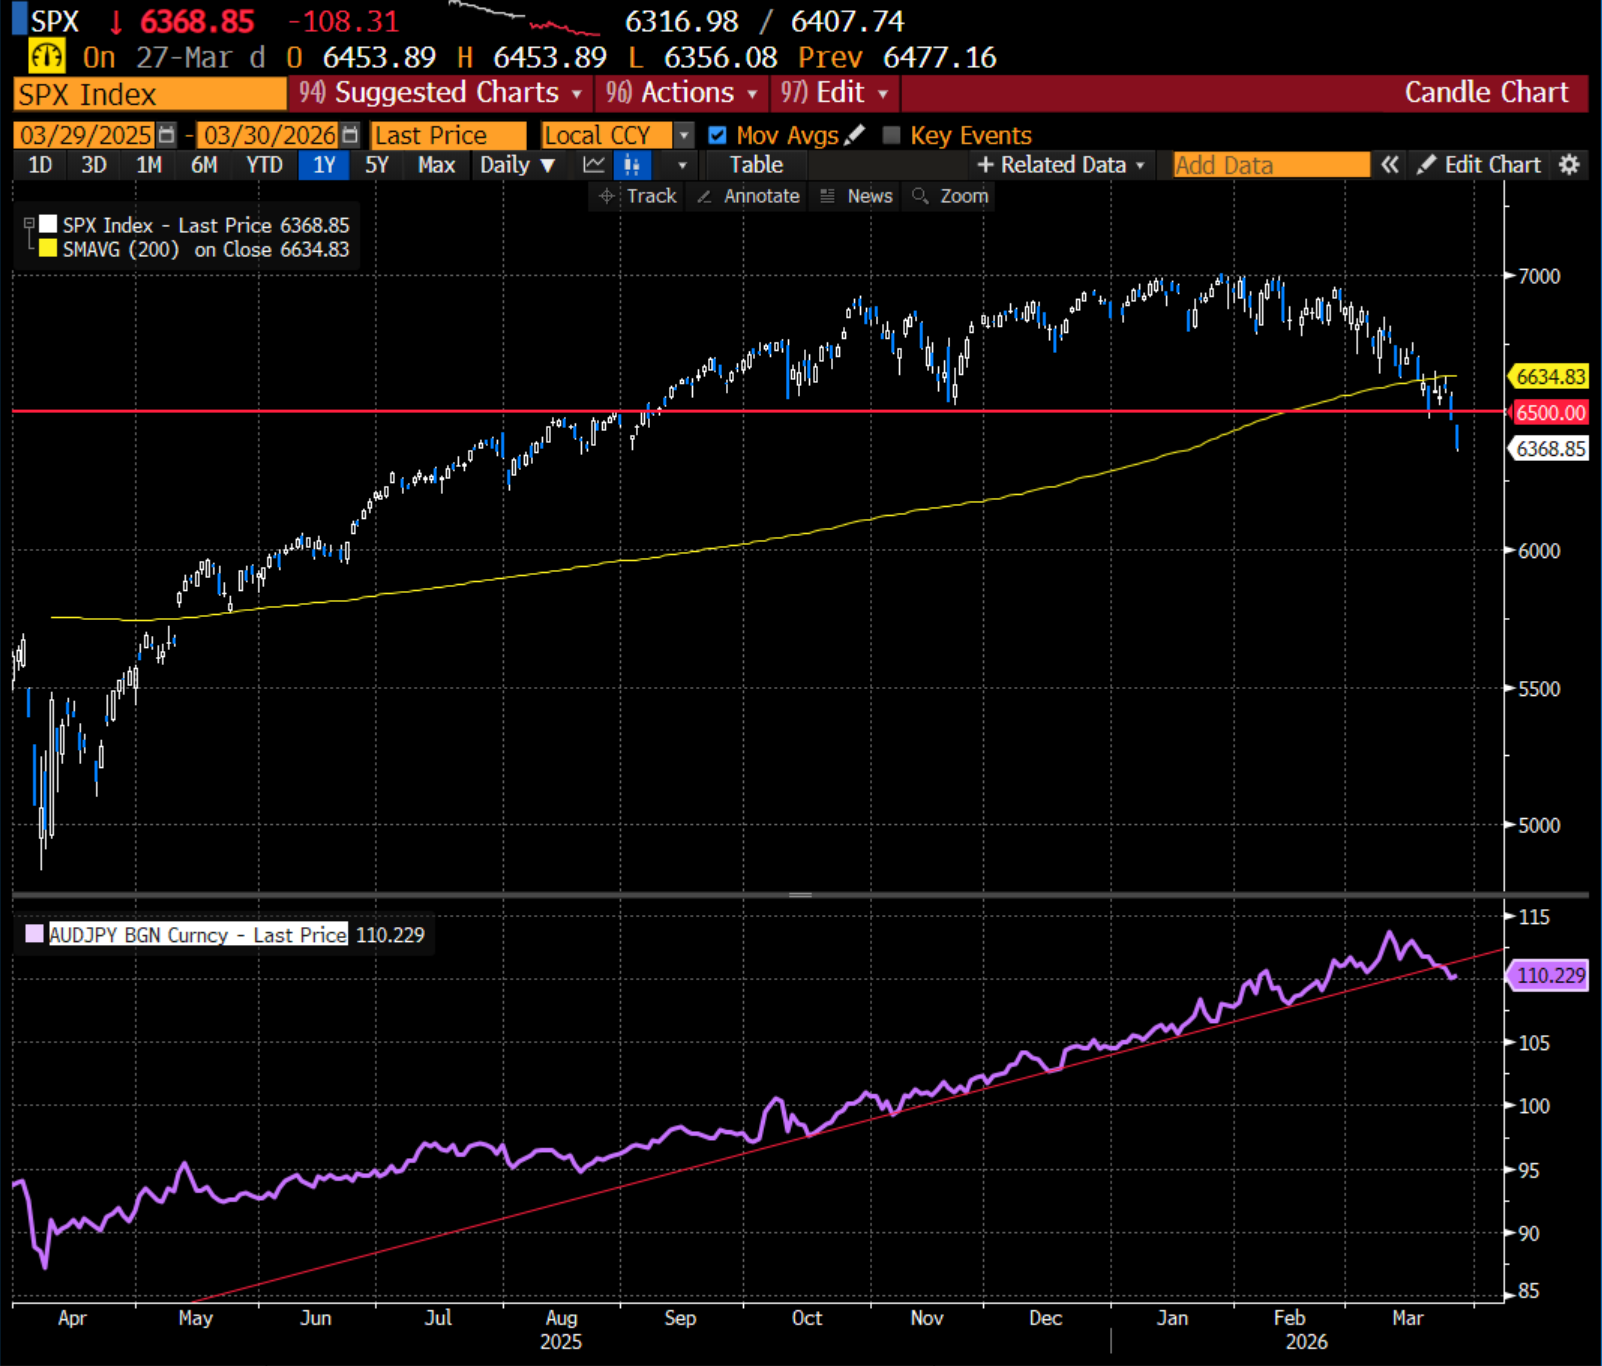
SPX first broke below the 200 DMA the week before. Last week, it closed below the key 6,500 level. AUDJPY, the classic risk barometer, confirmed the breakdown.
What is the plan this week?
Another week deeper and we are still expecting escalation. Global markets have entered more vulnerable levels. S&P sitting on the 200 DMA at 6,500. Brent above $110. Gold is just below $4,500 after crashing 10% in a week. The steep oil prices are seeping more and more into daily life and heading West. Even in the US, protests against the war and the “No Kings” movement are getting intense. The glimmer of hope for rationality is the only thing holding back the pace of portfolio destruction across all markets. Powell speaks at Harvard tonight, his first public appearance since the Fed held rates. Every word will be parsed.
The week ends with the US payrolls data. February printed -92K, the first negative since the pandemic. We are expecting a rebound but the real story is inflation and affordability taking all the priorities. ISM manufacturing on Wednesday is the test for stagflation. Prices paid were already at 70.5 before oil moved. If it breaches 75, the narrative shifts. Retail sales should rebound but nobody is celebrating a rebound funded by rising prices. NFP drops on Good Friday when US, UK, and EU markets are all closed. Any surprise sits over the Easter weekend with no ability to trade it until Monday.
In Europe, expecting higher flash CPI on Tuesday. The ECB is having a hard time managing rising bond yields and the growing pressure to hike rates to combat the situation. Swaps market now prices 65% chance of a hike in April, would be the first since September 2023. The BOE at 60%. The BOJ at 69%. If all three hike in the same week at end-April, it will be the most coordinated tightening since 2022. Central banks are being forced to tighten into a war. There is no playbook for this.
The energy crisis continues to split the haves and have-nots in Asia. Pakistan avoided blackouts by betting on Chinese solar panels. Bangladesh is still tied to the pipe. South Korea came into this crisis with 10 days of gas. Patience is running out and unrest can break out easily. A series of data from South Korea this week will tell us how the chips industry is handling the turbulence from supply to demand. China looks like it is managing the situation calm and calculated. The strength in renewables is claiming a real advantage. The Xi-Trump summit is now 6 to 7 weeks away so posturing will get more intense from here. Pakistan is reportedly hosting US-Iran talks, adding a new channel to the slim hope for a negotiated outcome.
It is difficult to watch the markets when you know it is one man, perhaps one administration of a superpower, taking the whole world into a humanitarian crisis. But this is the market we have. The plan this week. Xi-Trump and Pakistan talks are the two off-ramps. If neither works, stay long energy and short duration. If one does, flip fast. Size down for Good Friday.
What Did I Learn Last Week?
Mar 23: Eurozone consumer confidence plunged to -16.3 from -12.3, worst drop in a decade outside pandemic. Singapore CPI eased to 1.2% from 1.4%. Trump posted Iran talks were “very good and productive.” Brent crashed 11% to $99.94 in minutes. A $500 million sell order hit crude 15 minutes before the post. Israel struck 50+ targets across Iran.
Mar 24: PMI day. Eurozone composite held at 50.5, 10-month low. UK 51.0. Japan 52.5. None broke below 50 but all weakened. Japan CPI fell to 1.3%, below BOJ’s 2% target — subsidies masking pressure, core-core still 2.5%. Denmark voted: Social Democrats 21.8%, lowest in 120 years. Hungary held 6.25%. Chile held 4.5%, shelving cut on oil shock. Mexico CPI breached 4.02%.
Mar 25: Australia CPI 3.7% y/y, barely down from 3.8%. RBA third hike now live for May. UK CPI held at 3.0%, core ticked up to 3.2%. Germany IFO collapsed to 86.4, expectations worst since Russia-Ukraine invasion. Lagarde at ECB Watchers: “We will not be paralysed by hesitation.” BOJ January minutes: one member warned “should not take too much time.” US Q4 GDP confirmed 0.7% annualised.
Mar 26: OECD held global growth at 2.9% but raised G20 inflation to 4.0%, up 1.2 pp on energy. Sovereign downgrade shift did not fire. G7 called for de-escalation. Mexico cut 25bp to 6.75%, split 3-2. Norway held 4.0%, signalled hike next. South Africa held 6.75%.
Mar 27: China industrial profits +15.2% y/y Jan-Feb, pre-war data. UMich 53.3, inflation expectations 3.8%. Spain CPI 3.3% vs 3.7% expected. Trump extended energy strike pause to April 6. Houthis announced “first military operation.” 15+ US wounded at Prince Sultan Air Base. Sovereign ratings: Italy, Spain held. Brent back above $110.
All week: BYD record revenue but profit fell first time since 2021. Sinopec profit -36.8%. Ping An operating profit +10.3%. China Life +44.1% to record. Xiaomi, PetroChina, CNOOC, Hapag-Lloyd also reported. S&P down 1.4% Friday.
What To Look Out For Next Week
Mon Mar 30: Germany CPI, first major eurozone inflation print since the war. Bloomberg expects 2.6% vs 2.0% prior — pump prices up 16% m/m. If it prints above 3%, ECB April hike becomes near-certain. Powell speaks at Harvard. BOJ Summary of Opinions. Israel rate decision.
Tue Mar 31: China official PMIs — manufacturing expected 49.7, still contracting but improved from 49.0. Refinery run rates crashed to 78.3% after Beijing suspended fuel exports. Eurozone flash CPI expected 2.5% vs 1.9%. Nike earnings at 2017 lows near $50 support. Macron arrives in Tokyo.
Wed Apr 1: Q2 begins. ISM manufacturing expected 51.5–52.2 — prices paid the real story after spiking to 70.5 before oil even moved. If it breaches 75, stagflation pricing intensifies. South Korea exports expected +40% y/y on a 164% surge in chip shipments. BOJ Tankan expected 16. US retail sales. ADP. Supreme Court hears birthright citizenship.
Thu Apr 2: South Korea CPI expected 2.4% vs 2.0%, breaching BOK target. Switzerland CPI. US trade balance — deficit expected to narrow to -$46.1B on gold exports. Weekly claims.
Fri Apr 3: US payrolls, the most important print of the week. Expected +55–80K vs -92K prior. This is the cleanest read on whether February was weather or trend. Unemployment rate expected 4.4–4.5%. Markets closed for Good Friday. Turkey CPI 31.3%. Macron in Seoul.
All week: Earnings: Nike, PetroChina, Midea, China Vanke (record loss expected), Country Garden, Agricultural Bank of China, Bank of China, China Eastern Airlines.
Beyond Next Week
April 6: Trump’s Hormuz deadline. Markets closed. Any escalation hits thin liquidity Monday Apr 7. Binary outcome — power infrastructure strikes or another extension.
April 13–16: Bank earnings. JPMorgan, Goldman, Citi, Wells Fargo, Bank of America in four days. First corporate read on war damage to credit, trading revenues, and loan provisions.
April 27–30: Central bank week. FOMC Apr 28–29, BOJ Apr 27–28, ECB Apr 30, BOE Apr 30. Four major central banks in four days. If BOJ and ECB both hike, it is the most coordinated tightening since 2022.
May 14–15: Trump-Xi summit in Beijing. Rescheduled from late March. Gave argues the war should force both sides toward compromise — solar panels, rare earths, renminbi revaluation, Boeing orders. The most consequential bilateral meeting of the year.
April 27 – May 22: UN NPT Review Conference. Nuclear non-proliferation treaty review in New York. After the Bloomberg piece on proliferation cascades — South Korea, Japan, Saudi Arabia all debating the bomb — this is where the diplomatic fault lines surface.
Regimes
Structural damage meets ceasefire optionality. South Pars and Qatar’s force majeure are permanent. That does not reverse with a deal. But the vol regime has shifted from one-way to two-way. Trump’s Iran post moved Brent 11% in minutes. The market is no longer just pricing damage. It is pricing the possibility of a deal alongside the damage. That changes how you position. Long energy still works but you need to be faster and lighter. Hedging cost has doubled in two weeks. changed
Rate repricing is crowded on both sides. ECB 65% hike end-April. BOE 60%. Fed 60% hike by year-end. The moves have happened. The question now is who blinks first. Bloomberg Economics says oil shocks barely touch core PCE. German pump prices (+16% m/m) and eurozone input costs at three-year highs say otherwise. This standoff breaks this week. Eurozone CPI Tuesday. ISM Wednesday. NFP Friday. changed
Dollar bid but running out of reasons. BWCI biggest decline since July. AUD worst G10, sterling best. Yuan fixing at strongest since April 2023. Beijing positioning ahead of Xi-Trump. The war premium keeps the dollar bid. Remove the war premium and the structural short reasserts. held
Credit stress is waiting for a trigger. The regime is intact but nothing new has broken. Airlines, Vanke, private credit gating, regional banks in correction. All still there. The next leg needs either oil above $130 or a credit event outside the usual suspects. Watch CLOs. held
Shifts (if → then)
April 6 passes without Hormuz reopening → Strikes escalate. Oil $130–150. This week is binary. new
Eurozone CPI above 2.8% Tuesday → ECB April hike locked in. Bund 2yr to new highs. new
NFP above +150K Friday → February’s -92K was noise. Hike pricing accelerates. Good Friday liquidity amplifies. new
ISM prices paid breaches 75 Wednesday → Stagflation intensifies. Already at 70.5 before oil moved. Replaces “PMIs break below 50” which did not fire. new
Xi-Trump produces Iran framework → Oil drops $20 in a day. Pakistan hosting US-Iran talks same week. Two channels open simultaneously. carried, probability rising
War finds off-ramp → Oil retreats, rate cuts snap back. But South Pars, Qatar force majeure, and supply chain damage do not reverse. The $500 million trade says someone is already positioning for this. carried, probability rising for the first time
Tails
Hormuz closed through Q2. $150+ oil. Demand destruction. Water scarcity. April 6 deadline makes this closer. carried
Houthis operational. Announced “first military operation” this week. No longer a tail in the traditional sense. If Bab al-Mandab closes alongside Hormuz, two chokepoints shut. changed, upgraded
Sudden ceasefire. Oil crashes 20–30% in hours. Pakistan talks and Xi-Trump same week. Risk is being caught short on a headline. new
Saudi infrastructure hit. Aramco or Yanbu pipeline. Different category of war. carried
Private credit contagion. Gating spreads. CLOs stall. Active watch since 16 March. carried
Russia targeting intelligence to Iran. Direct US-Russia confrontation. carried
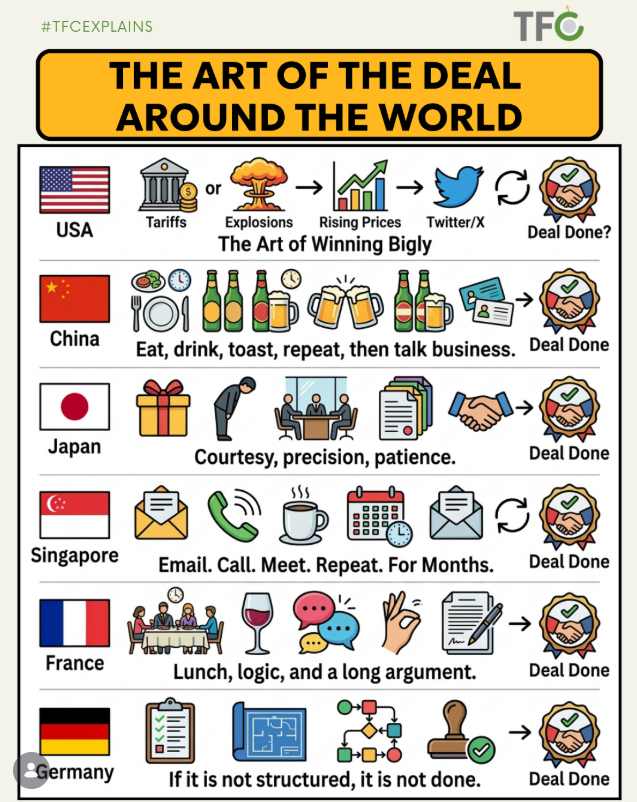
The Art of the Deal Around the World. The deal is rarely just the deal. USA: tariffs, explosions, rising prices, Twitter. China: eat, drink, toast, repeat, then talk business. Japan: courtesy, precision, patience. Singapore: email, call, meet, repeat, for months. France: lunch, logic, and a long argument. Germany: if it is not structured, it is not done. Trump deals like a New York real estate developer. The rest of the world does not.
The full edition includes 40+ curated charts and infographics with commentary.
For the complete visual edition, email hoelon at lengleng dot com
Best,
Hoelon