Powell’s Last Stand
Happy Sunday.
“Just so you know, thanks to the Supreme Court, some of that money is going back to China.” — Scott Bessent, US Treasury Secretary, to reporters following the Supreme Court ruling on tariff refunds. Refunds are paid to U.S. importers, not to China. The statement compresses a second order effect into a direct one. Yes, removing tariffs may lead to more imports over time, and some of that demand could flow back to Chinese exporters. But that is very different from money being sent to China. The framing blurs that line, and in a policy debate, that is unlikely to be accidental. The federal government is now refunding nearly $166 billion to American businesses under the IEEPA ruling.
“Never think that war, no matter how necessary, nor how justified, is not a crime.” — Ernest Hemingway.
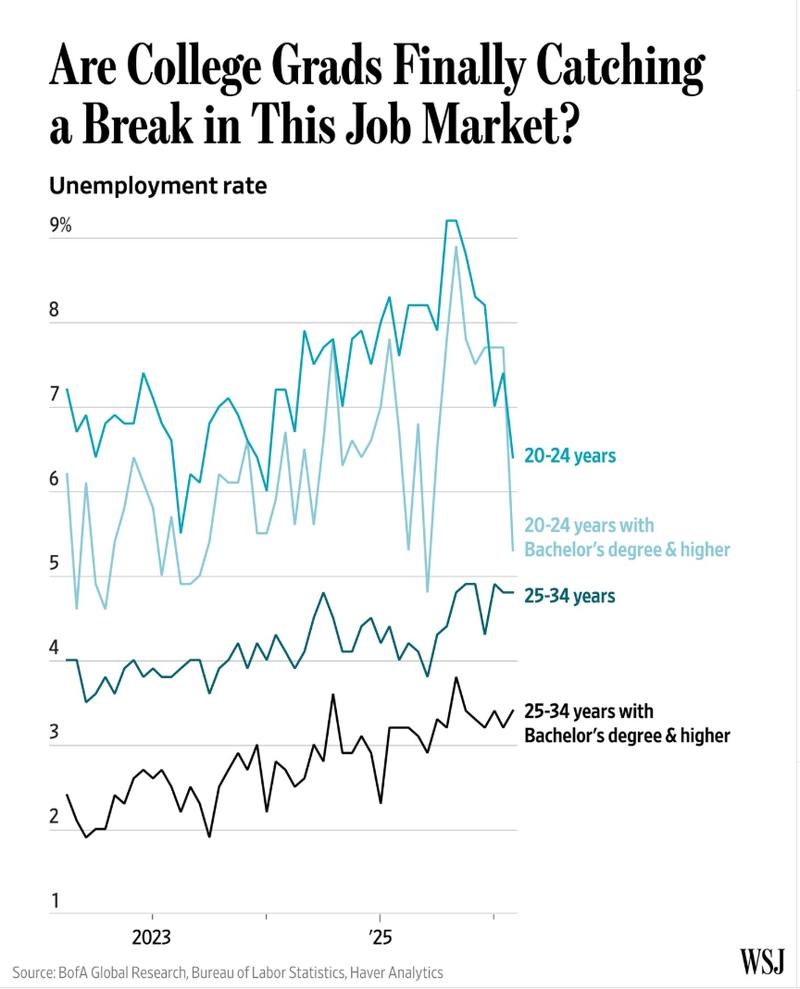
“Twenty years from now you will be more disappointed by the things that you didn’t do than by the ones you did do. So throw off the bowlines. Sail away from the safe harbor. Catch the trade winds in your sails. Explore. Dream. Discover.” — Mark Twain. Last week the unemployment rate for 20 to 24 year olds with bachelor degrees dropped sharply to 5.3% from a decade high of 8.9% last fall. Employers expect to boost new graduate hires by 5.6% this spring. The class of 2026 is graduating into a different world than the one their professors prepared them for. The barriers that gated the old career paths are being dissolved by AI. The industries opening up did not exist five years ago. The leap, when you make it, will not feel like a leap at the time. It will feel like the most natural thing in the world. The risk is not in trying. The risk is in waiting too long.
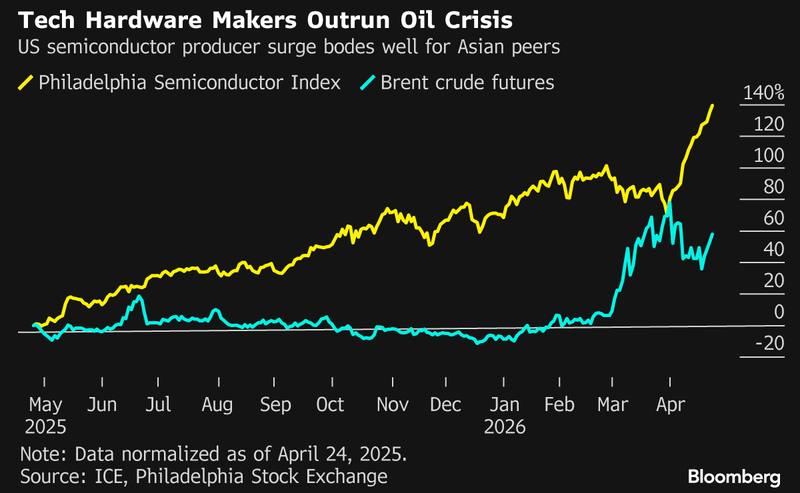
Tech hardware makers are outrunning the oil crisis. The Philadelphia Semiconductor Index has now strung together 17 consecutive sessions of gains, the longest streak on record, even as Brent crude has surged past $105. The chart captures the divergence the macro narrative is wrestling with. Records on the chip side, blockade on the energy side. The market has decided which one matters more for now.
What is the plan this week?
This is the heaviest week of the year. Powell takes his last seat at the Fed table on Wednesday, his term as chair ending May 15. The Justice Department dropped the renovation probe on Friday, clearing Warsh’s confirmation path. The live question is whether Powell stays on as a governor through January 2028, his right under the law, which would give a hawkish dissent voice inside the room as Warsh and Bessent shape what comes next. Records and warning signals are coexisting. The S&P at 7,165, Intel surging 24% on Friday, the Nasdaq at its fifth record close. At the same time the Stoxx 600 fell 2.5%, the high yield credit spread closed at 285 basis points for the first time since June 2007, the Strait of Hormuz remains blocked. Saturday night the WHCA dinner was evacuated after shots fired near the venue, the dinner rescheduled within thirty days. Independence is a fragile institution once someone decides to test it. The political violence layer just got added on top.
The central bank week is the heaviest of the year. Four major decisions in seventy two hours. The BOJ Tuesday, the Fed and BOC Wednesday, the ECB and BOE Thursday. All five expected to hold. The variable is tone. Lagarde will keep optionality alive and will not be forced into Trichet’s 2008 mistake. Bailey is walking a tightrope on gilt market nerves and Labour’s May 7 local election pressure on Starmer. Ueda will toe the government line and pave the path for a June hike to 1%. Powell will use his last meeting to defend the institution, not the rate. Fed funds futures have 30% chance of a cut by year end, down from 60% three weeks ago. Bessent’s comments on the Fed monitoring the supply shock have created political space for steady policy without inflicting a public clash. Watch the dot plot dispersion when it eventually moves under Warsh, that is the more material event for the cycle than this Wednesday’s hold.
Mag 7 dominates the earnings tape. Microsoft, Alphabet, Meta and Amazon all on Wednesday, Apple on Thursday, the day after Tim Cook’s succession to John Ternus was announced. The chart on the trillion-dollar club below sets the table for the prints. The cohort reporting Wednesday is the same cohort that built the concentration in the first place. Q1 GDP advance prints Thursday at a likely +2.0% rebound, March PCE deflator follows the same morning at +0.7% headline and +0.3% core. The capex commentary on the Mag 7 calls is the variable that the AI thesis rests on. Intel +24% on Friday already confirmed the demand side. The European tape diverged this week, Stoxx 600 -2.5% on the war taking margin out of airlines, retailers and manufacturers. Asia’s split holds. Korea Q1 GDP +1.7% q/q, the fastest since the pandemic, on chip exports up 151% y/y, while Indonesia, the Philippines and Thailand defend currencies and manage spillover. The yuan is at a three year high against the dollar, the PBOC quietly running an appreciation policy, and Beijing has been credited by Washington for helping push the ceasefire. The Xi Trump summit mid-May runs through that goodwill, or it does not.
One larger thought. The week’s narratives all point to the same place. Powell’s exit is the symbolic end of the post 2008 era of dovish first monetary policy. The Hormuz blockade is the slow rewriting of the supply chain map. The AI capex spend is the most concentrated industrial buildout since post war railways. The credit spread at 285bp is the quiet warning under the records. Each is a generational shift wearing a normal news cycle. The plan this week. I am generally bullish tech and short USD, looking for Tuesday’s corporate USD buying climax and the month end vol to add. The flip to short USD around mid morning Tuesday is the trade. Trim duration into the Fed, Powell’s tone is the last variable. If the Mag 7 capex guides hold, stay long quality AI exposure. If they soften, software pair trades against semis come into focus. Wait the binary, then re-engage. Size down for Wednesday.
What did I learn last week?
Mon Apr 20: Canada March CPI 2.4% vs 2.6% expected. Trump confirmed an Iranian flagged tanker named Touska tried to run the blockade and was repelled. Apple announced John Ternus succeeds Tim Cook as CEO from September 1. Amazon disclosed a $25B Anthropic deal with up to 5GW of compute, run rate revenue at Anthropic now over $30B from $9B at end 2025. CATL unveiled the third generation Shenxing battery cell, 98% charge in 6 minutes and a 1,000 km range. Russian Tuapse refinery hit again.
Tue Apr 21: Trump extended the Iran ceasefire indefinitely while keeping the blockade in place. Warsh hearing went ahead, calling for “fundamental policy reforms, a different use of Fed tools, a new inflation framework, and a regime change.” Retail sales +1.7% vs +1.4% expected. Pending home sales +1.5% vs +0.5% expected. GE blew it out at $1.86 vs $1.60 expected. RTX raised FY guidance, NOC and 3M beat, Halliburton beat, UAL beat but cut FY EPS.
Wed Apr 22: South Korea Q1 GDP +1.7% q/q vs +0.9% expected, fastest pace since the pandemic. UK CPI in line at 3.3%. German ZEW current situation crashed to -73.7 vs -70.5 expected. SK Hynix printed Q1 op profit 37.6T won. GE Vernova guided gas-power equipment backlog to at least 110GW by year end. IBM beat, ServiceNow beat, Lam beat. Eurozone consumer confidence -20.6 vs -17.2 expected. Bessent said Iran’s Kharg storage will be full in days and oil could have hit $150 without US sanctions.
Thu Apr 23: Intel surged 24% on Q1 $0.29 vs $0.01 expected, its biggest single day move in 38 years. UK April flash manufacturing PMI 53.6 (highest since May 2022). US S&P manufacturing PMI 54.0 (8th expansion month). Trump ordered the Navy to shoot any boats laying mines in Hormuz. Newmont raised buyback, Dow disclosed a 2.5 to 3 year replacement lead time on damaged Qatar LNG and announced May polyethylene price hikes of 20cpp. Tokyo CPI ex-fresh food +1.8% core.
Fri Apr 24: DOJ dropped the Powell probe, clearing Warsh’s path to confirmation. German Ifo 84.4, lowest since 2023. UMich confidence final 49.8. Israel PM Netanyahu underwent treatment for an early stage prostate tumor. Google announced a $10B to $40B Anthropic deal with up to 5GW of compute. The S&P closed at a record 7,165, Intel held its session high, the SOX index made it 18 consecutive sessions of gains. Brent finished the week at $105.
All week: S&P +0.6%, Nasdaq +1.5%, DJIA -0.4%. Brent +15%. AI capex confirmed by Intel, IBM, ServiceNow and the Anthropic mega deals. Mid East stalemate persists. European stocks lost their year to date outperformance over the US. The HY OAS closed the week at 285bp, last seen seven months before the Great Financial Crisis. WHCA shooting Saturday night.
What to look out for next week?
Mon Apr 27: China March industrial profits expected +14.9% YTD. Pakistan SBP rate decision expected hold at 10.5%. Singapore industrial production. Germany GfK consumer confidence. Israel-Lebanon 10-day ceasefire is set to expire. King Charles III and Queen Camilla begin a state visit to the US through Apr 30. UN opens five-yearly Nuclear Non-Proliferation Treaty review. Elon Musk’s OpenAI lawsuit jury trial begins in Oakland. TSMC 2nm trade-secrets verdict in Taiwan.
Tue Apr 28: BOJ rate decision expected hold at 0.75%, June hike telegraphed. Hike odds collapsed from 75% three weeks ago to under 7%. US Conference Board consumer confidence expected 90.0. Case-Shiller home prices. Chile and Hungary rate decisions. Japan unemployment, India IP. Earnings: General Motors, Coca-Cola, Visa, Booking, Pfizer, BP, BYD, Foxconn Industrial, Maruti Suzuki, Advantest.
Wed Apr 29: Fed FOMC rate decision expected hold at 3.50-3.75%, Powell’s likely last meeting as chair. Bank of Canada expected hold at 2.25%. Australia Q1 CPI expected +4.2% y/y from 3.6%. UK Nationwide house prices. Spain HICP, Germany HICP. Bank of Thailand expected hold at 1.00%. Earnings: Microsoft, Alphabet, Meta, Amazon, Boeing, Caterpillar, GSK, ADP, Volkswagen, Mercedes-Benz, Cambricon, Geely, Bank of China, ICBC, ABB, Lloyds.
Thu Apr 30: ECB rate decision expected hold at 2.00%, Lagarde keeps options open. BOE rate decision expected hold at 3.75%, expect 7-2 vote. US Q1 GDP advance expected +2.0%. US PCE expected headline +0.7% m/m, core +0.3% m/m, y/y core to 3.2%. Employment Cost Index Q1 expected +0.8%. Jobless claims. Eurozone Q1 GDP expected +0.2% and April CPI expected 2.8%. France, Spain, Germany, Italy Q1 GDP. South Korea IP. Japan IP. China official PMIs. Taiwan Q1 GDP expected +10.5%. India IP. Earnings: Apple, Mastercard, Amgen, ConocoPhillips, Comcast, Royal Caribbean, Standard Chartered, DBS, Hindustan Unilever, Samsung Electronics, Saudi Aramco.
Fri May 1: US ISM manufacturing expected 52.2. US auto sales expected 16.0M. Tokyo CPI April expected core 1.8% from 1.7%. South Korea exports April expected +54% y/y. China RatingDog manufacturing PMI. Sovereign ratings: Ireland, Qatar review. Earnings: Exxon Mobil, Chevron, AbbVie, Linde, ICE, AB InBev, BNP Paribas, Société Générale, T-Mobile, Reddit. Japan Golden Week begins.
All week: Over 60 S&P 500 companies report including five Magnificent Seven. Plus 3M, Adidas, AbbVie, Aflac, Airbus, ArcelorMittal, Astellas, AstraZeneca, Banco Santander, BASF, BNP Paribas, BP, Chevron, Coca-Cola, ConocoPhillips, Deutsche Bank, Eli Lilly, Exxon, Ford, Foxconn, GE HealthCare, GM, Honeywell, HSBC, KLA, Komatsu, Mastercard, Mondelez, NXP, P&G, Pfizer, Qualcomm, Reddit, Roblox, Saudi Aramco, Samsung, Spotify, Standard Chartered, Stellantis, Toyota Industries, T-Mobile, UBS, UPS, Verizon, Visa, Volkswagen.
Beyond next week
May 5: RBA rate decision. Futures pricing roughly 75% chance of a third consecutive hike, the most aggressive G10 path of the year.
May 7: Mexico Banxico decision. UK local and mayoral elections, a poor showing for Labour increases political pressure on Starmer.
May 12: Australian 2026/27 budget. US April CPI lag effect data point.
May 14-15: Xi Trump summit in Beijing. Trade, Taiwan, Iran, rare earths. Beijing has been credited by Washington for helping push the ceasefire.
May 15: Powell’s term as Fed Chair ends. The live scenario is Powell stays on as governor through January 2028, which is his right under the law and which would give a hawkish dissent voice inside the FOMC even after Warsh takes the chair.
Mid June: Warsh’s first FOMC with the Summary of Economic Projections re-thought. Watch for a possible Bessent Warsh accord and any shift in the inflation targeting framework. Markets will be sensitive to any formal erosion of central bank operational independence.
Later in May: OPEC+ ministerial. Physical crude at records, Hormuz flow metered. Any quota increase validates supply as the binding constraint.
Q3/Q4: The financing squeeze nobody is pricing. $10 trillion US Treasury refinancing, $2 trillion deficit, $2 trillion corporate debt rolling. The crunch lands in autumn.
Regimes
Credit stress sharpening, HY at pre-GFC level. The HY OAS at 285bp matches levels last seen at the June 2007 cycle low, seven months before the Great Financial Crisis. Banks all delivered last week. Q1 numbers do not show the war yet, Q2 is the real test. Private credit contagion via Blackstone and the BDC complex is the channel to watch. The single most important data point of the week is not in the macro calendar. changed, week 1
War in stalemate, Hormuz blockade is the binding constraint. Iran extended ceasefire indefinitely, but the blockade remains tight and Brent surged to $105. It has been called the biggest energy disruption ever. The truce does not equal de-escalation when the supply chain stays cut. held, week 2
Rate repricing: still confused, broadening. PPI gave the doves room. PCE Thursday is the next test. Empire prices paid jumped to 51, services PMIs are running hot. The Fed has had to back off the dovish tilt that briefly returned. Stagflation remains the lens. held, week 7
Dollar bid fading, but trap risk remains. The dollar made its longest losing streak in fifteen years. Bessent comments creating space for Warsh continuity. The April retreat after the March rally leaves the dollar oversold, consolidation or a bounce looks likely before the medium term decline resumes. held, week 6
Shifts (if → then)
China Iran intelligence confirmed before Xi Trump → Summit agenda poisons, decoupling accelerates, rare earth restrictions return. carried
Mag 7 capex guides confirm AI investment trajectory → Equities extend, software re-rates, hyperscaler beta runs another leg. new
Mag 7 capex guides disappoint or pause → AI beta cracks, software unwinds, software vs semis pair compresses. new
Apple iPhone China beats and services accelerate → Apple catches up to Mag 7, narrative widens beyond hyperscalers. new
PCE prints above 0.3% core m/m → Cut odds compress to zero, dollar bounces, gold pulls back, duration sells. new
BOJ surprise dissent or hawkish forecasts → Yen rallies hard, JGB very long end sells off, USDJPY 159.50 fails. new
Powell signals dovish at his last meeting → Curve flattens, gold extends, dollar breaks the recent range. new
Tails
Hormuz blockade extends through Q2, $150+ oil. Energy shock cascades into rates, margins, profits. Probability rising. carried, upgraded
Powell stays on as governor through 2028. Warsh chair plus Powell as hawkish dissent inside the FOMC. Reduces the Bessent Warsh accord risk but adds two-track signalling that markets struggle to read. new
Bessent Warsh formal accord reshapes Fed independence. Markets reprice institutional risk premium. Bonds sell off, gold rallies, dollar weakens structurally. Mid June FOMC is the first window. new
Cash for uranium $20B deal closes quickly, Hormuz fully reopens. Oil crashes to the $60s, rate cut path reopens, dollar weakens sharply, multi-asset risk-on extends. carried, declining
Private credit contagion in the BDC complex. HY at 285bp is the prelude. Blackstone reported Thursday last week without a crack, but the spread is the more honest signal than any earnings line. carried, upgraded
Mythos class AI exploits financial infrastructure. Anthropic’s model demonstrated capability earlier this month. Wall Street emergency meetings already happened. carried
WHCA shooting opens broader political violence cycle. Risk premium lifts on US policy assets, equities reprice tail risk, gold continues. new
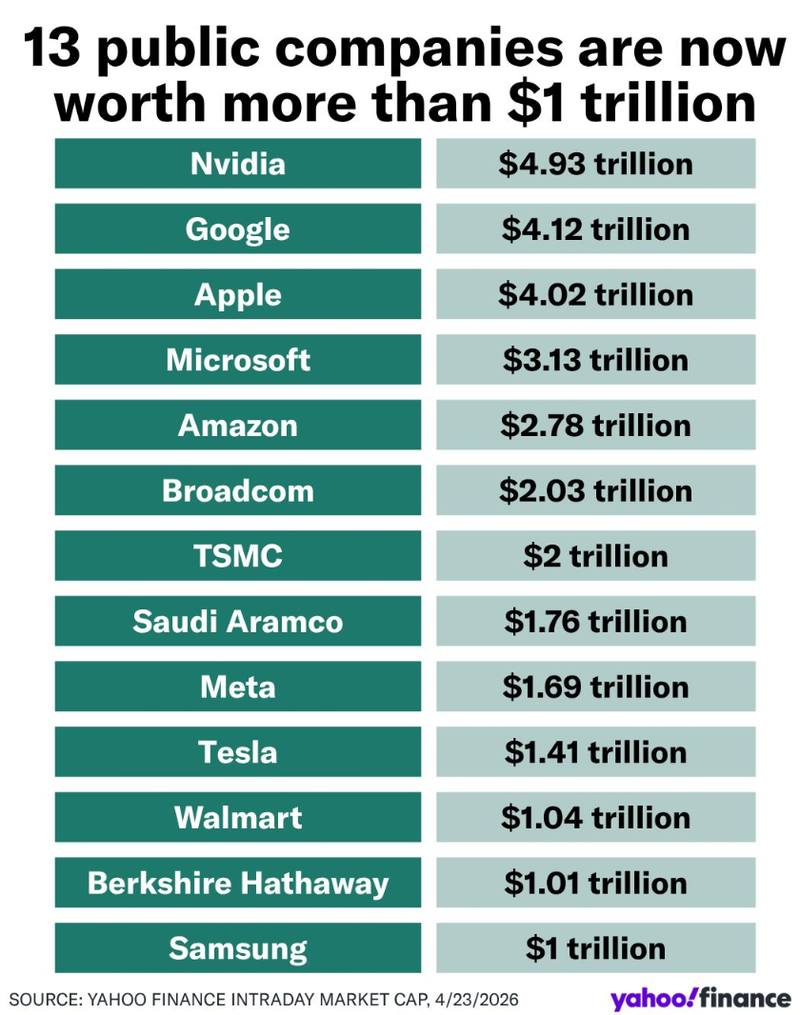
The trillion dollar club has 13 members. Nvidia at $4.93T, Google $4.12T, Apple $4.02T, Microsoft $3.13T, Amazon $2.78T, Broadcom $2.03T, TSMC $2T, Saudi Aramco $1.76T, Meta $1.69T, Tesla $1.41T, Walmart $1.04T, Berkshire $1.01T, Samsung $1T. Five of these names did not exist as public companies fifteen years ago. Concentration is the dominant feature of modern equity markets, and the cohort reporting earnings this week is the same cohort that built the concentration in the first place.
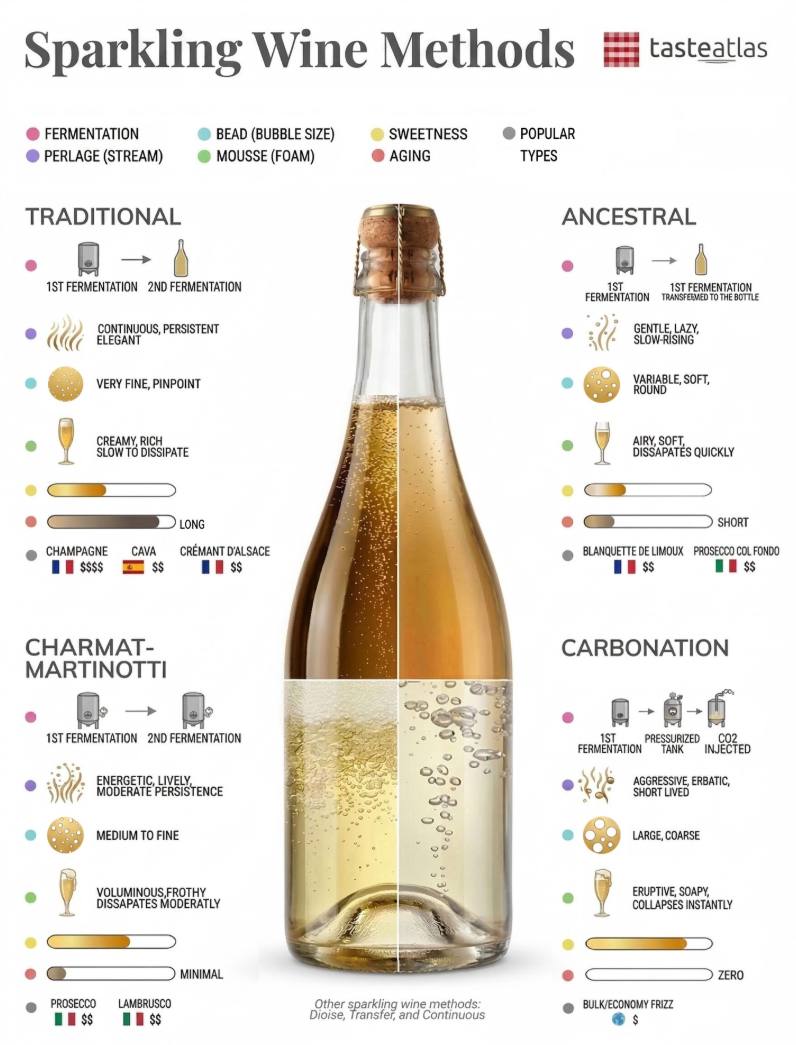
Bubbles never lie. The size, speed and structural integrity of the carbon dioxide in your glass is a physical blueprint of how the wine was handled. Traditional Method ferments inside the bottle for months, producing a microscopic bead and creamy mousse. Charmat-Martinotti uses pressurised steel tanks for crisp youthful fruit. Ancestral Method bottles before fermentation finishes, gentle and lazy. Carbonation injects industrial CO2 into still wine, coarse and short lived. Four very different cellars, four very different beads. The same applies to the markets you watch this week. The headline rally is one bead size, the structural one is another, they come from very different cellars.
The full edition includes 30+ curated charts and infographics with commentary.
For the complete visual edition, email hoelon at lengleng dot com
Best,
Hoelon