Switch of Guards
Personal views and market commentary. Not investment advice. Not associated with any employer or firm.
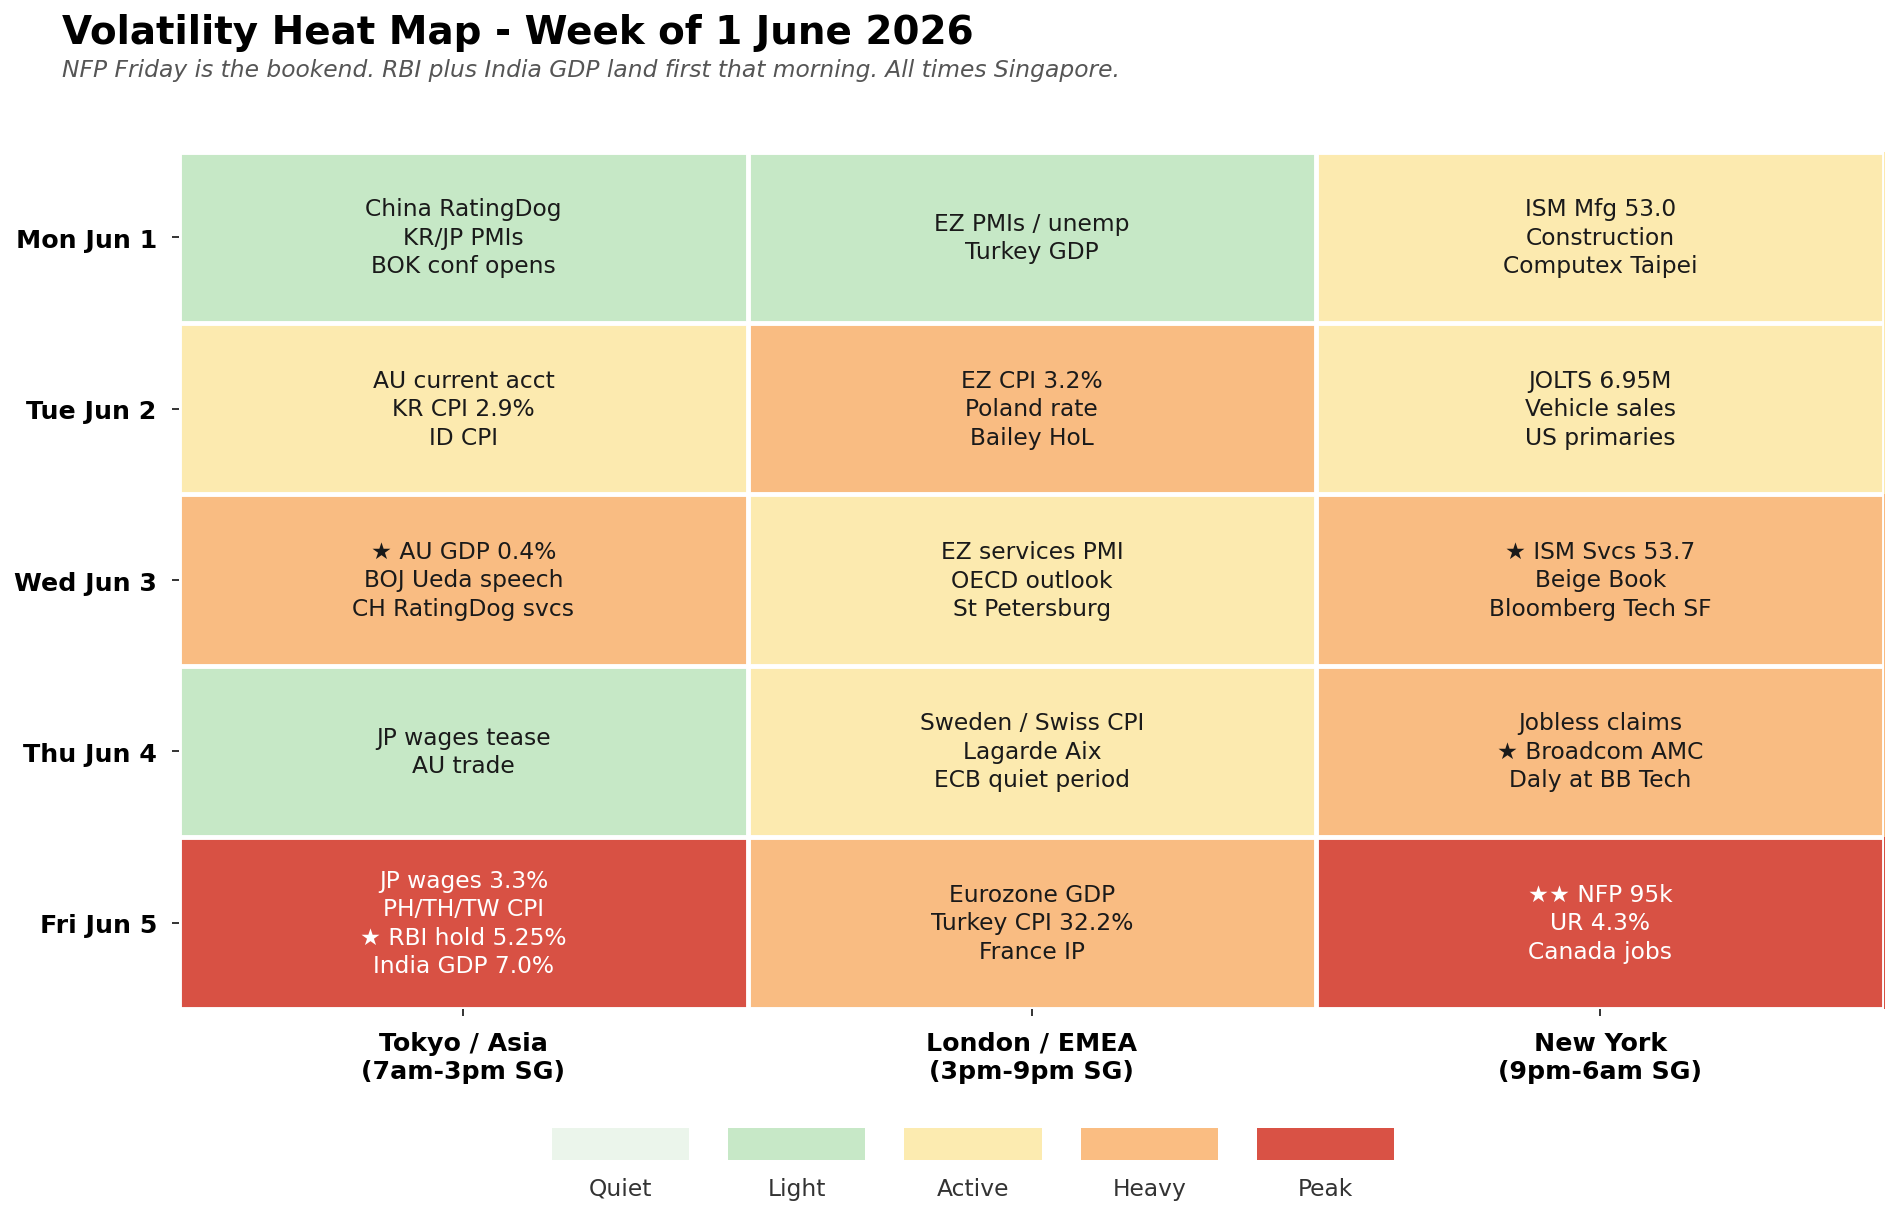
Volatility heat map for the week ahead, all times Singapore. Friday is the pivot, with NFP in New York stacked on RBI and India GDP in Asia the same morning. Wednesday is heavy globally — Australia GDP and BOJ Ueda in Asia, the OECD outlook and St Petersburg in EMEA, ISM Services and the Beige Book in New York. Tuesday EMEA carries the eurozone CPI cluster. Thursday's marquee is Broadcom after the New York close.
"Take the horse next to the door, or none at all." — attributed to Thomas Hobson, Cambridge livery stable, c. 1631. Hobson’s rule was a choice that was no choice. Warsh inherits the same door. Inflation will not let him cut. The yield curve, the dollar and the political calendar will not let him hold. Growth will not let him hike without breaking something. The bond market has done some of his work already. The trade is to size around which horse the stable hand finally walks out.
"I have no doubt that these companies are going to get filthy rich, but is it going to be good for children? Is it going to be good for parents? Is it going to be good for the American worker?" — Senator Josh Hawley (R-MO), May 28, 2026. The line catches the populist wedge running through the midterm calendar. A growing cohort of voters does not care whether ChatGPT is useful or whether Waymo is efficient. They see AI as another elite project to resist. Anti AI candidates are already positioning for 2028 to differentiate themselves from JD Vance. Trump owns the timing problem now. The AI capex regime that has been the equity tailwind for two years is moving into the political risk discount column.
"There is a danger of fragmentation of the international community and a regression to the law of the jungle." 重返「丛林法则」秩序的危险。 — Xi-Putin Joint Statement, "Formation of a Multipolar World and a New Type of International Relations," Beijing, May 21, 2026. The phrase 丛林法则 carries weight in Mandarin that flattens in English. It is the explicit accusation that the 1945 order has degenerated back to the pre WWII state of nature in which the strong simply take. The statement also called out unilateral coercion, hegemonism, bloc confrontation and neocolonialism. Trade was mentioned 33 times. The 50 billion cubic metre Russia China gas pipeline conversation was on the table. The investment expression is gold, RMB internationalisation, and the deepening Asian energy axis.
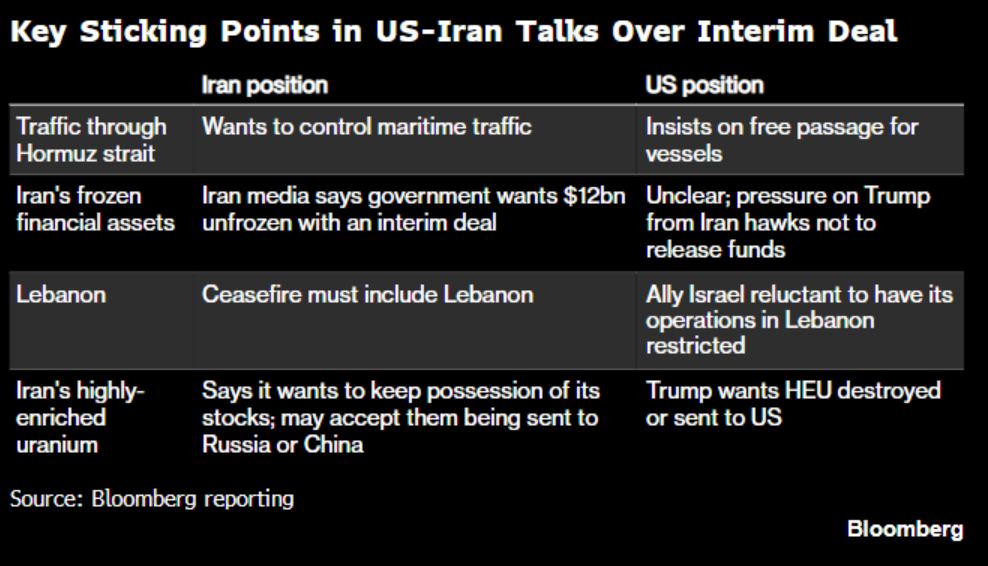
Trump moves toward the Iran deal, the market pricing it as if signed. Tehran open to enriched uranium concessions. Witkoff and Lavrov drafting a back channel framework. The OPEC+ communique walked back the production cut path. The question is no longer whether a deal is announced, it is on what terms and whether Hormuz physically reopens within four months. Adnoc says full flows do not return before Q1 2027. The deal trade and the supply trade are not the same thing. Source: Reuters / Polymarket.
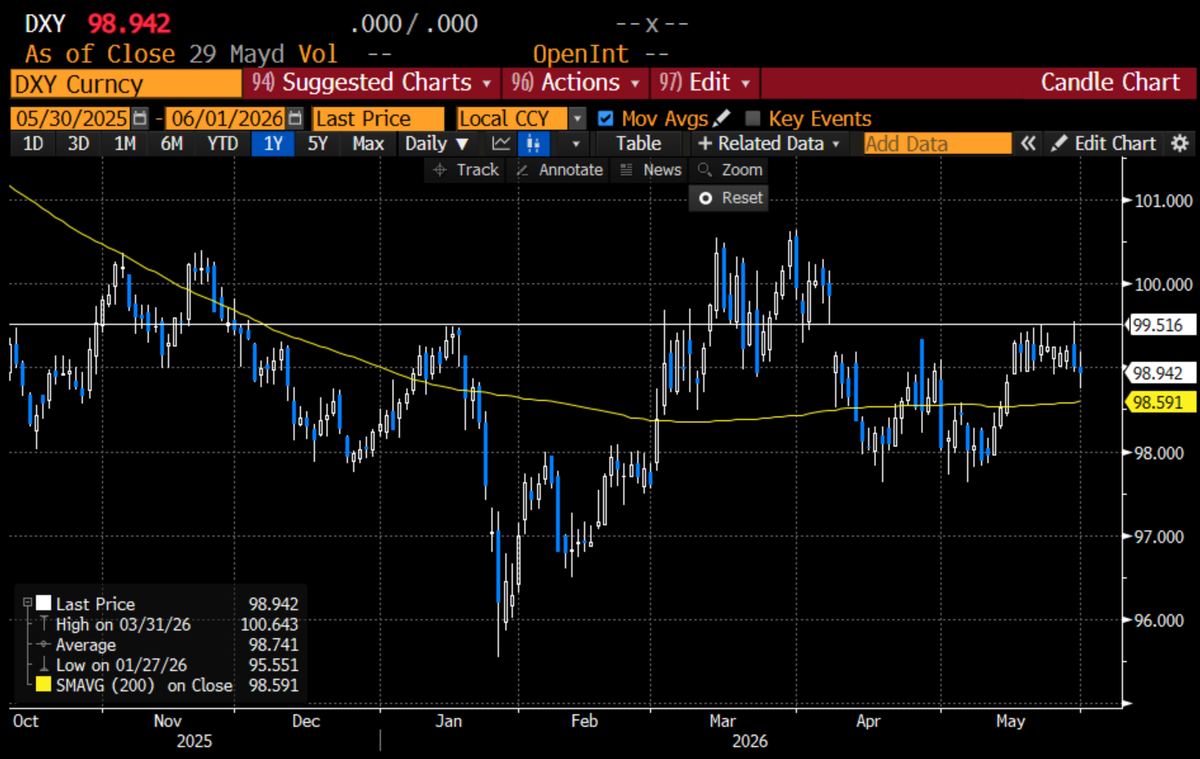
The largest question on the market is now the USD. Sell in May did not come. The USD is back in range now that the April 7 gap has completely closed. Source: Bloomberg.
What is the plan this week?
Entering the last month of the first half of 2026. As I scroll through the performance of markets, it is still striking to see the Taiwan index rallied 50% and Korea and Japan 30% each, and how the currencies are extremely stable. My old school thinking of being bullish the currency along with sentiment is laughable. It is all about flows. Almost every equity bought is probably FX hedged, which means net flow out of these countries is even bigger net net. Currencies that have moved large, BRL (15% including carry), ILS (20%), CNY (6%), are all real flows quietly passing through daily. The MOU resolution is the backbone of the week, now assumed done, even as the 38% probability of Hormuz reopening by end June reads less optimistic than the market is positioned for. The weekend brought renewed US-Iran military confrontation and Israel expanded its Lebanon invasion, adding tension under the assumed deal. When the ME conflict subsides, interest rate differentials and the shift of central bank tone will push flows in the coming months. Oil restocking keeps oil elevated but inflation expectations will be different across countries.
The biggest elephant is still what Warsh is going to lean on. Dovish or less dovish, and data dependent. This week we get a series of ISM and employment data setting the scene for the first FOMC. NFP will measure the health of the labour market and the worries about AI taking jobs. The Main Street versus Wall Street divide keeps widening underneath the headline US growth, labour income share declining, consumer sentiment softening, while equity indices keep printing records. Long end yields fell recently around the Memorial Day seasonality but will be back in the discussion. The question is whether inflation is transitory and there will be demand destruction, or we see wage pressure from the wealth effects, which is by far the reason why market sentiment is invincible.
European CPI is very key. The ECB June hike is now almost a done deal, yet EUR has been consistently sold despite the rate path. Most people still have Europe as the weakest link globally but the stock markets and currency are defying all claims. The deeper story is the $12.4 trillion of European capital parked in US assets, $10.4 trillion in US stocks (up 91% in three years) and another $2 trillion in US Treasuries. The hedged carry on holding US assets has turned negative for euro investors. European earnings have matched the US ex Mag 7 over the decade, with Q1 the strongest in three years and the STOXX 600 offering wider yield gaps than the S&P or Nasdaq. Any rotation out of US large caps is a mechanical EUR bid. SoftBank backing France on datacentres is the biggest upside in a while given Europe has been slow.
Australia and New Zealand have completed the switch of guards. The RBA paused after three hikes in 2026 with a dovish lean as April CPI eased to 4.0% on fuel-tax rebates. The RBNZ surprised the market last week with a hawkish hold and a revised inflation track. Australia Q1 GDP on Wednesday is the next read, expected 0.4% QoQ from 0.8% in Q4, with the housing top end already rolling.
In Asia there are inflation measures across the board. China is doing its own thing, with currency and bond markets rallying strongly. The 5 year swap broke lower out of the last 9 months range while global yields are headed the other way. RBI this week, expected to hold for another meeting but could lean as hawkish as any other central bank of late. A lot of rate hikes expected across the region, that is the only way.
The plan this week is to see how the US data holds up. The retracement of long end yields, Fed pricing and oil at the low is challenging the long USD view. We probably missed the narrow window for participants to take profit on equities before the summer lull. Maybe it turns to a carry play while skating around the inflation fears, especially if Warsh manages to suppress the committee. Beyond the USD, AUDNZD lower, EURJPY higher, CNH outperformance are the lesser disturbed, lower volatility channel of flows. JPY intervention is looking less effective and the risk is JPY grinds weaker toward fundamentals again, with the BOJ June hike now almost a done deal.
What did I learn last week?
Mon May 25: US Memorial Day, markets closed. UK and Hong Kong also out. Singapore April CPI lifted to 2.9% from 1.8%, the imported energy passthrough doing its work. Israel cut 25bp to 3.75%, the shekel's 20% surge giving the Bank room. Mexico trade. Thailand customs. The Hajj began in Mecca. Anthropic's Christopher Olah at the Vatican for Pope Leo's first encyclical on AI and human dignity.
Tue May 26: US Conference Board consumer confidence printed soft at 91.5 vs 92.0e, the household read tracking the cost of living straight down. Sri Lanka surprised with a 100bp hike to 8.75%, the EM signal. Quad foreign ministers in New Delhi with the Middle East crisis sitting next to Indo-Pacific security on the same agenda. Treasury 2-year auction at $69B. Trump checkup at Walter Reed. Xiaomi YU7 GT unveiled. ONGC, Fisher & Paykel Healthcare earnings.
Wed May 27: Australia April CPI eased to 4.0% on fuel-tax rebates. China April industrial profits accelerated to 19% YoY, YTD 16.4%. RBNZ held at 2.25% with HAWKISH guidance and a revised inflation track — the surprise that triggered the AUDNZD breakdown. Salesforce beat. Fed Cook on AI at Stanford. BOJ-IMES Conference opened in Tokyo, Ueda and Kashkari on the panels. France consumer confidence soft. Treasury 5-year auction at $70B.
Thu May 28: The PCE day. April PCE printed 0.4% headline, 0.3% core, year-on-year headline 3.8% and core 3.3%, right on consensus, no escape valve for the Fed. Q1 GDP second estimate revised to 2.1%. April durable goods +3.0% on Boeing. Jobless claims subdued. BOK held at 2.50% with hawkish signal. SARB hiked 25bp to 7.00%. ECB April account showed the Council closer to a June hike than the curve was positioned. Putin opened the Eurasian Forum in Astana. Dell printed the marquee earnings shock on AI servers, the stock +33% on Friday, biggest one-day gain ever.
Fri May 29: Tokyo May CPI 1.5% steady, BOJ June hike kept on the table. Eurozone CPI cluster — France 2.9%, Spain 3.5%, Italy 3.2%, Germany 2.8%, confirming the ECB June print. Canada Q1 GDP +1.3% annualised. Bessent at the Reagan National Forum, signalled Fed pressure escalating. Shangri-La Dialogue opened in Singapore, Hegseth attending. France, Hungary and South Africa sovereign rating reviews. SK Hynix and Micron joined the trillion-dollar club. Costco beat.
All week: S&P flat, Nasdaq +0.8% on Dell + Nvidia, Dow lagged on rate concerns. DXY filled the April 7 gap, back in the 99-100 range. US 30-year closed Friday at 4.97%, off the early May spike. EURUSD 1.1654, highest weekly close in over a year. AUDNZD through the 1.2139 cloud into the air pocket. USDJPY 159.26. Dell the marquee. Russia-China gas pipeline signals picked up out of Astana.
What to look out for next week?
Sun May 31: China official PMIs landed mixed. Manufacturing 50.0 held the threshold from 50.3. Non-manufacturing 50.1 beat from 49.4. Composite 50.5 from 50.1. Holiday disruptions damped factory; festival spending supported services.
Mon Jun 1: US ISM Manufacturing 53.0e from 52.7, construction spending 0.1%e. China RatingDog Manufacturing PMI 51.3e from 52.2. South Korea exports +55.5%e on AI chips, Pakistan CPI. Eurozone manufacturing PMI, unemployment, inflation expectations. Switzerland GDP, Turkey Q1 GDP 3.1%e. Bank of Korea International Conference opens in Seoul. Choose France summit at Versailles. Computex pre-show in Taipei. Atlantic hurricane season opens.
Tue Jun 2: Eurozone CPI 3.2%e from 3.0%, core 2.3%e, the last inflation print before the ECB June 10-11 meeting. South Korea CPI 2.9%e, Indonesia CPI 3.1%e. US JOLTS 6.95Me, vehicle sales 16.0M. Poland rate decision. Yellen at Brookings on Powell's tenure. Kashkari at BOK conference, Hammack at Cleveland City Club. Bailey before House of Lords. Israel-Lebanon talks resume in Washington. US congressional primaries, CA, IA, MT, NJ, NM, SD.
Wed Jun 3: Australia Q1 GDP 0.4% QoQ from 0.8%, the housing top-end already in decline. US ISM Services 53.7e, factory orders, durable goods, Beige Book, ADP. BOJ Ueda Kisaragi-kai speech in Tokyo, the June bias read. OECD outlook released at ministerial council. Bloomberg Tech Summit opens San Francisco, AI and hyperscaler capex the theme. St Petersburg Forum opens, Saudi Energy Minister attending. Bessent testifies on Treasury budget to Senate Finance. NBA Finals begin.
Thu Jun 4: Broadcom and Lululemon earnings AMC, the AI tape and the consumer tape side by side. Sweden CPI 1.2%e, Switzerland CPI 0.6%e, last reads before SNB June 18. US initial jobless claims 218k, eurozone retail sales. ECB enters quiet period ahead of June 10-11. Lagarde speech in Aix-en-Provence. SF Fed Daly at Bloomberg Tech Summit. Bailey at IA conference. RBA Bullock before Senate Economics. Netflix AGM, Hastings steps off board.
Fri Jun 5: The NFP day. US Nonfarm Payrolls 95k expected from 115k, unemployment 4.3% held. India GDP 7.0%e from 7.8%, then RBI hold at 5.25%. Asia CPI cluster, Japan wages 3.3%, Philippines 8.2%, Thailand 4.05%, Taiwan 2.1%, Colombia 5.85%. Canada employment +15.0k, unemployment 6.9%. Eurozone GDP final Q1. Turkey CPI 32.2%. Sovereign rating reviews for Hungary, Azerbaijan, Austria.
All week: NFP Friday and Broadcom Thursday AMC bookend the data. Eurozone CPI Tuesday cements the ECB June hike. The Asian rate-decision and inflation cluster Friday. Bloomberg Tech Summit, St Petersburg Forum and OECD outlook the three soft-power markers. Seasonally-light June begins.
Beyond next week
Jun 8: OPEC+ JMMC, production-cut path under review.
Jun 10-11: ECB rate decision, 25bp hike likely confirmed; the September follow-up the deeper market question.
Jun 16-17: Warsh's first FOMC, the SEP re-thought. The call on whether the first move under the new chair is, improbably, up.
Jun 17-18: BOJ decision, swaps around 75-80% pricing a 25bp hike to 1.00%.
Jun 18: SNB decision, expected hold at 0% with deflation-risks-receding signal.
Jun 21: Colombia presidential runoff if Sunday's first round is inconclusive.
Late Jun: SpaceX expected on Nasdaq, $2T IPO; OpenAI confidential filing for September pricing reportedly imminent.
Jul-Aug: UN funding cliff, Guterres flags mid-August financial collapse on current trajectory.
Regimes
US growth signal stays clean, the bond market does the Fed’s tightening for it. Bloomberg Economics estimates the long end rise this quarter is worth about 75 of equivalent tightening. NFP 95k still consistent with the early in the cycle thesis. Carry into 3 to 6 month USD upside structures through NFP into the BOJ FOMC window. held, week 3
G7 long end stress softens at the edge, the belly catch up is the next phase. US 30 year closed Friday at 4.97%, off the early May spike but still elevated. UK and JGB curves at multi decade highs in parallel. The 2 to 5 year belly is where the term premium catch up sits if the Fed pulls its punches. Pay US short end on any Iran rally relief. evolved, week 4
European structural rebalance, multi trillion overhang the multi quarter frame. European households hold 10 trillion US equities and 2 trillion US Treasuries. FX hedged carry on US assets has turned negative for euro investors. Q1 European earnings best in three years. ECB June hike confirmed by Tuesday CPI cluster. EURUSD closed Friday at 1.1654. Long EURJPY entered late Friday is the cross rate expression. Small long EUR sleeve through the June meeting. evolved, week 2
China pay rates stopped, CNH long held on the energy axis flow. The Chinese 5 year swap broke lower through multi year support last week, against the view. Stopped on the pay rates leg. Long CNH stays through the Russia China pipeline news flow. Watch for re entry above the prior support if structural inflation breaks through. stopped, repositioned
AI capex regime moves into the political risk discount column. Hyperscaler CDS volumes through 13 billion net notional. Hawley populist messaging up. 55% of voters say no unlimited AI profits and require redistribution for AI displaced jobs. Broadcom Thursday the next earnings tell. The credit market is hedging. The equity market still pays. No position, the canary. evolved, week 6
Shifts (if → then)
If NFP prints below 80k Friday → curve bull steepens, dollar fades, the Fed cannot cut narrative bends. Trim 3 to 6 month USD upside, hold AUDNZD short, add to long EURJPY. new
If NFP prints above 130k Friday → curve flattens at the long end, dollar bid extends. The Warsh might hike narrative comes back into the front end. Add USD upside, pay US short end. new
If Iran deal headline lands hard → temporary USD relief, long end yields ease for a session. Use the dip to add the AUDNZD short and the long EURJPY structure. new
If Broadcom misses Thursday after the close → AI capex tape rolls over, Nvidia leads the equity correction, the hyperscaler CDS canary stops being a canary. new
If eurozone CPI prints 3.4% or higher Tuesday → ECB June hike confirmed and September follow up gets priced. Bunds sell off, add to long EUR sleeve and pay European rates. new
If USDJPY tops 160 sustainably → BOJ June hike priced certain, yen carry unwind begins, long EURJPY benefits from the EUR leg first. Spot 159.26 Friday close. carried, evolved
If MOVE keeps rising while FX vol stays pinned at the lows → the gap closes the wrong way, FX vol catches up, the VAR shock arrives. carried
Tails
AUDNZD seasonal headwind plus the rates switch of guards → a multi month downside cycle in the cross, the air pocket below the 1.2139 cloud the immediate target. Spot 1.1995 Friday. The book runs short with defined risk. new, week 1
AI political backlash accelerates into the midterm calendar → Gen Z sabotage, populist legislation, anti AI 2028 candidates differentiate. The AI capex regime takes a political risk discount. week 3, evolved
Hormuz physical reopening lags the headline by months → Adnoc says four months minimum to 80% of pre conflict flows, full flows not before Q1 2027. The deal trade and the supply trade do not converge for two quarters. week 8
The Russia China energy axis hardens, 50bcm pipeline advances → the Eurasian axis regime accelerates, RMB internationalisation gets a structural lift, gold gets the multipolar tailwind. new, week 1
Trump Bessent fight the curve, Warsh holds or bends → markets reprice institutional risk premium. Gold rallies, dollar weakens structurally. week 6, evolved
Yen carry unwind contagion → Japanese capital stays home. The bid that funded G7 deficits for two decades disappears. week 3
UN funding cliff in August → the 1945 architecture fragments visibly. The law of the jungle frame the Xi Putin statement called out becomes the operational reality. new, week 1
Manic Monday
ISM Manufacturing, construction spending and Korea exports the data line up. Sunday’s China official PMIs already in the rearview, manufacturing right at the line and non manufacturing the upside surprise.
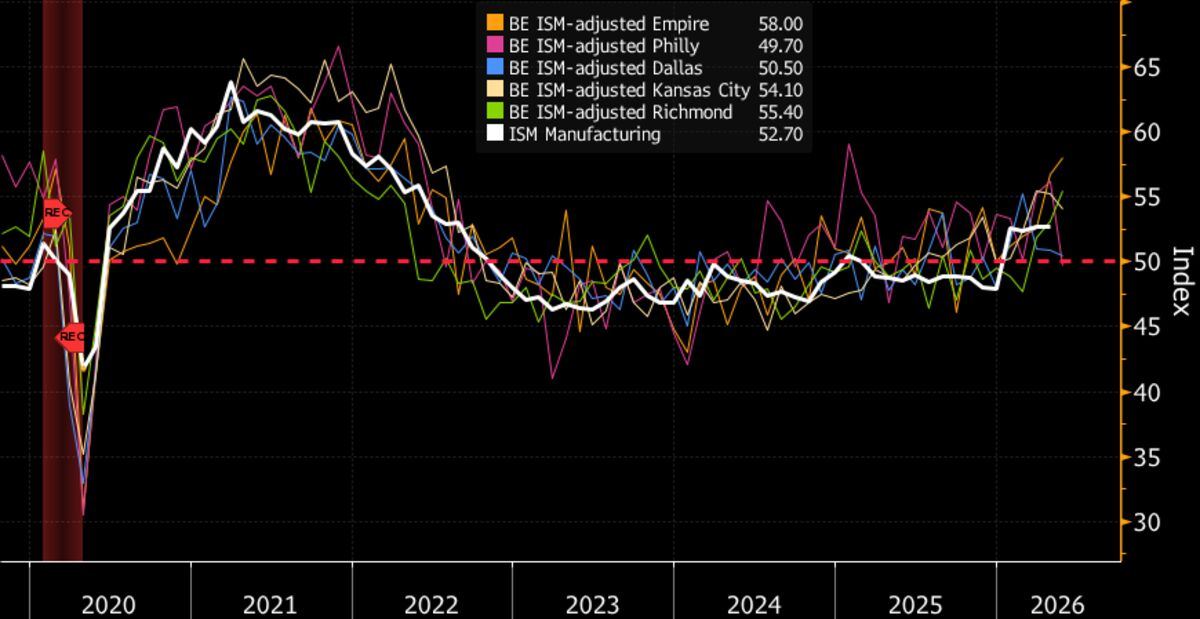
ISM Manufacturing likely improved to 53.0 in May from 52.7. Regional Fed surveys point to accelerating new orders. Bloomberg Economics is below the 53.1 consensus on softer shipments and mixed employment indicators. Price pressures still present but less pervasive in May. The first US data point of the new week sets the tone. Source: Bloomberg Economics.
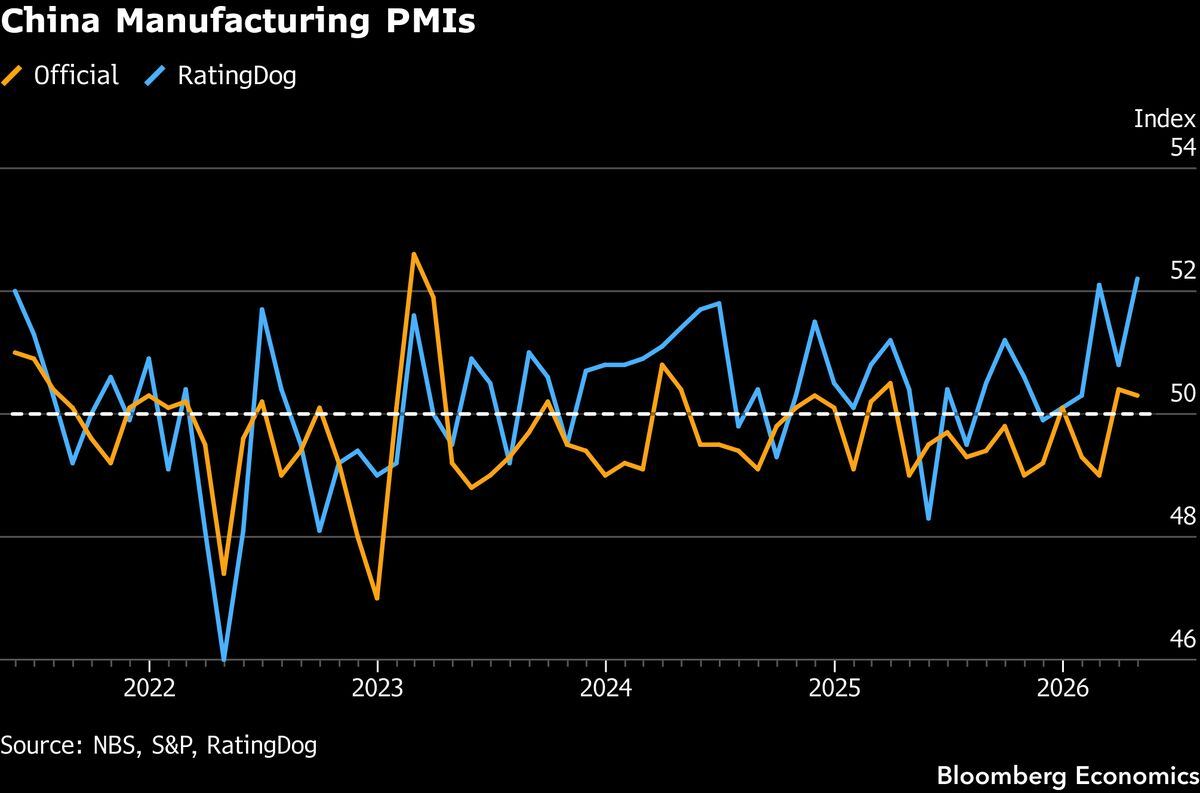
China RatingDog manufacturing PMI may slip to 51.3 from 52.2. A week long holiday and softer external demand pulled the exporter tilted private gauge lower. Sunday's official PMIs already in the rearview: manufacturing held the threshold at 50.0, non manufacturing beat at 50.1 from 49.4, composite picked up to 50.5. Source: Bloomberg.
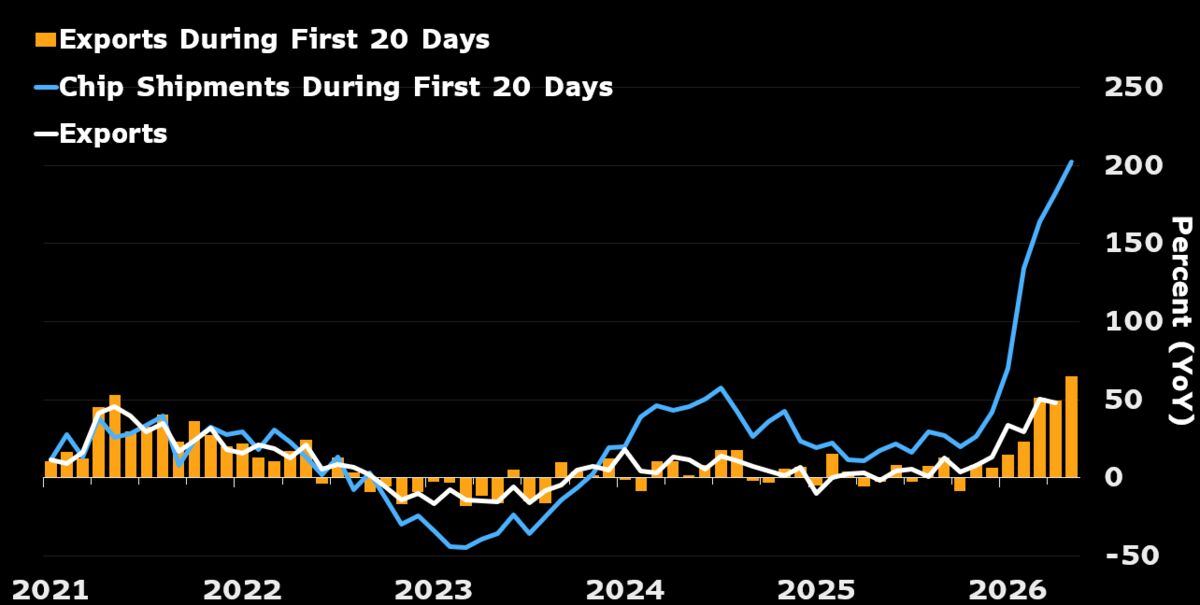
Korea exports likely surged 55.5% year on year in May, propelled by AI semiconductor demand. Chip shipments up 202.1% in the first 20 days. Petroleum products 46.3%, computer peripherals 305.5%. Trade surplus widening to 26.4 billion from 23.8 billion. SK Hynix joining the trillion dollar club is the equity expression of what the trade data already shows. Source: Bloomberg.
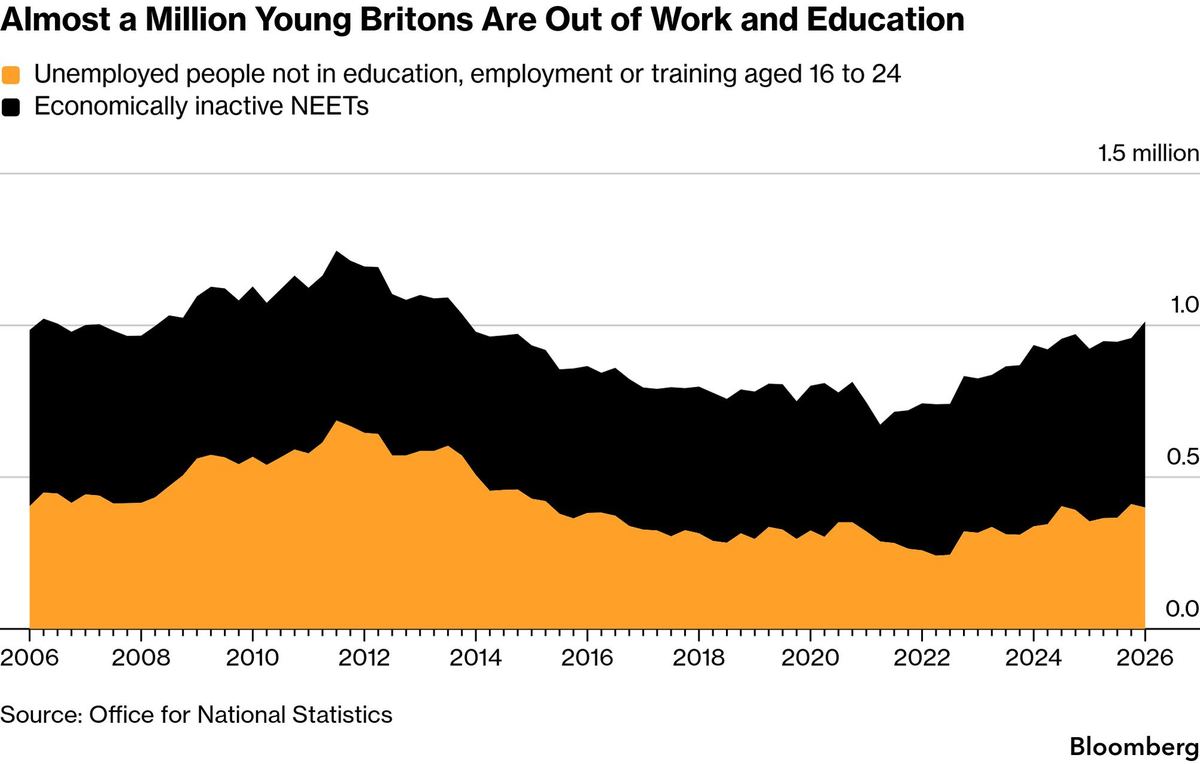
UK youth unemployment surge risks a lost generation. A government commissioned review found surging employment costs, worsening mental health, and AI reducing the number of entry level roles as the drivers. The European mirror of what Hong Kong and Singapore recruiters are calling out openly this week. Read the Bloomberg piece. Source: Bloomberg.
Turnaround Tuesday
Eurozone CPI day, the last inflation print before the ECB convenes. JOLTS in the US afternoon. Korea and Indonesia CPI early Asia.
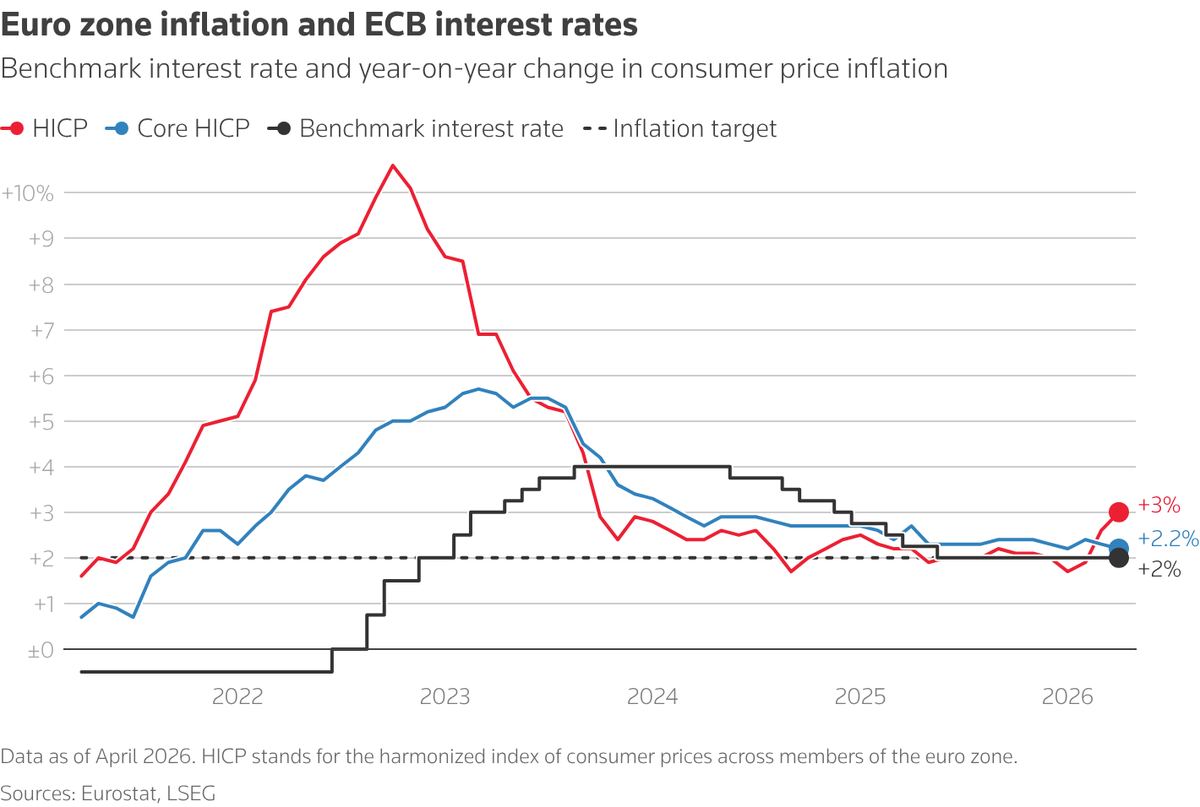
Eurozone inflation back above 3%, the ECB set to hike June 10-11. Bloomberg Economics sees May HICP at 3.2% from 3.0%, core 2.3% from 2.2%. Higher utility and travel service costs are the cleanest read on second round effects from the energy shock. Money markets price at least one more hike this year, possibly two. Source: Reuters.
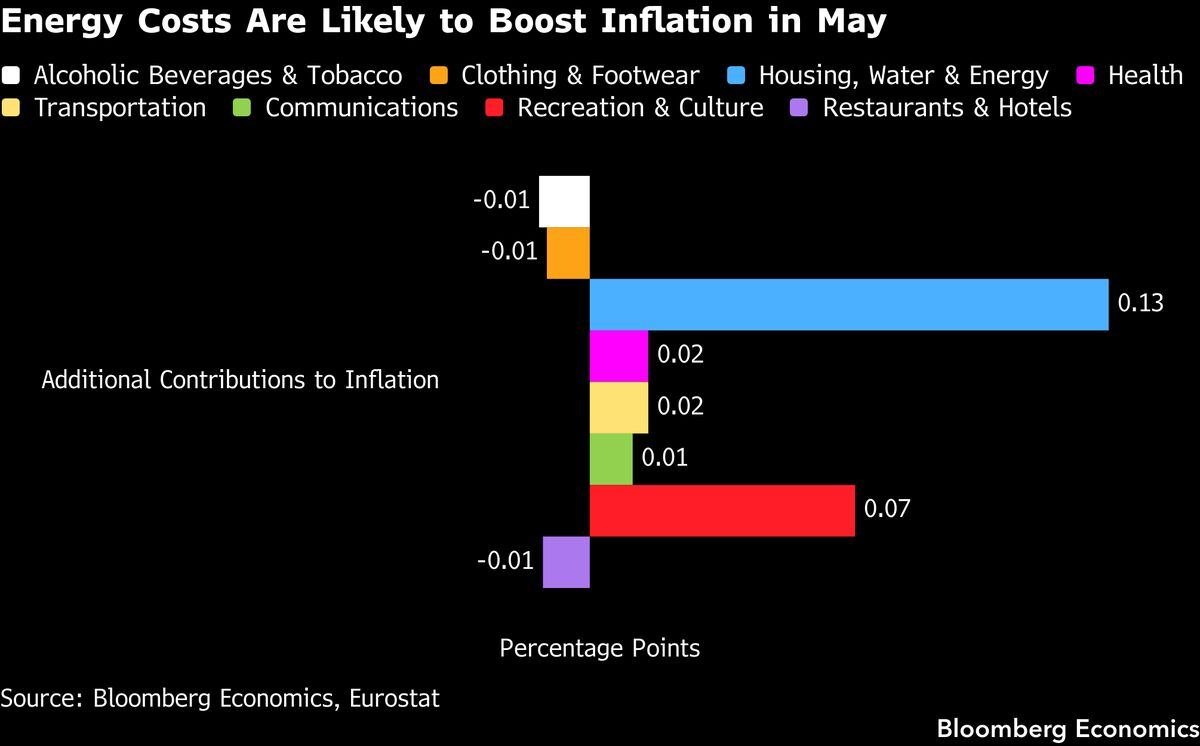
The May CPI cluster across the four largest eurozone economies. Germany 2.8, France 2.9, Italy 3.2, Spain 3.5 — the national prints already published — cement the June ECB hike. Household energy bills add 0.1ppt to headline. Travel services add another 0.1ppt to both headline and core. A print above 3.2 reprices the post June path. Source: Bloomberg Economics.
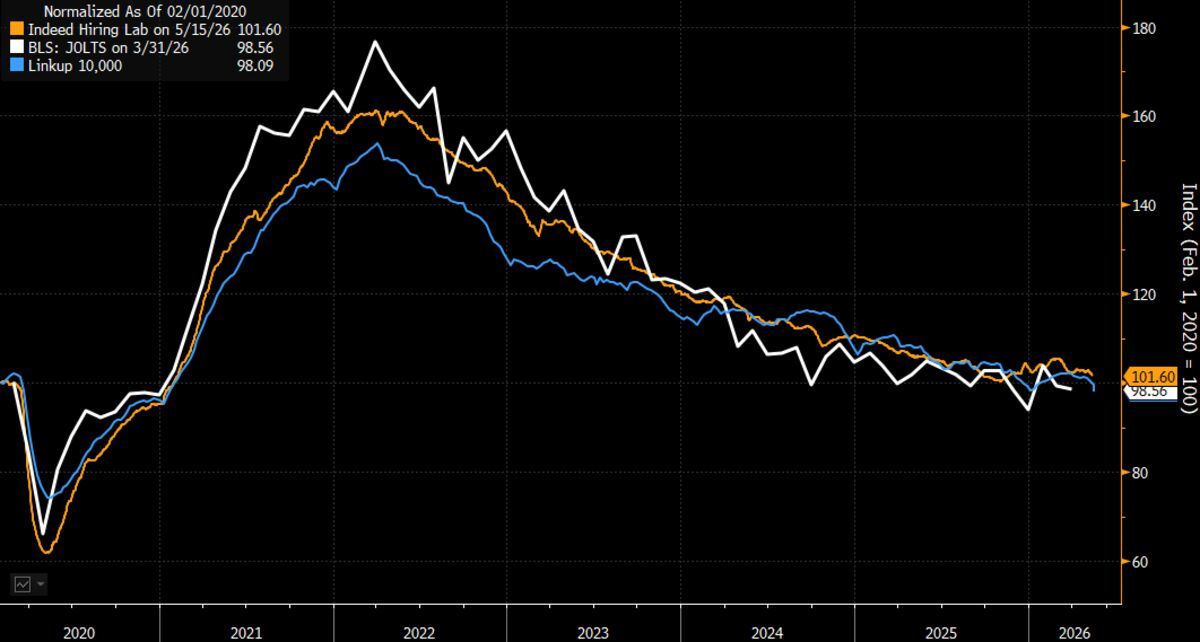
JOLTS likely rose 85k to 6.95 million in April. Indeed Hiring Lab and LinkUp alternative data point to a third consecutive uptick. Declining layoffs prevented a third uptick in the discharge rate. The quits rate held at 2.0%. The rotation underneath is AI driven automation reshaping the composition of openings. Source: Indeed Hiring Lab / LinkUp / BLS.
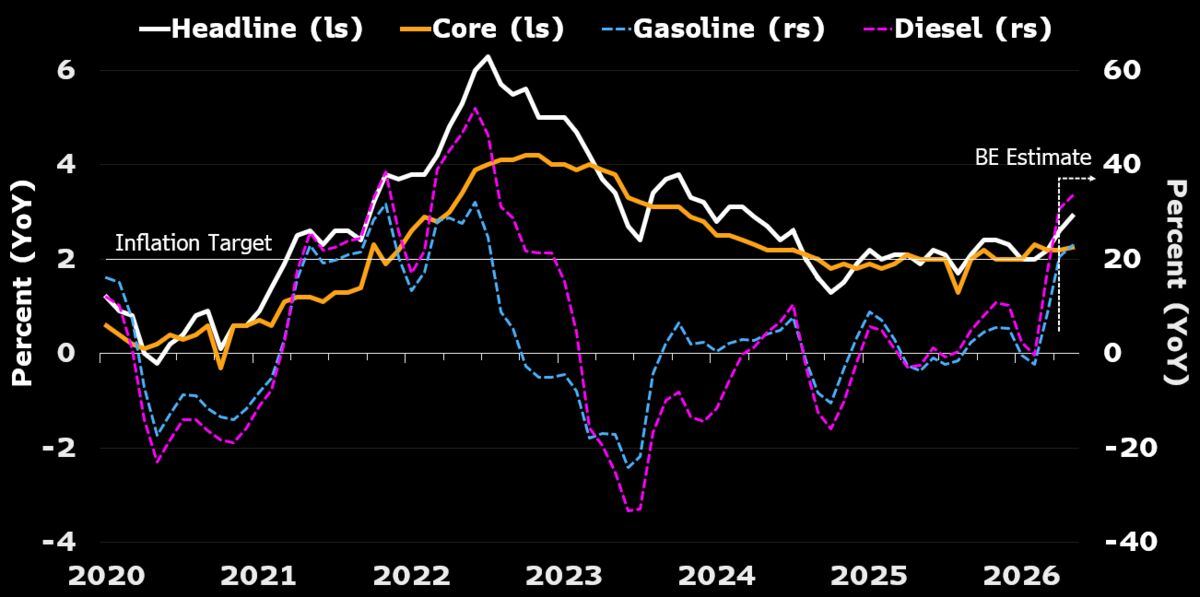
Korea CPI likely accelerated to 2.9% in May, moving further above the BOK 2% target. Core 2.3 from 2.2. The fuel price cap has softened the immediate hit. A weaker won is lifting import costs. Memory chip prices pushing electronics higher. BOK expected to start raising in 3Q, taking the base rate to 3.0% by year end. Source: Bloomberg Economics.
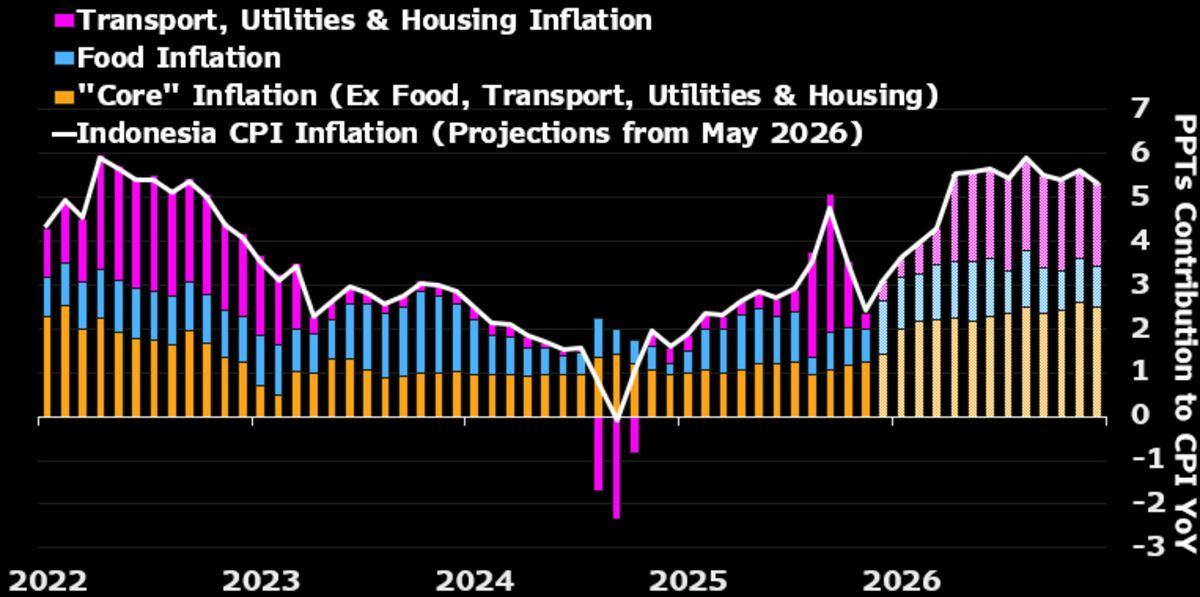
Indonesia CPI likely picked up to 3.1% in May from 2.42%, lifted by domestic demand and the oil shock. On track to breach the 1.5 to 3.5 target band in June and keep rising through year end if the oil shock persists. The rupiah has weakened against the dollar and most peer currencies, lifting import costs further. Source: Bloomberg Economics.
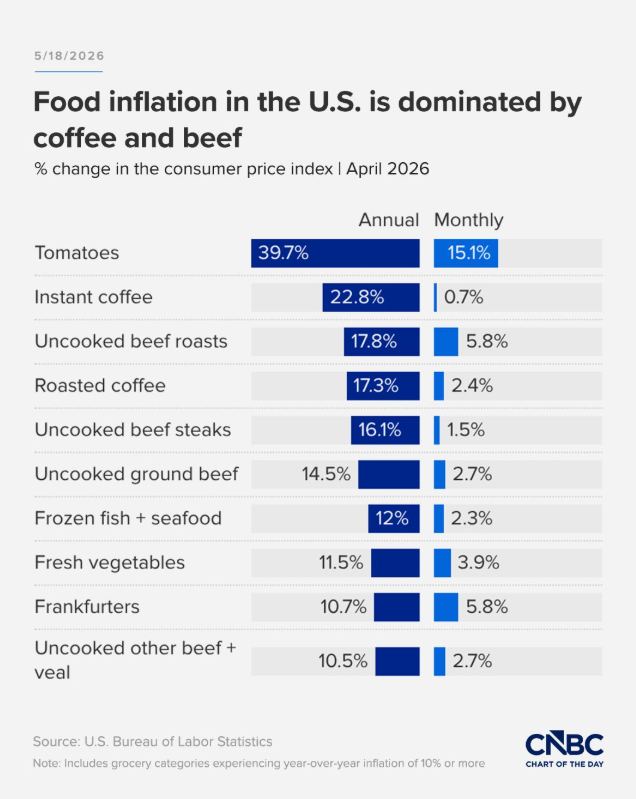
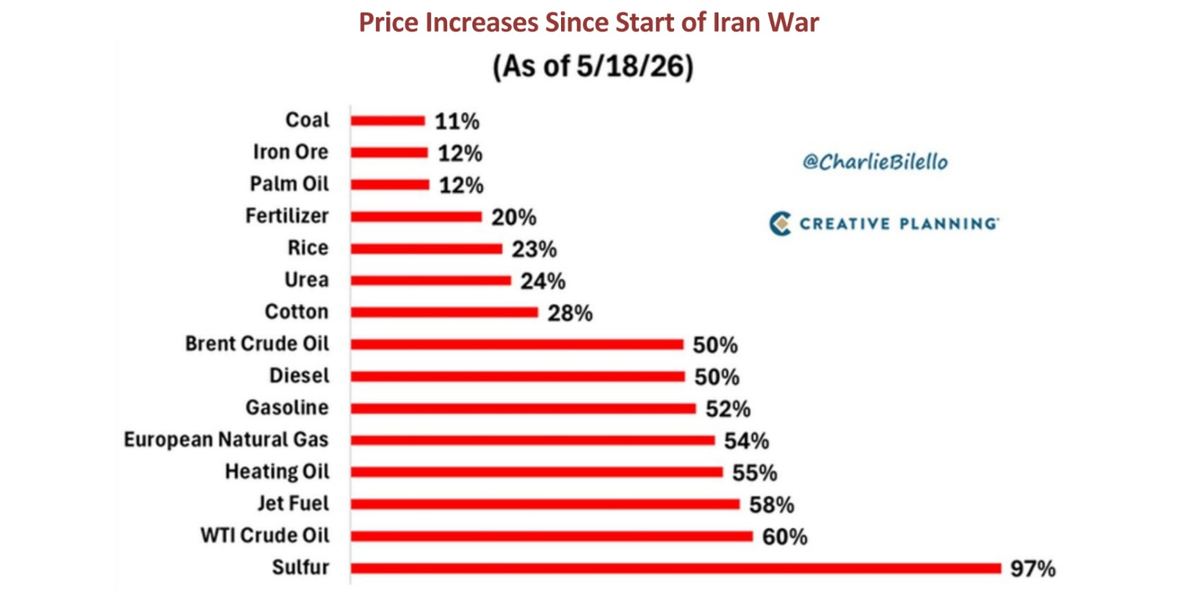
US April CPI hit its highest level in nearly three years on the Iran war passthrough. Surging gas prices pushed up the cost of many consumer goods. The diesel trucking passthrough to grocery shelves is the cleanest household budget read. The same pattern shows up across the eurozone, Korea, Indonesia and the rest of Asia all in the same week. Source: WSJ.
Watershed Wednesday
Australia Q1 GDP and the BOJ Ueda speech in Asia. ISM Services and the Beige Book in New York. Bloomberg Tech Summit opens in San Francisco. St Petersburg Forum opens with the Saudi Energy Minister attending. The busiest day on the calendar.
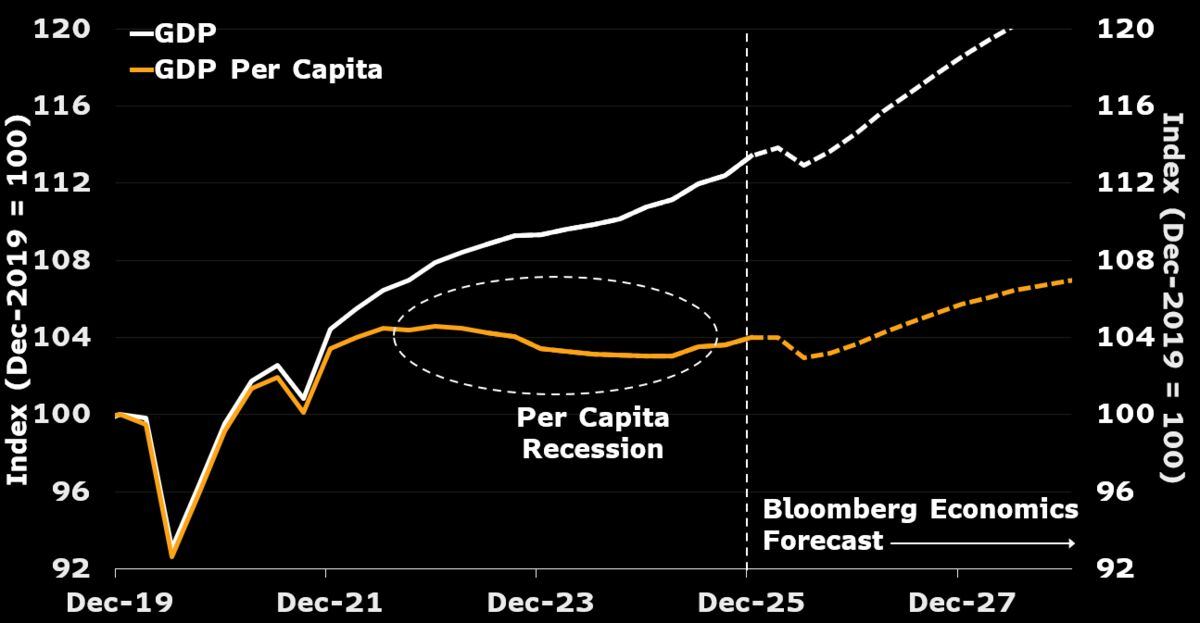
Australia GDP likely expanded 0.4% QoQ in Q1, half the 0.8% Q4 pace. Household spending supported by precautionary spending linked to the energy shock. Weaker residential construction and softer sales activity weighed. Q2 softens further as energy prices, uncertainty and the cumulative effect of the 2026 hikes weigh on household spending. Source: Bloomberg Economics.
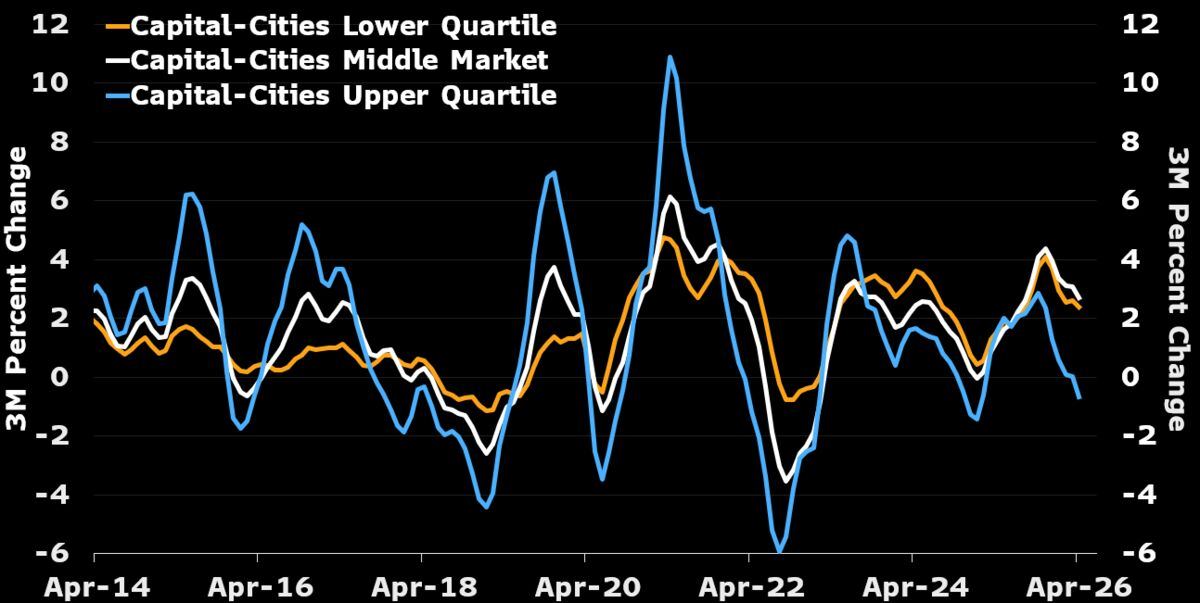
Aussie housing top end leads the first price decline since January 2025. Capital city prices likely fell 0.1% in May, led by Sydney and Melbourne. Perth, Brisbane, Adelaide still gaining at a slower pace. The cumulative RBA hike cycle has dented confidence. Proposed tax changes on housing investor concessions adding pressure at the top end. Source: Cotality / Bloomberg Economics.
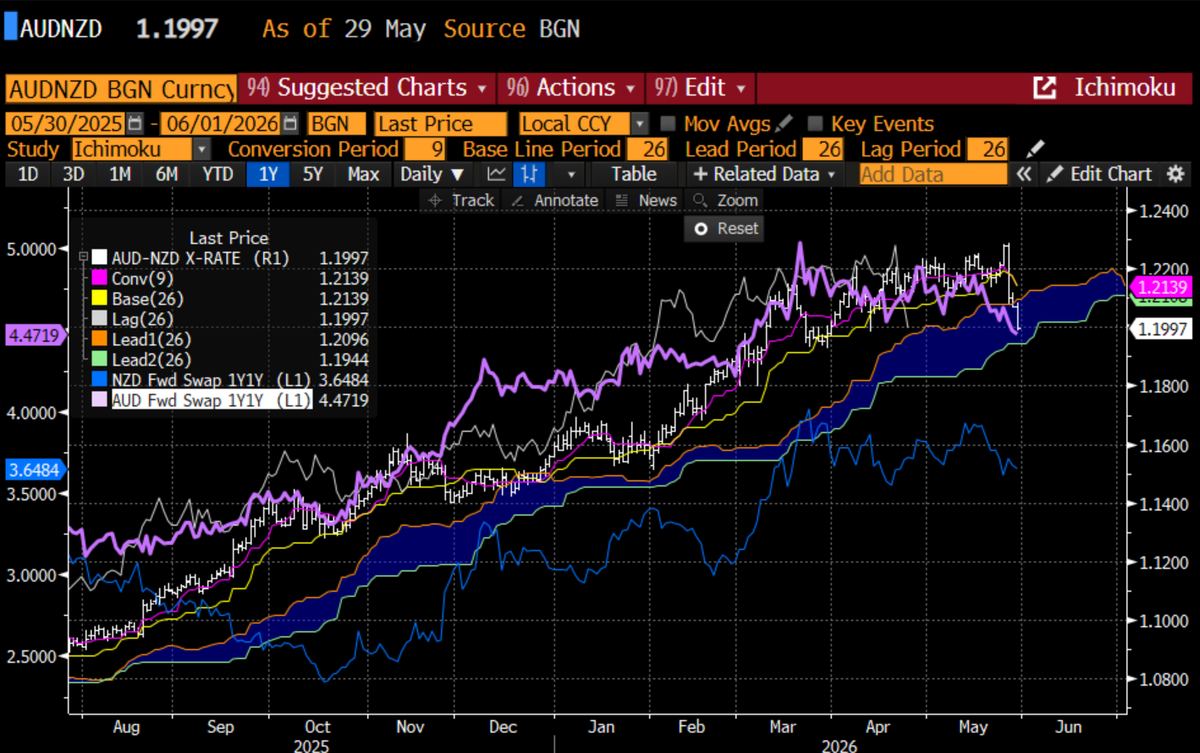
AUDNZD daily Ichimoku, the air pocket. Spot did not drift lower, it sliced vertically through the conversion line and baseline both at 1.2139 straight into the cloud. The multi month uptrend since August 2025 left no historical volume profile to slow the fall. Friday close 1.1995, already below the cloud's bottom edge at 1.1944. Source: Bloomberg / Ichimoku.
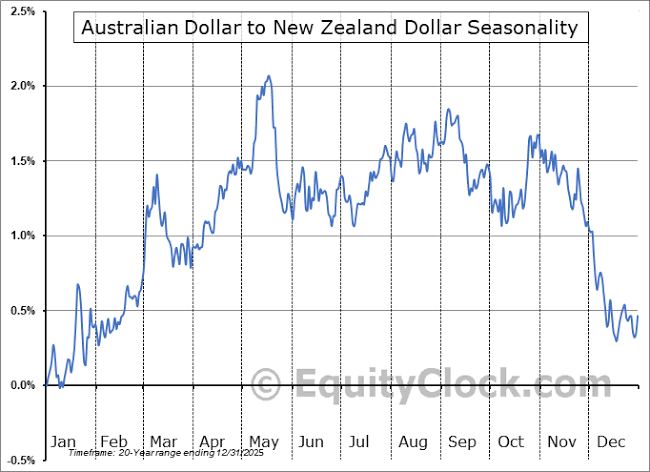
AUDNZD seasonal pattern peaks mid to late May, steep headwinds into June and Q3. The 20 year cycle data shows the cross facing structural pressure right around the rates switch of guards. Fast money macro overlays with seasonal trend filters saw the RBNZ hold plus the weak AU CPI as the cue to front run the historical downswing. Source: Bloomberg seasonal.
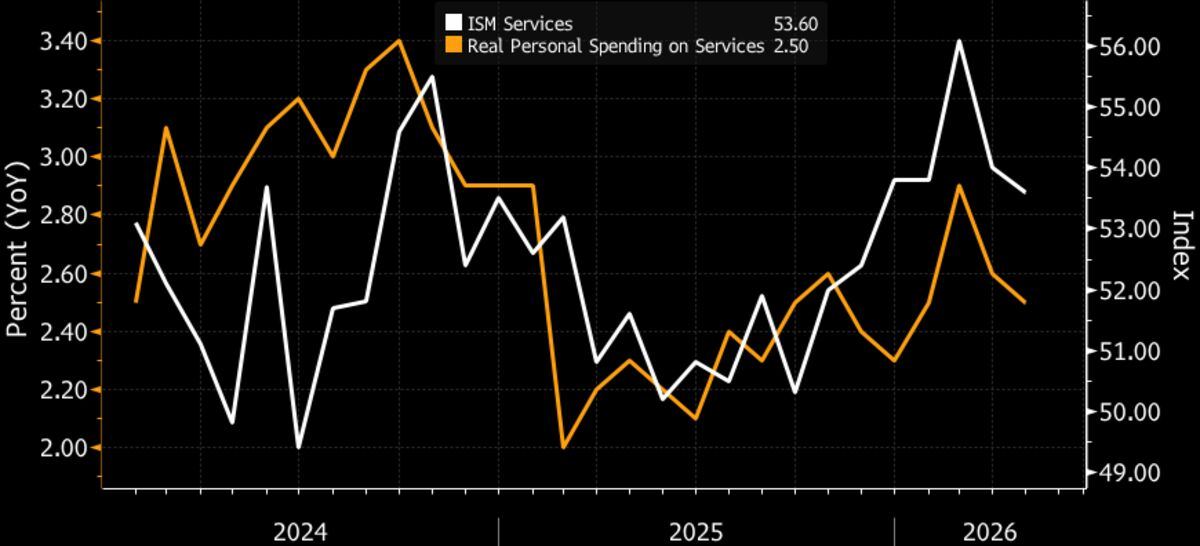
ISM Services likely ticked up to 53.7 in May from 53.6, a touch below the 53.9 consensus. Regional surveys point to a marginal improvement. The monthly uptick foreshadows improving real services spending after the April slowdown. Business activity supported by orders and sales. Employment data soft, limiting upside. Source: Bloomberg Economics.
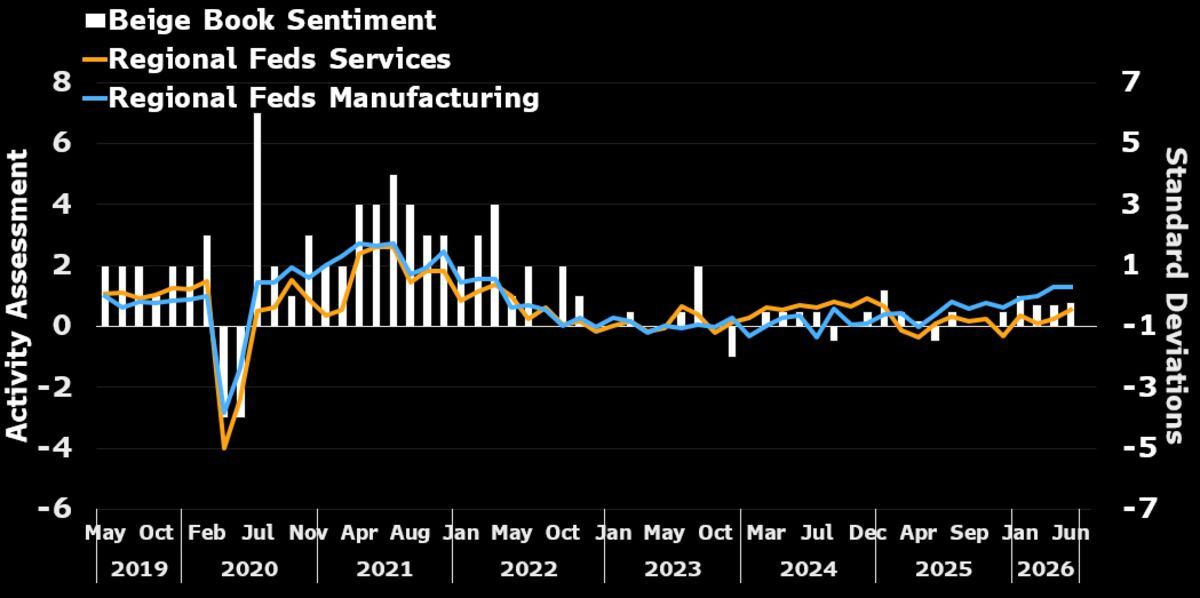
Beige Book likely characterises activity as mixed but generally positive. Tighter financial conditions increasingly visible. Firms cautious about permanent hires. Margin compression continues as input costs rise faster than selling prices. Manufacturing improving, particularly industrial and data centre projects. AI adoption enhancing productivity in some sectors. Source: Bloomberg Economics.
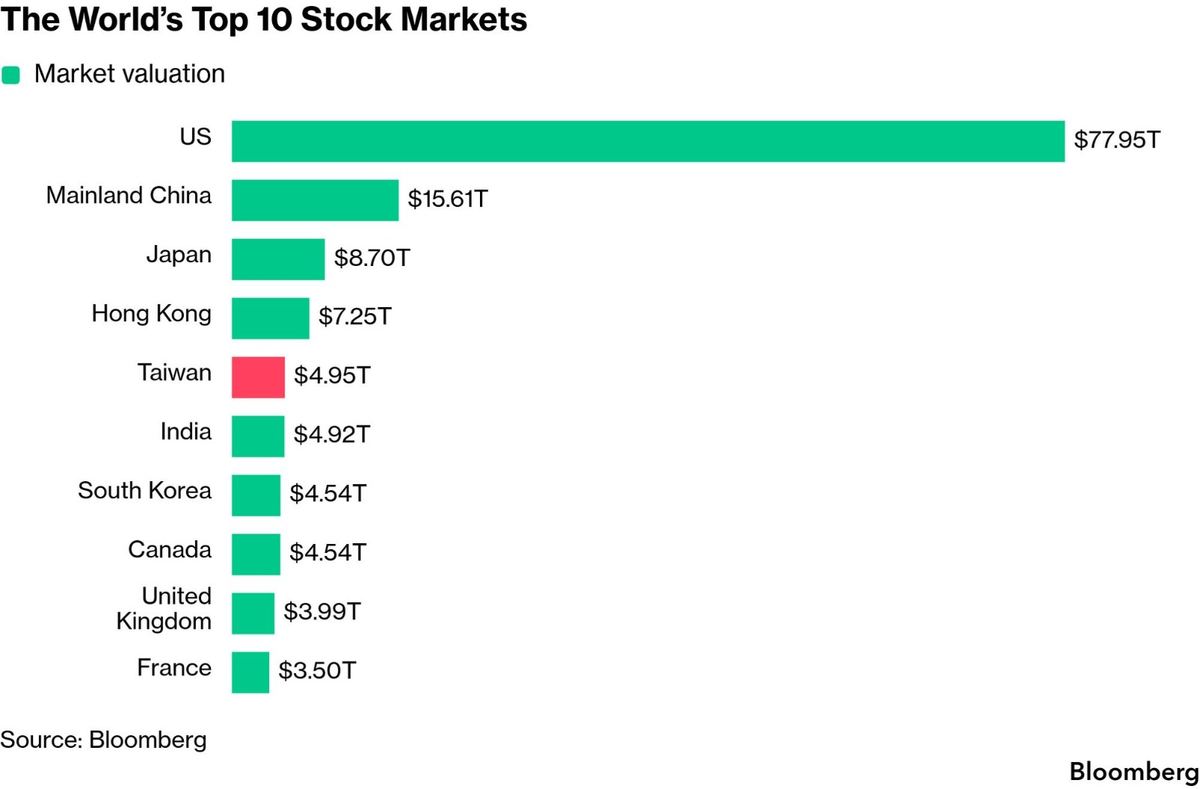
Taiwan TWSE becomes the world's fifth biggest bourse, AI the engine. The island makes the bulk of the world's most advanced chips. The bourse slipped past India, which is grappling with surging energy costs, slowing corporate earnings growth and a lack of firms tied directly to the AI buildout. The data point lands the same week as Computex and the Bloomberg Tech Summit. Source: Bloomberg.
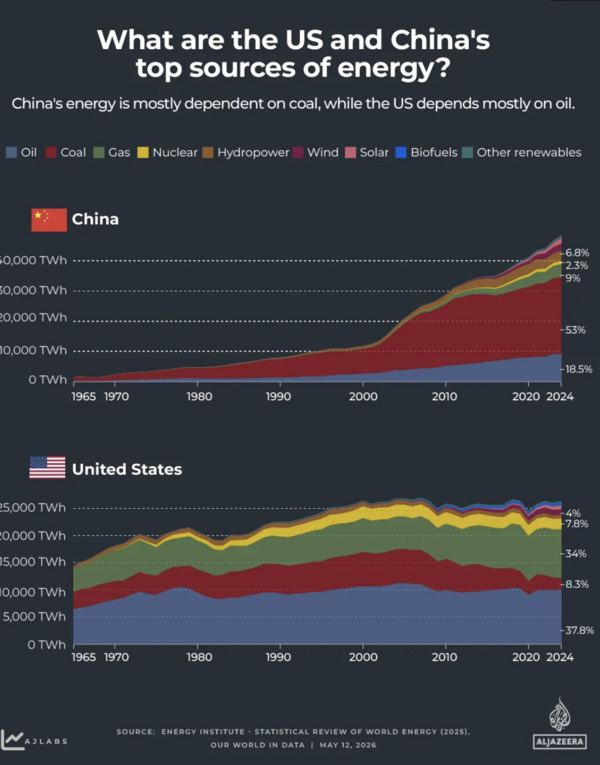
China and the US side by side on what each economy actually runs on. Coal dominant in China, oil at 18.5% of total consumption. Hydropower 6.8%, nuclear 2.3% expanding. The US more reliant on oil overall but much of it domestic, insulating the country from supply shocks. China's exposure to Hormuz — half of oil imports and 30% of gas — is why the Russia pipeline conversation matters now. Source: Al Jazeera.
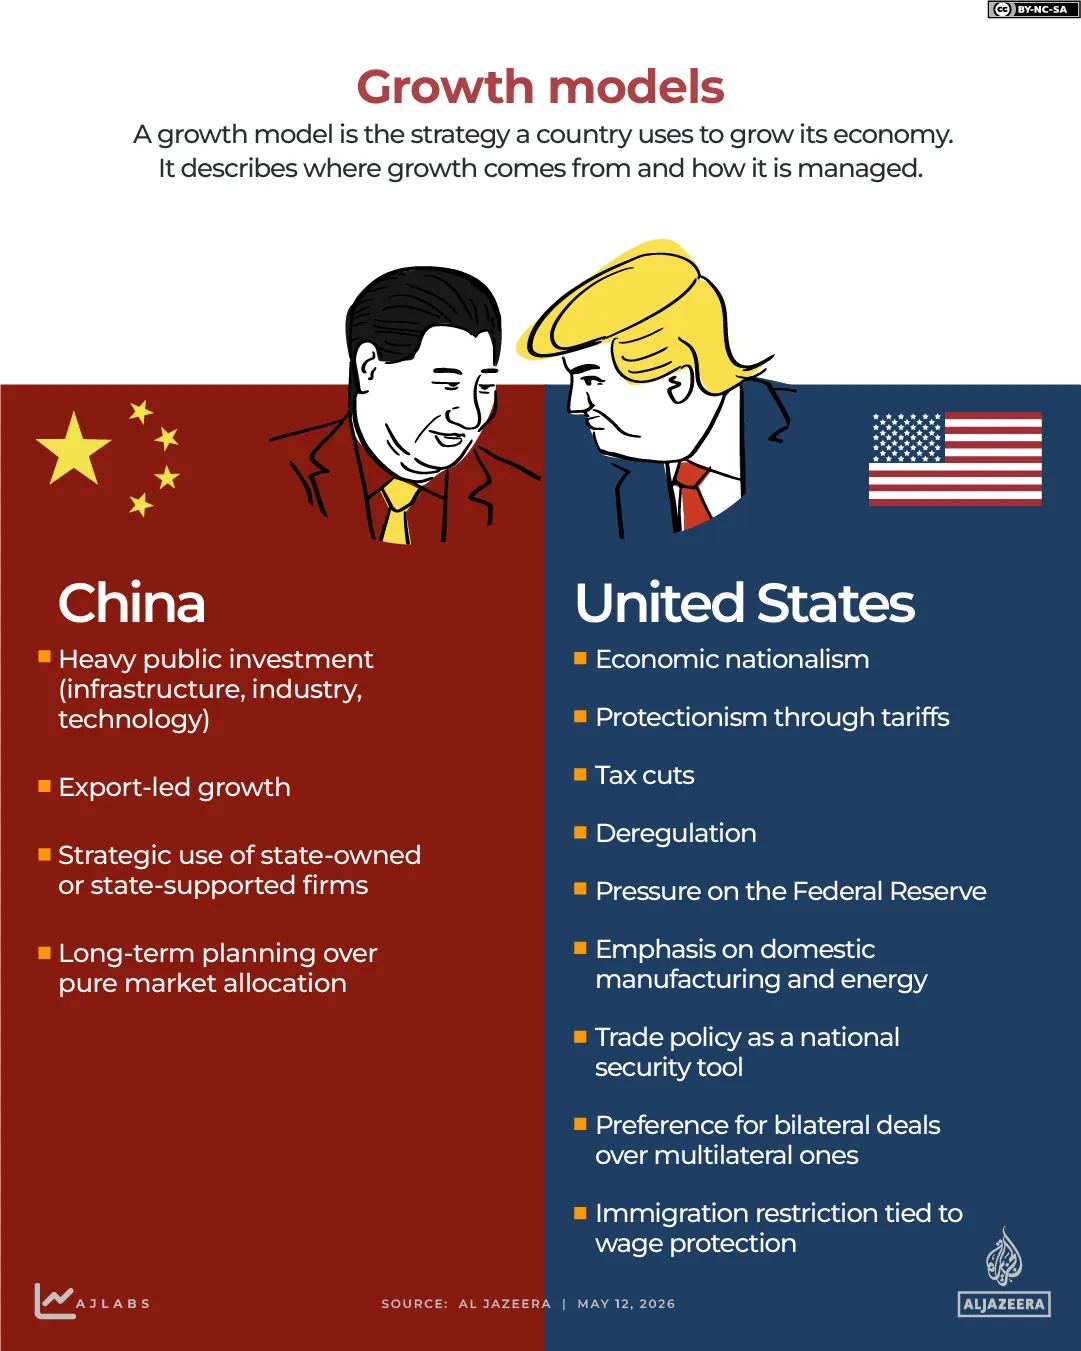
The 1,600 mile Russia China gas pipeline back on the table. The Xi Putin joint statement covered the project. 50 billion cubic metres of gas annually from Russia to China. The project would help Beijing reduce reliance on maritime chokepoints and strengthen leverage with America. Read the Al Jazeera piece. Source: Al Jazeera.
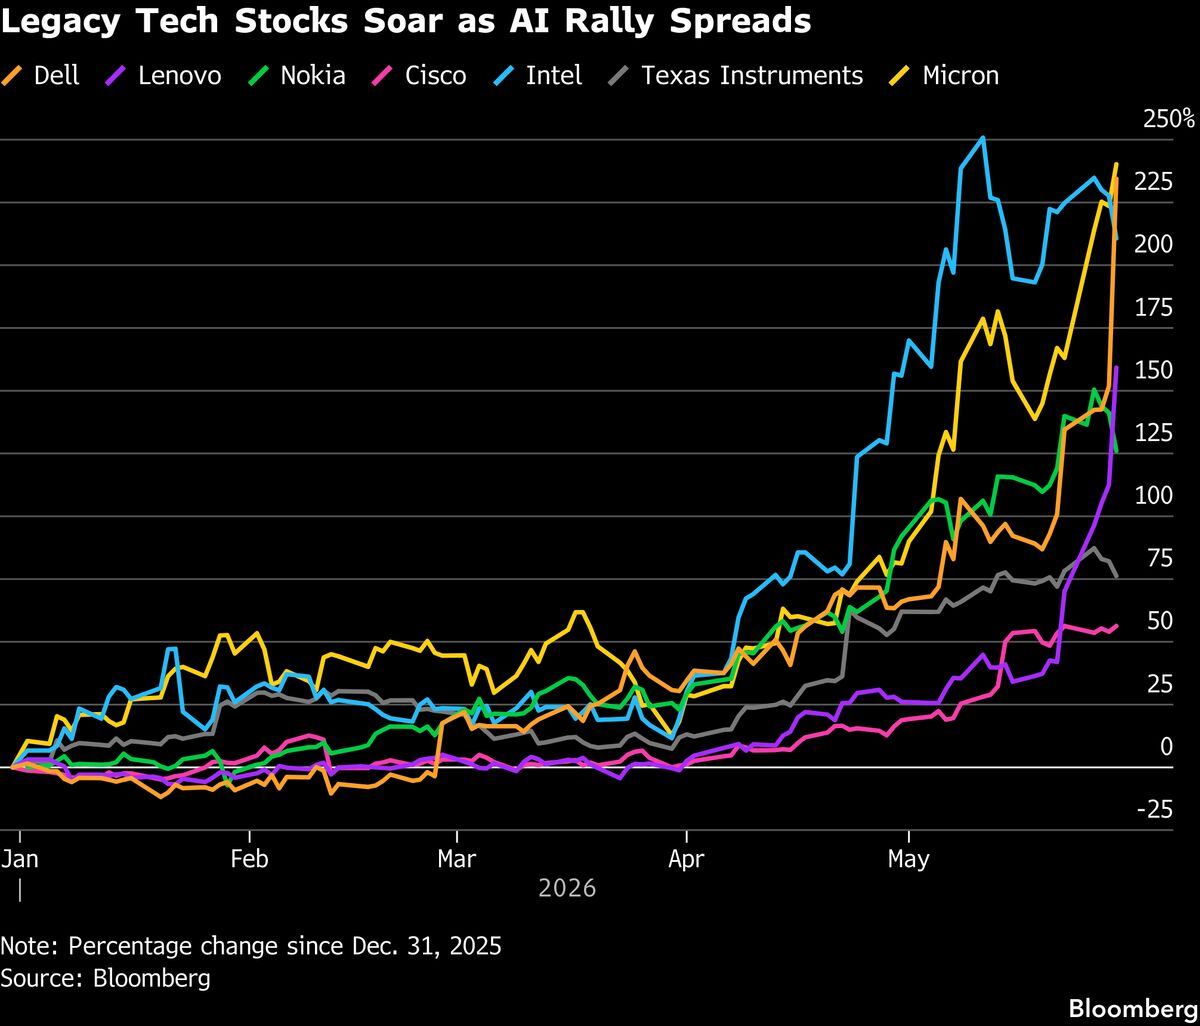
Dinosaur tech reborn, AI fuels a 1.7 trillion rally. Dell, Nokia, Lenovo, Micron, Intel, Texas Instruments, Cisco. The seven up an average 158% in 2026. Dell 33% on Friday on AI server demand, biggest one day gain ever. Lenovo 105% in May. Cisco finally topped its March 2000 peak. Micron 903% in twelve months. The under supply in boring hardware is the deeper story. Source: Bloomberg.
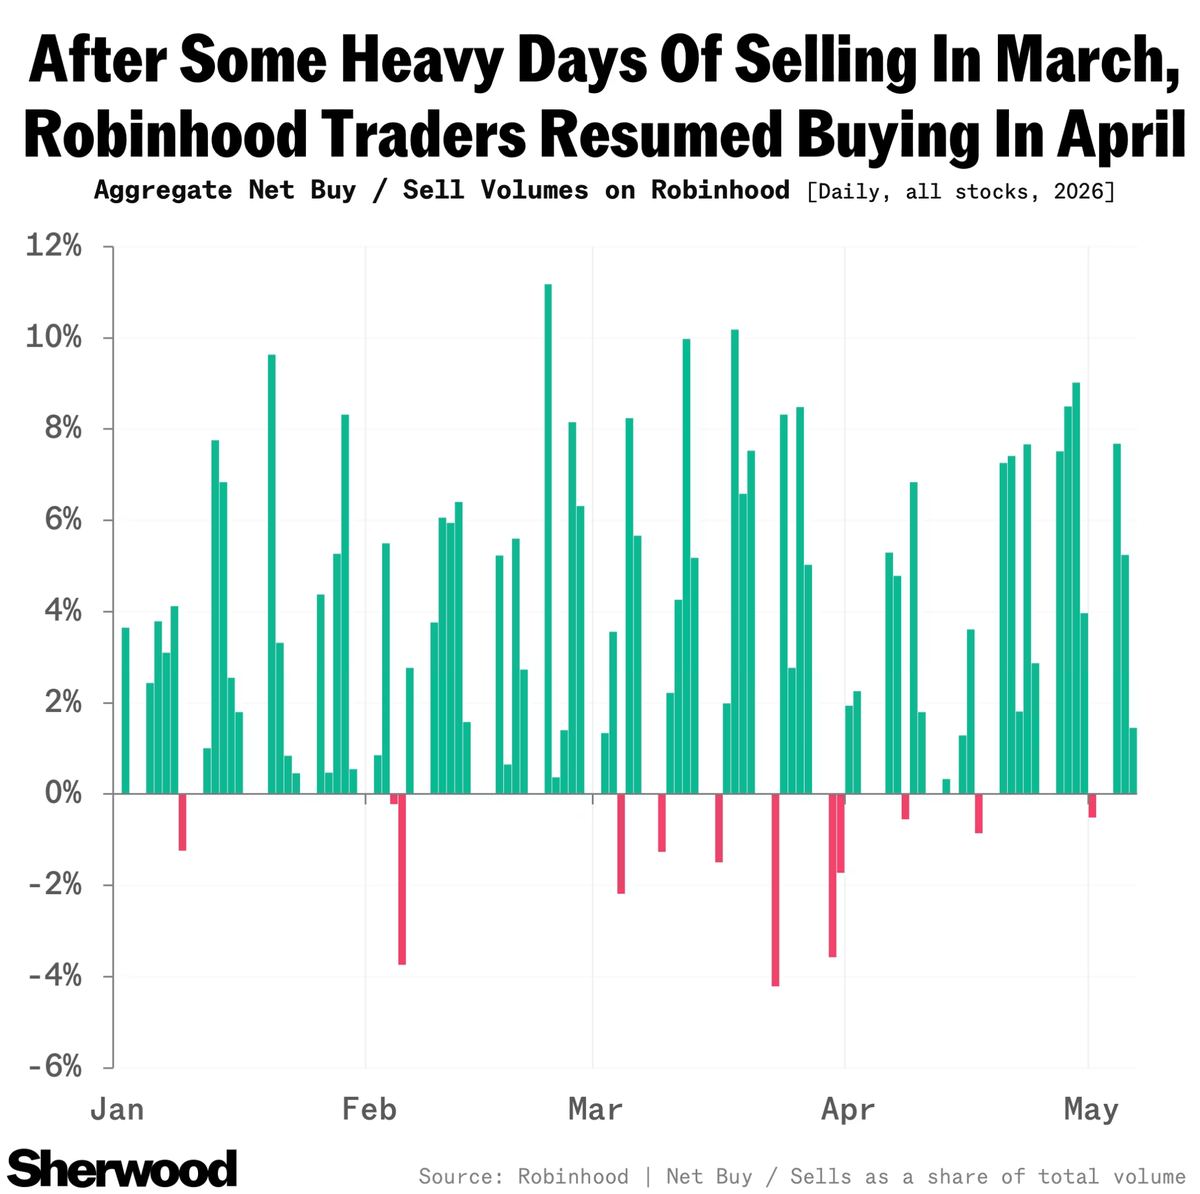
Robinhood most traded stocks, retail bought the dip. Sherwood News on which tickers Robinhood traders rotated into through the sell off and the rebound. The crowd wrong in 2022 has been mostly right in 2025 and 2026. Dinosaur tech rebirth tickers and Hormuz energy names sprinkled across the volume. Read the Sherwood piece. Source: Sherwood News.
TP Thursday
Broadcom after the New York close, the marquee AI tape print. Sweden and Switzerland CPI ahead of the SNB. Lagarde Aix en Provence as the ECB goes quiet. Underneath, Paramount Skydance is reportedly raising 50 billion in debt to finance the 110 billion Warner Bros acquisition, the largest single LBO debt raise on record. Anthropic added 36 billion in fresh credit lines, IREN closed 3.6 billion, and BDC redemption notices are running at multi quarter highs with gating expected to continue at least two more quarters. The credit cycle is doing what the equity tape is not yet pricing. Take profit before Friday.
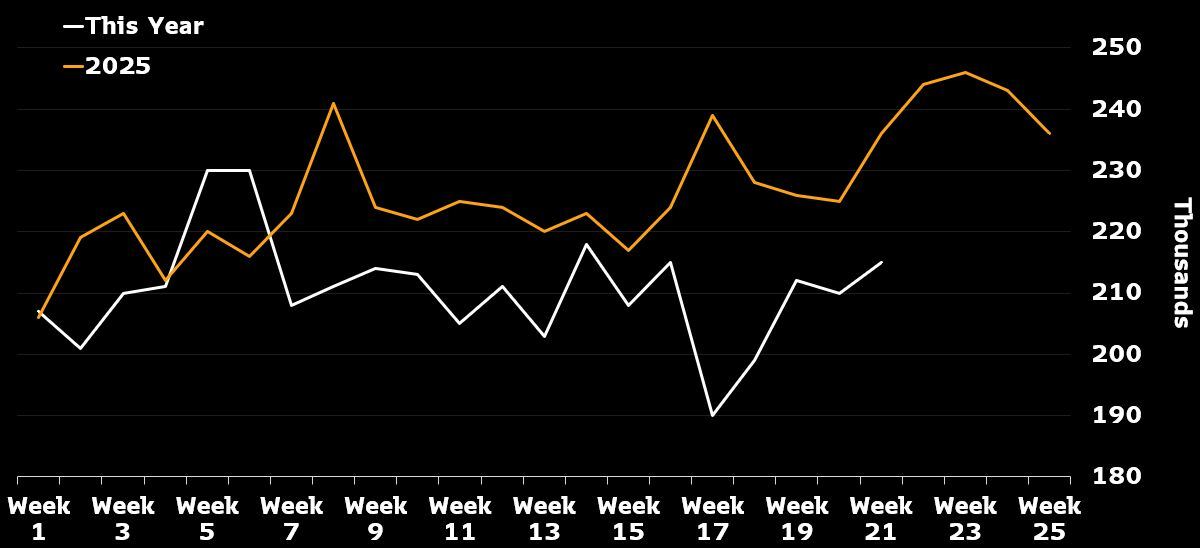
Initial jobless claims continue to track below year ago levels for a sixteenth consecutive week. The week ended May 30 expected at 218k, modestly above 215k prior. AI driven automation and geopolitical uncertainty have not meaningfully impacted the weekly print. The composition rotation underneath does not show up in the headline level yet. Source: Department of Labor.
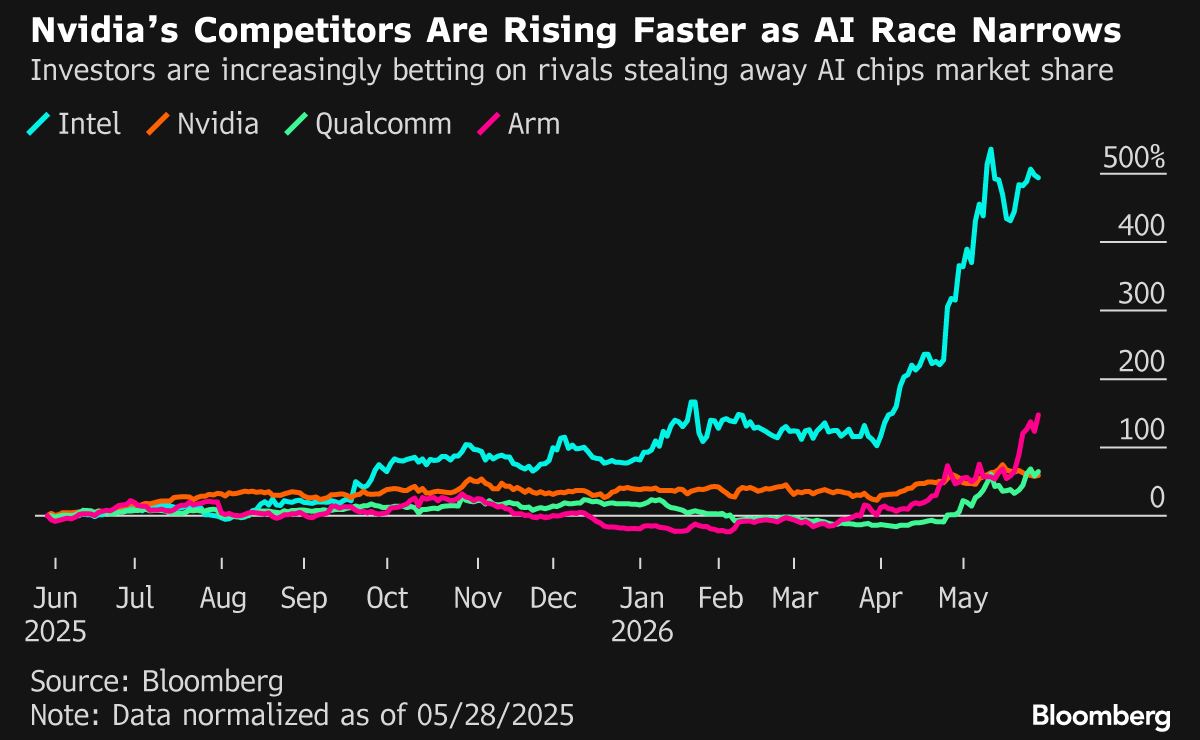
Computex sets the tone in Taiwan through June 5. The focus on Nvidia's challengers and AI hardware bottlenecks. The expo lands the same week as the Bloomberg Tech Summit and Broadcom earnings. Chip supply in two pieces: Nvidia uncontested at the high end, supply bottlenecks across the rest of the stack driving the dinosaur tech rally. Source: Bloomberg.
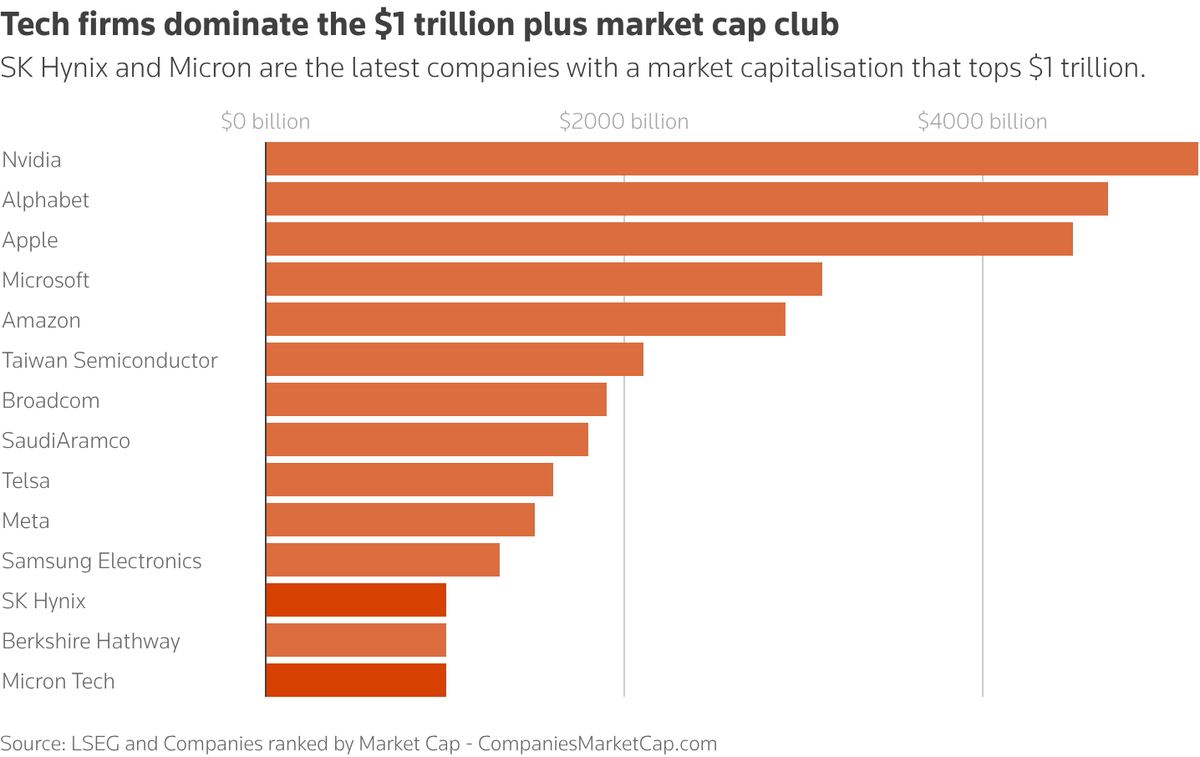
Trillion dollar club has grown again, Hynix and Micron joining. Nvidia, the leader, now over 5 trillion. Dominated by companies at the centre of the AI boom. The additions underline the staying power of the AI rally even as the energy shock drags on. Broadcom Thursday is the next earnings tell. Source: Reuters.
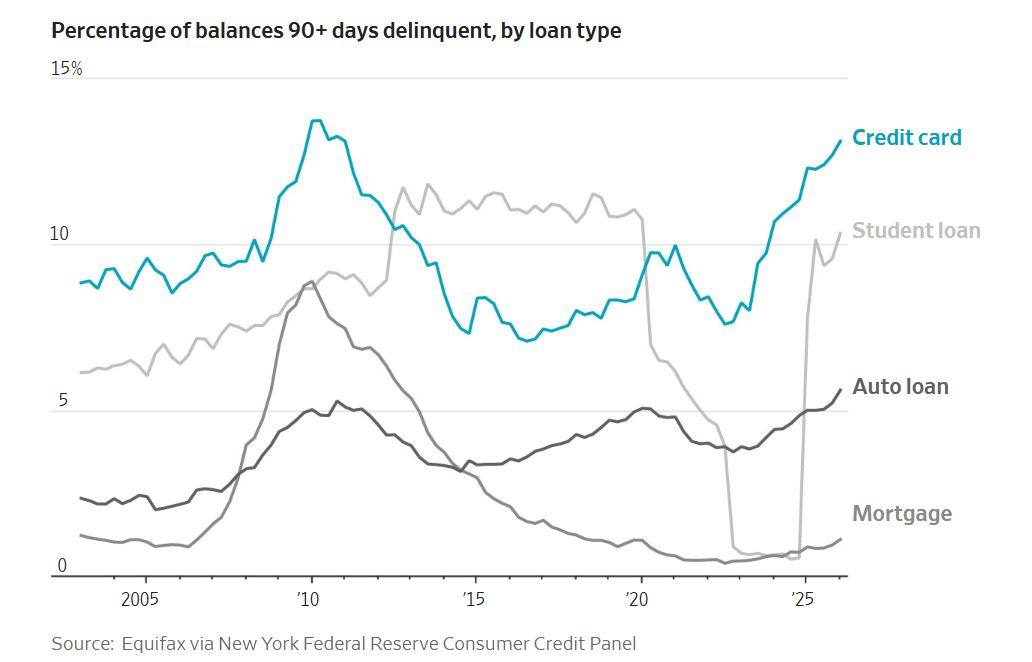
Americans falling behind on the 1.25 trillion credit card bill. Balances at least 90 days delinquent rose to 13.12% in Q1, the highest in 15 years. Total balance 1.25 trillion, the highest first quarter since the NY Fed began the measurement in 1999. Average rates 21% in February versus 14.6% three years prior. Republicans face mounting voter anxiety ahead of the November midterms. Read the WSJ piece. Source: WSJ.
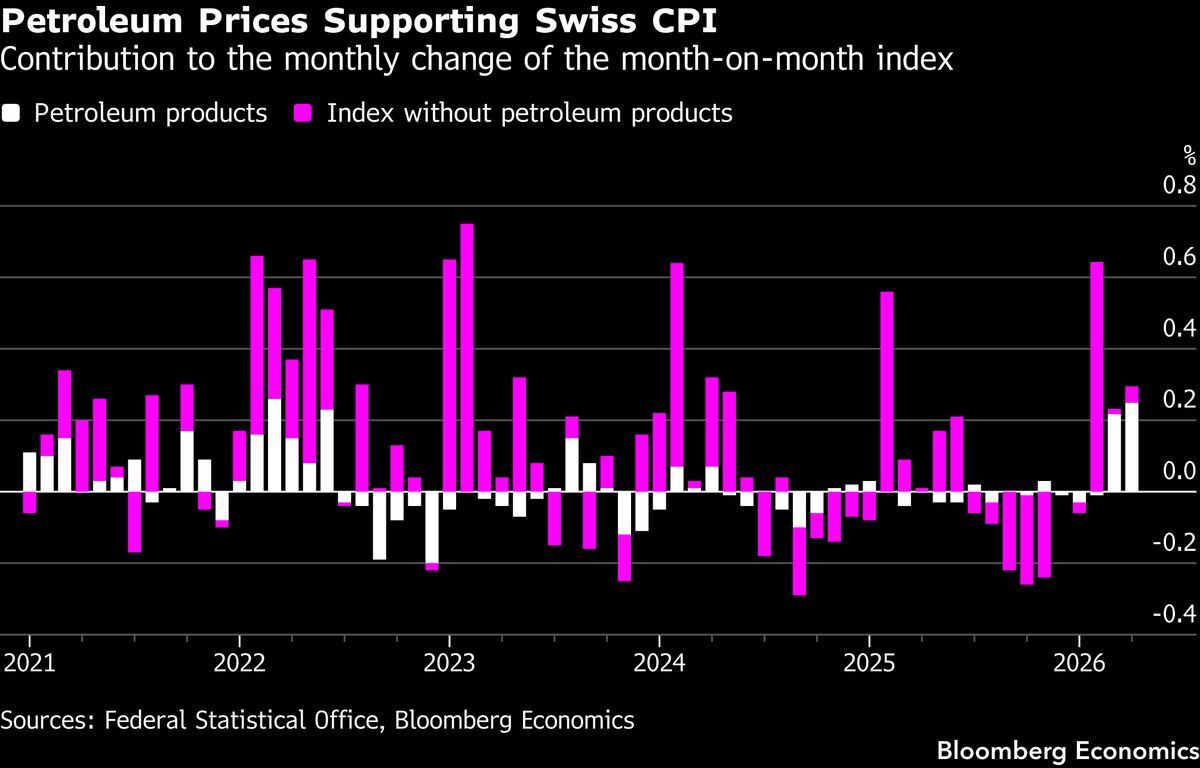
Switzerland CPI likely held at 0.6% in May. Passthrough from higher oil prices slowed and was partly offset by slightly negative contributions from rents and food. The May read is the last inflation print before the SNB June 18 meeting. Central bank likely holds at 0% and signals deflation risks are receding. Source: Bloomberg Economics.
Friday Fade
NFP Friday. India GDP and RBI hold first in Asia. Asia CPI cluster across the morning. Eurozone GDP final. Powder dry for the gate.
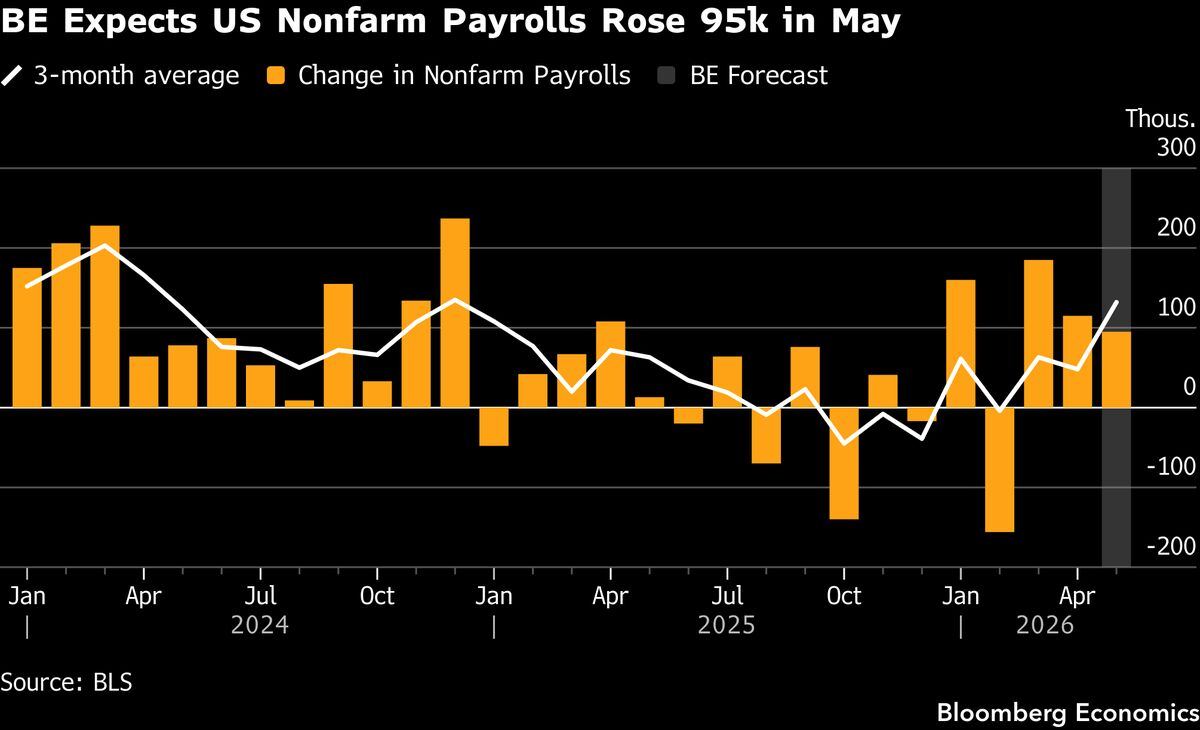
US Nonfarm Payrolls Friday, 95k expected from 115k. Bloomberg Economics calls 95k, lifting the three month average to 132k. The hot March and April reports reflected underlying momentum rather than a rebound. Private payrolls point to a pickup in leisure and hospitality. Unemployment likely held at 4.3%. The first marquee data print under Warsh. Source: Bloomberg Economics.
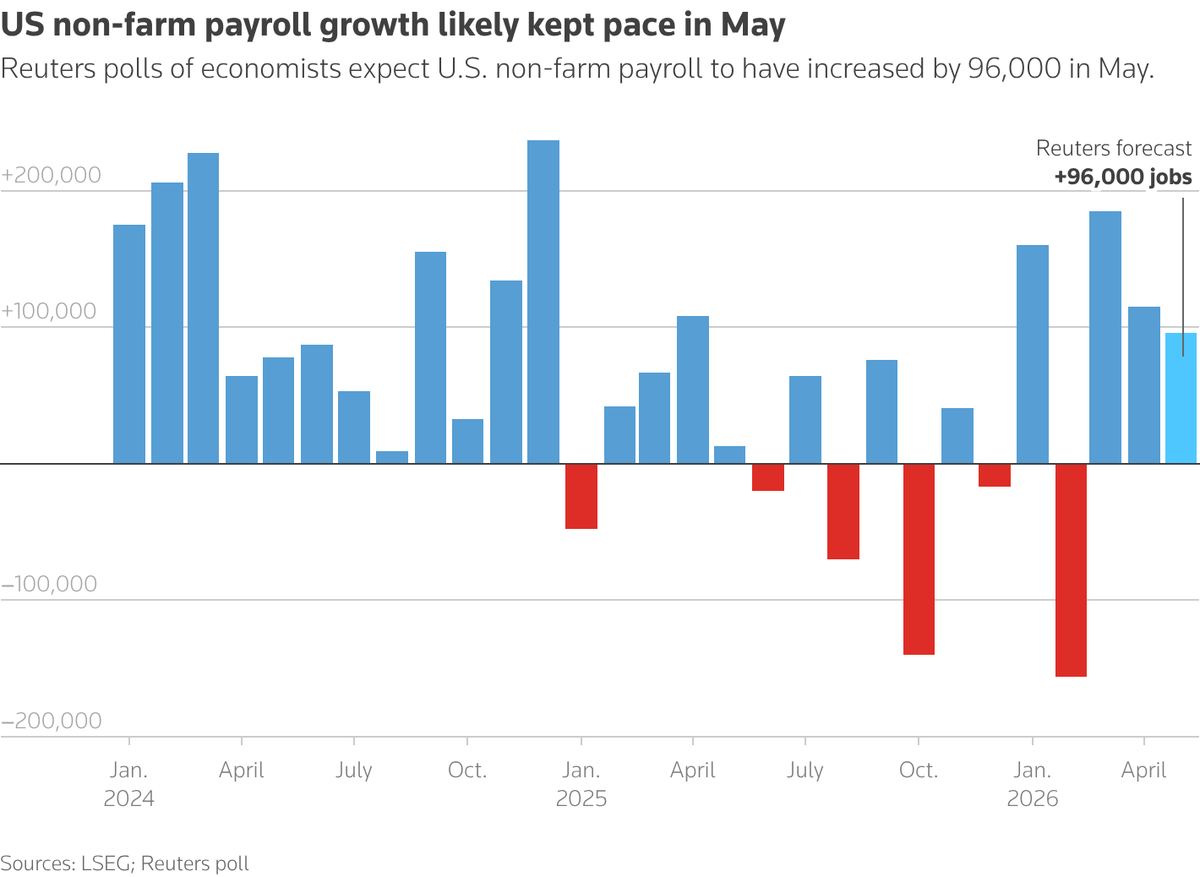
The hot payrolls run since January 2024 cools toward consensus 96k. Reuters poll 96k versus Bloomberg Economics 95k versus April's 115k. The labour market the cleanest early in the cycle signal in the macro tape. The risk is the print does not slow as expected. Warsh's first FOMC is in two weeks. Source: Reuters.
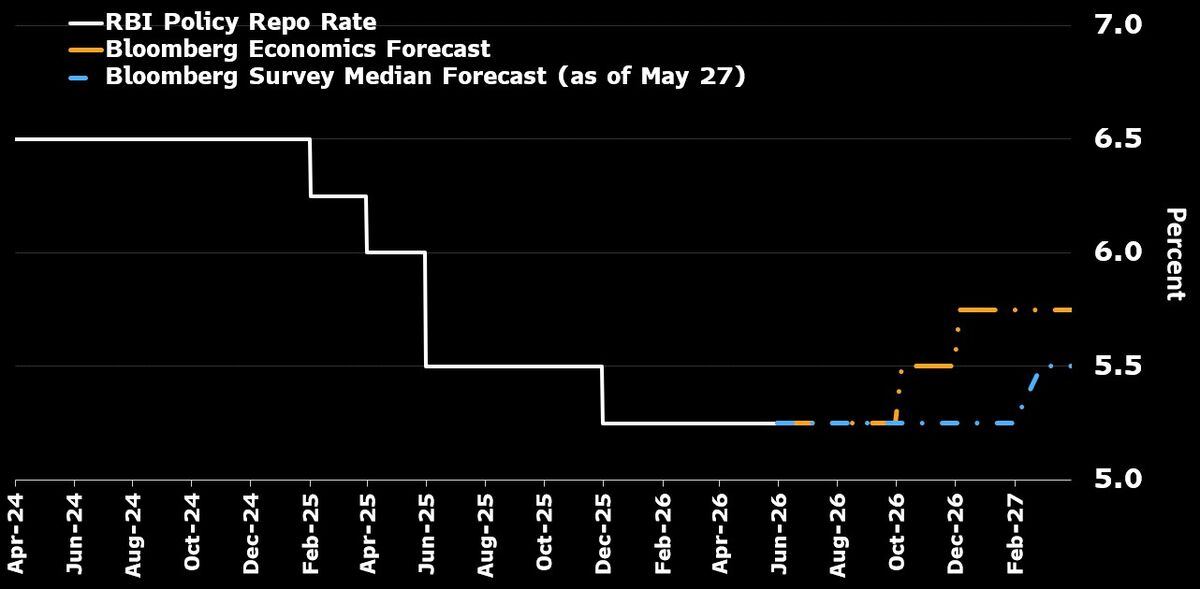
RBI to hold the repo rate at 5.25% on June 5. Inflation below target gives the RBI room to wait. The oil shock, a possible weak monsoon and gas shortages could stoke prices and pull the hike forward. Bloomberg Economics sees a mild 50bp tightening cycle starting October. Source: Bloomberg Economics.
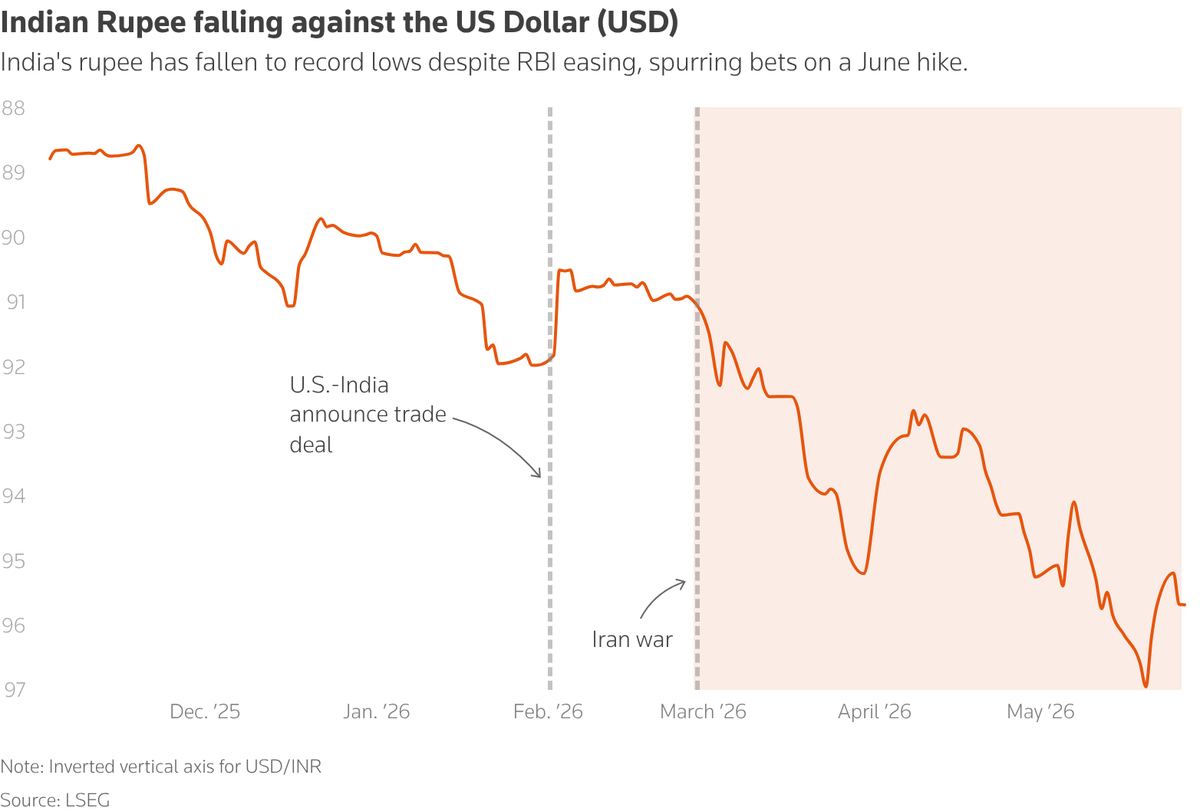
Indian rupee slide to record lows fuels June 5 hike speculation despite RBI signals of reluctance. The rupee briefly neared 97 per dollar on May 22 before central bank intervention steadied. Heavy reliance on imported oil left India exposed to the war's energy shock. Some major banks pencil in a June move; traders split evenly. Sri Lanka's 100bp hike last week the regional precedent. Source: Reuters.
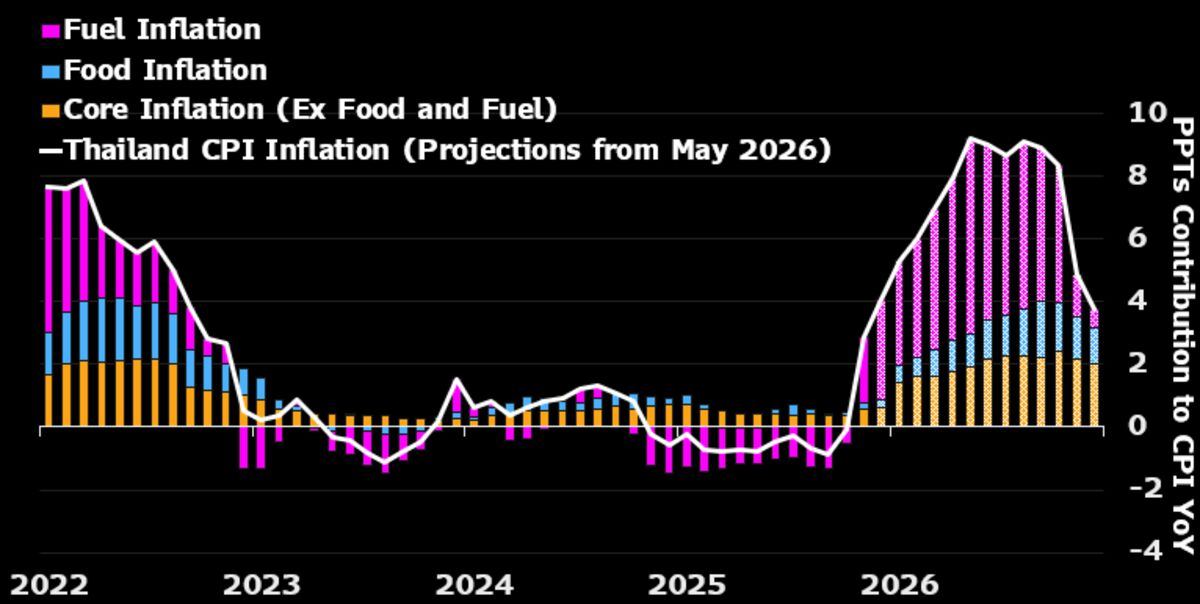
Thailand CPI likely jumped above the 1 to 3% target in May, 4.05% expected from 2.89%. Higher fuel prices drove the pickup. Inflation continues to climb into Q4. Domestic demand pressure weak but the BOT increasingly finds it hard to look through the energy shock. Source: Bloomberg Economics.
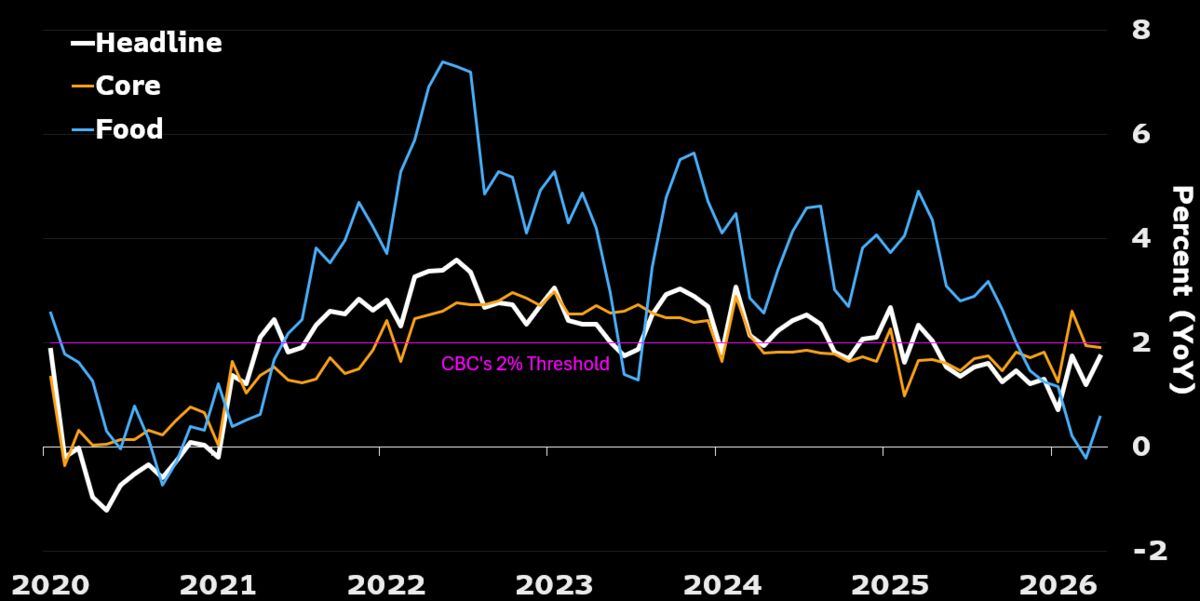
Taiwan CPI likely accelerated to 2.1% in May, slightly above the central bank 2% alert line. Government fuel price smoothing limited the passthrough. A weaker currency lifted import costs. The central bank expected to hold at 2% through 2026 despite the hawkish tilt. The chip cycle the offset. Source: Bloomberg Economics.
VC+ Special Dispatch — The State of Global Energy: Part 2
Part two of the dispatch goes inside the commodities themselves. How crude oil and natural gas move across the world, which countries produce the most, and why energy prices swing harder than anything else in the global economy. Seven charts. Credit to the VC+ team.
The Arteries of Global Oil Trade
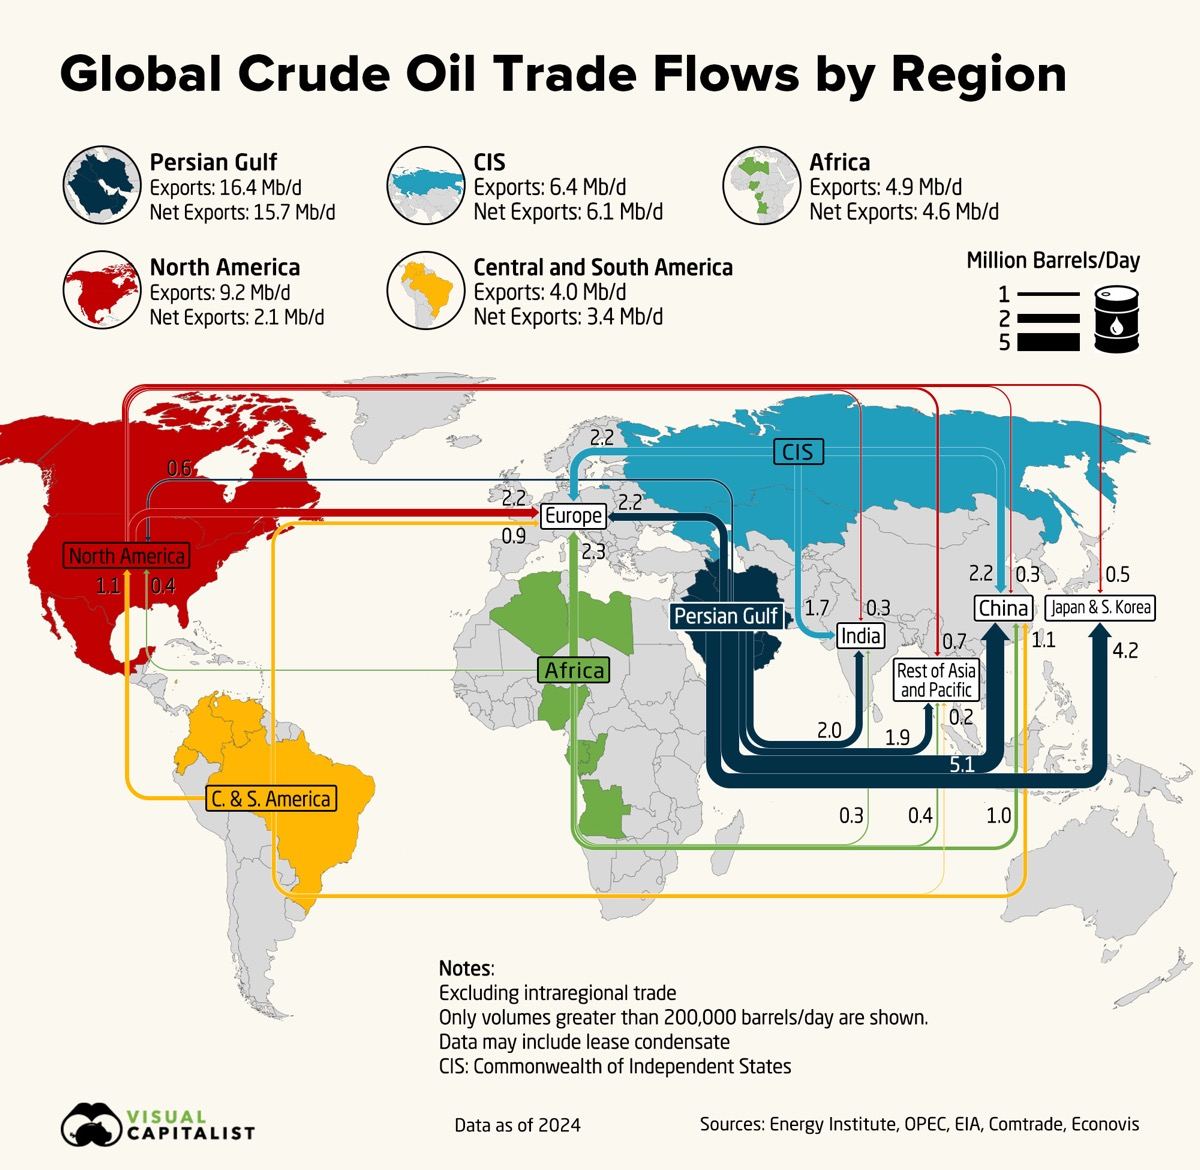
Global crude oil exports reached 43.3 million barrels per day in 2024, the flows strikingly concentrated. The Persian Gulf alone shipped 16.4 million barrels per day. Around 80% of Gulf exports headed to Asia and the Pacific. North America exported 9.2 million barrels per day, yet more than half stayed within the region. Source: Visual Capitalist.
The Great Eastward Shift in Oil
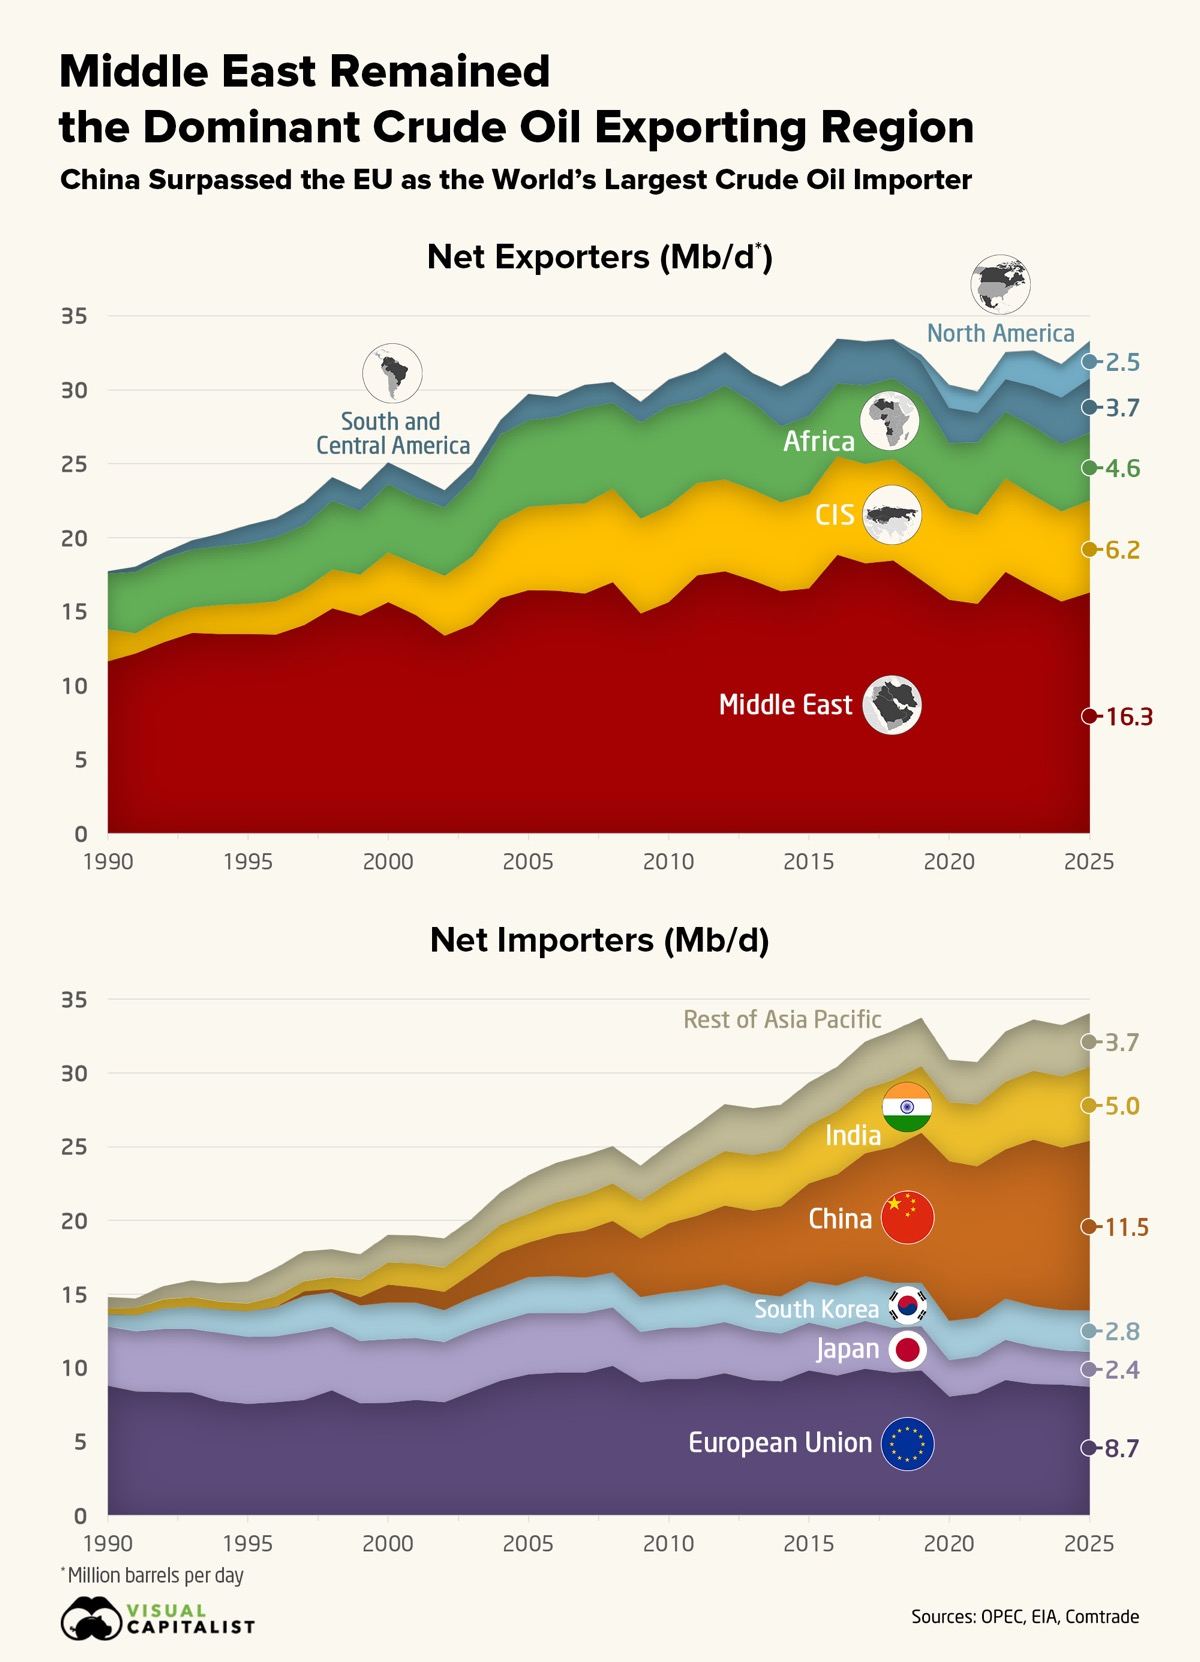
The centre of gravity for oil demand has moved decisively east. Since 2019, China has been the world's largest crude importer. China's net imports climbed from 1.2 million barrels per day in 2000 to 11.5 million in 2025. India's rose to 5.0 million. The Strait of Malacca now carries roughly 24 million barrels a day. Source: Visual Capitalist.
The Five Countries Behind Half the World’s Oil
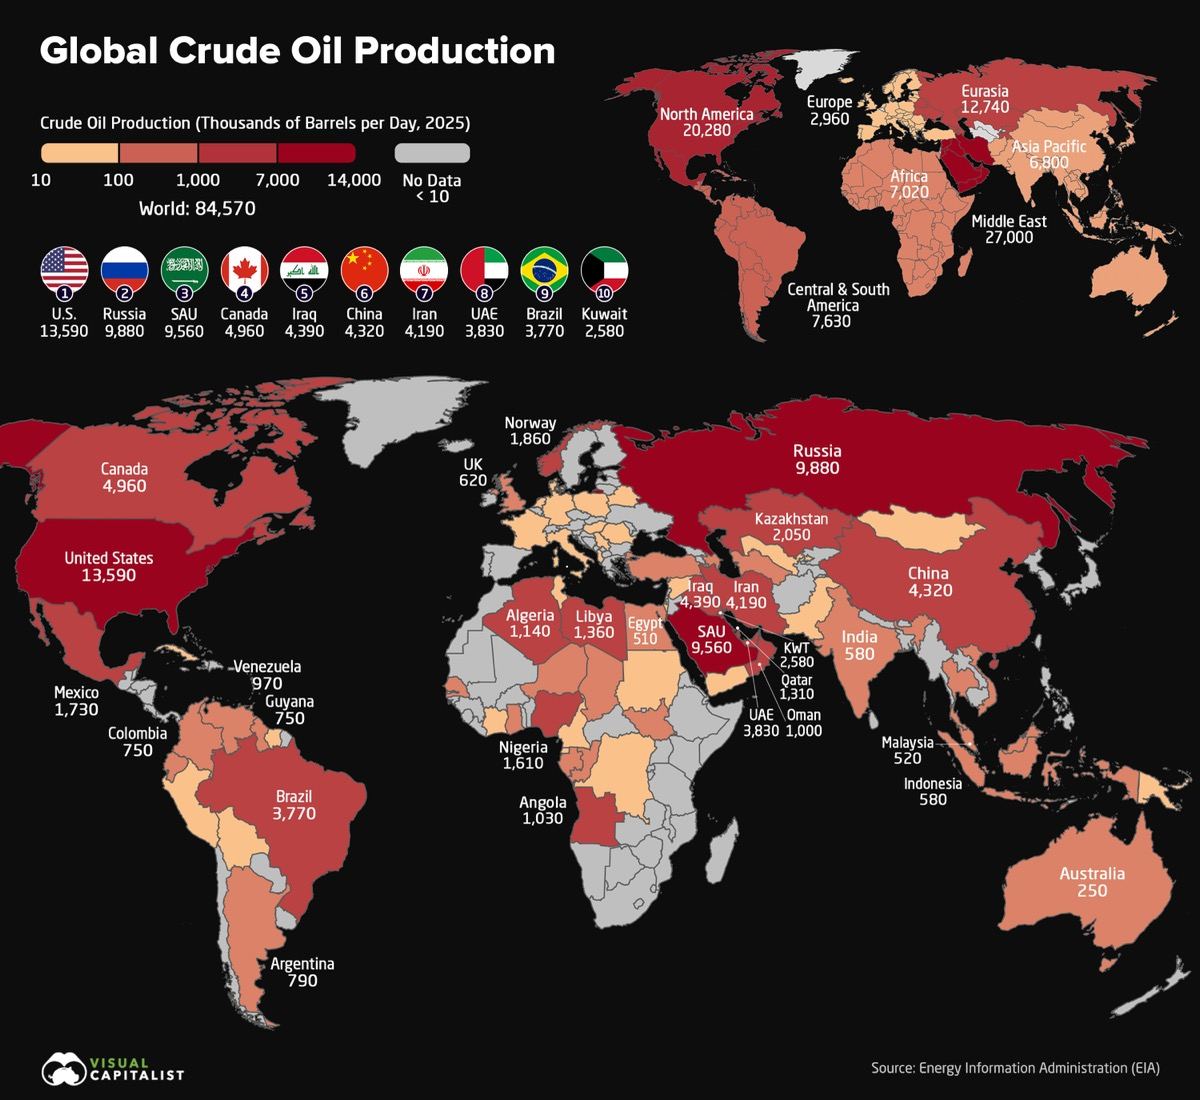
Just five countries pumped half the world's 84.6 million barrels of daily crude in 2025. The US led at 13.6 million, a record high driven by Permian Basin shale. Russia 9.9 million, Saudi Arabia 9.6 million. The top three alone account for nearly 39% of global output. The Middle East still produces the largest share of any region at 32%. Source: Visual Capitalist.
Who Ships the World’s Gas, and Who Needs It
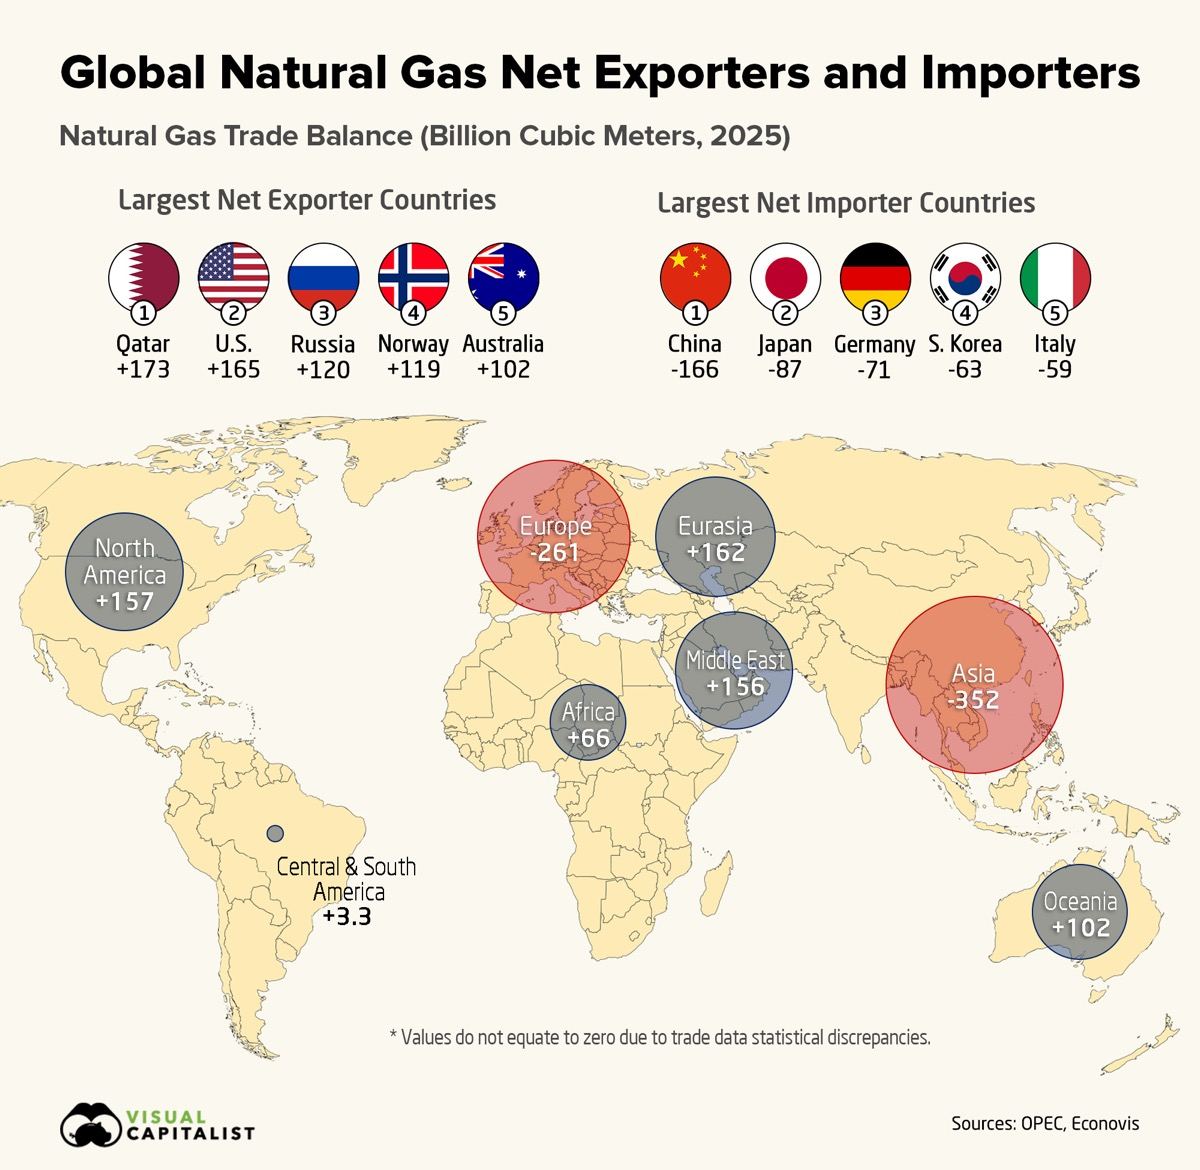
Qatar led net gas exporters in 2025 at 173 billion cubic metres, narrowly ahead of the US at 165 billion. Three regions — Eurasia, North America, Middle East — each export around 160 billion cubic metres. Asia the largest deficit region at a net 352 billion cubic metres imports. Europe close behind at 261 billion. Source: Visual Capitalist.
America’s Natural Gas Machine
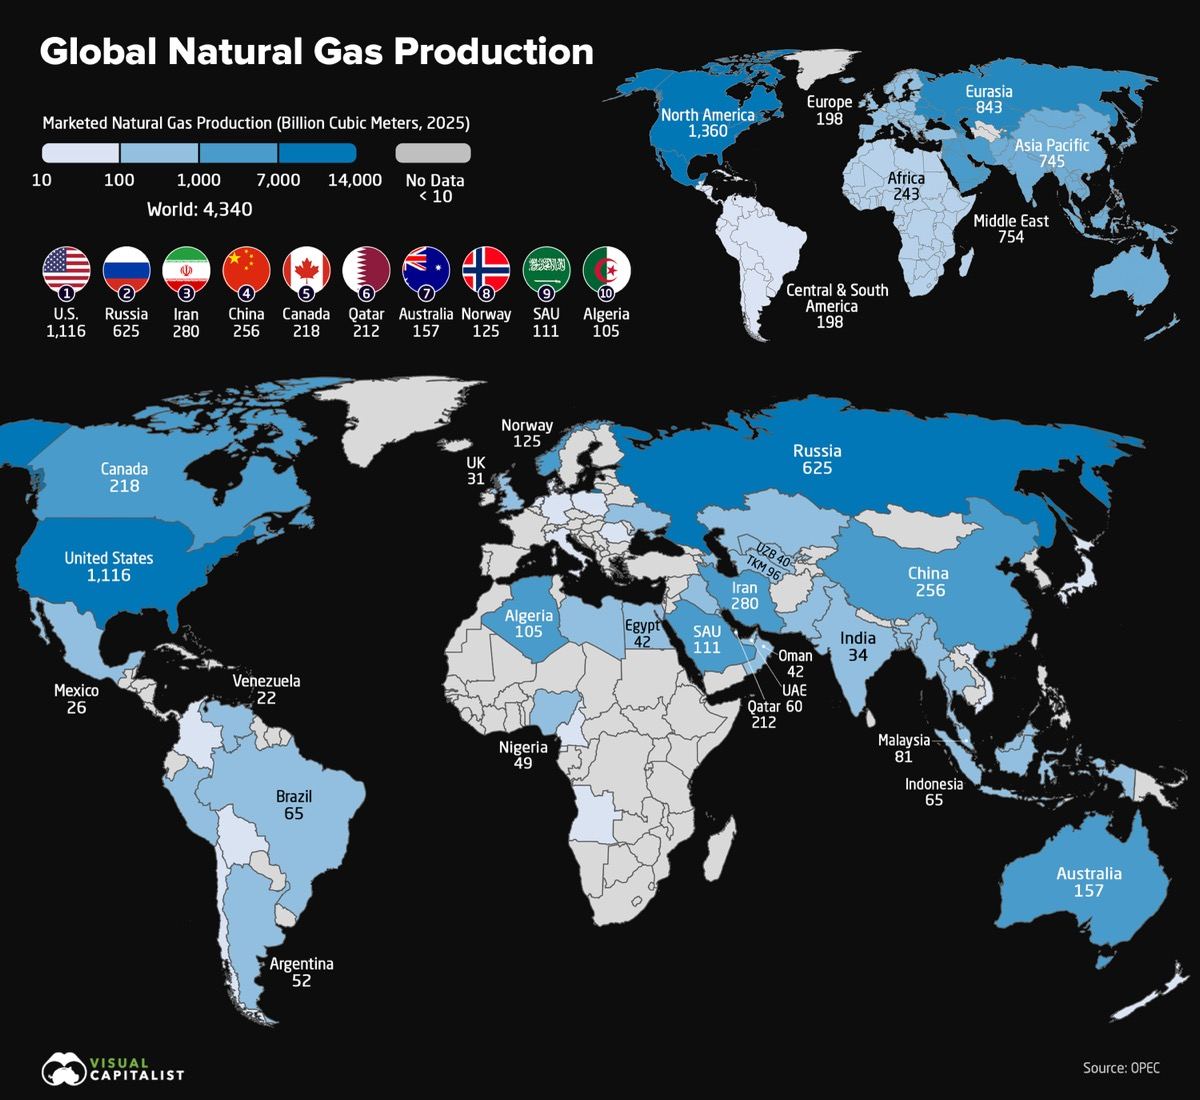
America's natural gas machine, output of 1,116 billion cubic metres in 2025. Nearly a quarter of the world's total and almost as much as the next three producers combined. Russia ranked second at 625 billion, Iran third at 280 billion. In 2025 the US became the first country ever to export more than 100 million tonnes of LNG in a single year. Capacity set to nearly double by the end of the decade. Source: Visual Capitalist.
Why Energy Prices Swing the Hardest
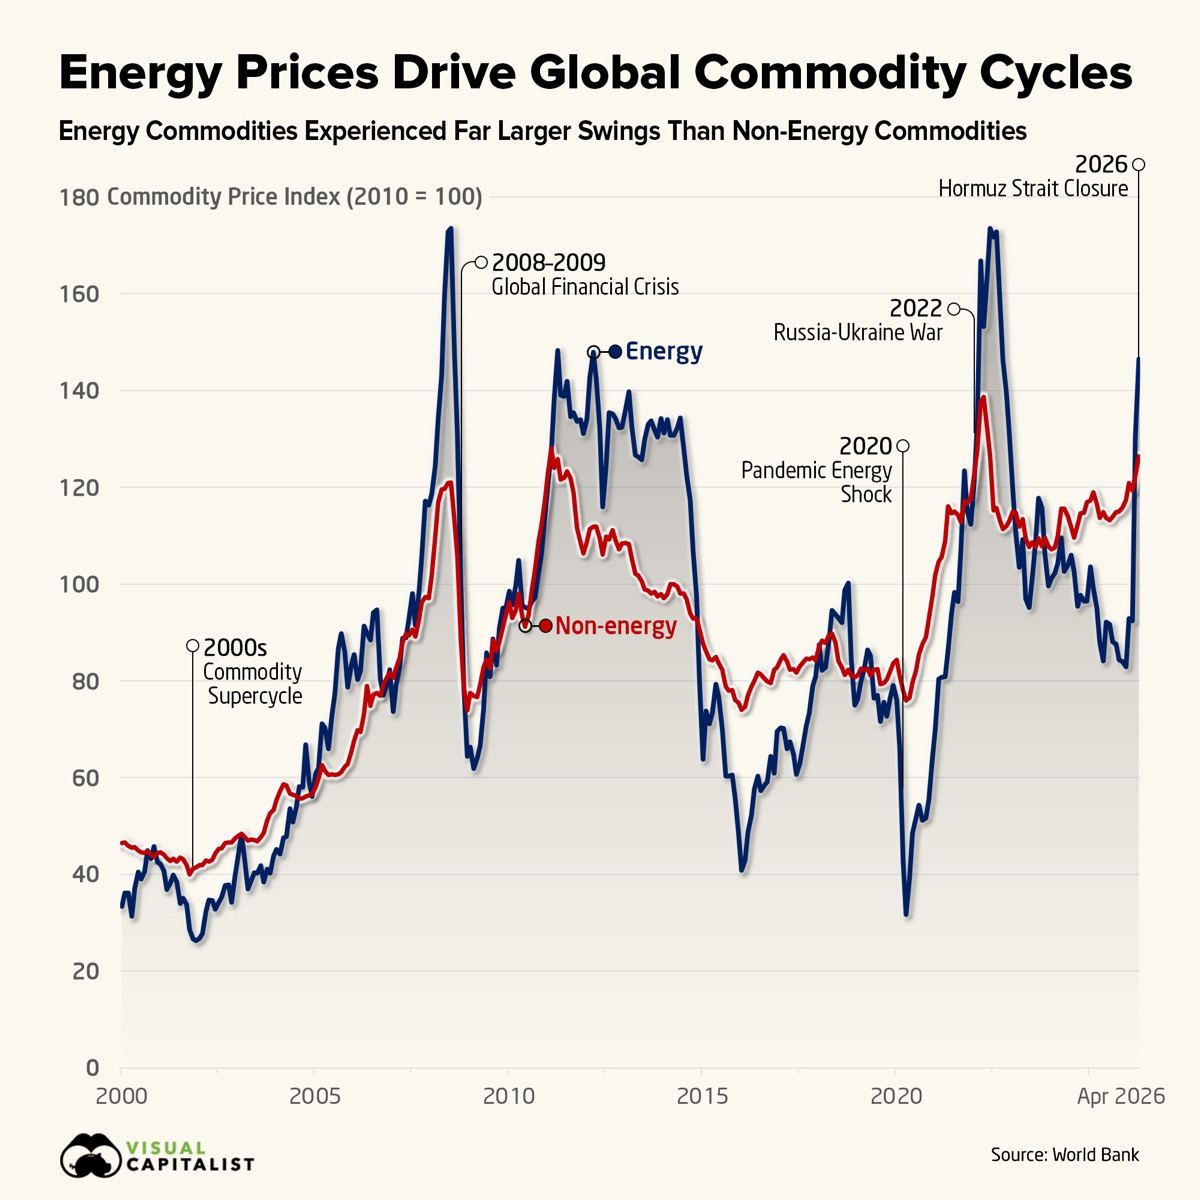
Energy prices swing the hardest. Energy and non energy commodities move together but energy swings far more violently. The 2000s commodity supercycle: energy 210%, non energy 120%. Every major shock since has followed the same pattern. By April 2026 the Hormuz disruption had pushed energy prices 63% above the 2025 average versus 9% for non energy commodities. Source: Visual Capitalist.
The Economic Weight of Fossil Fuels
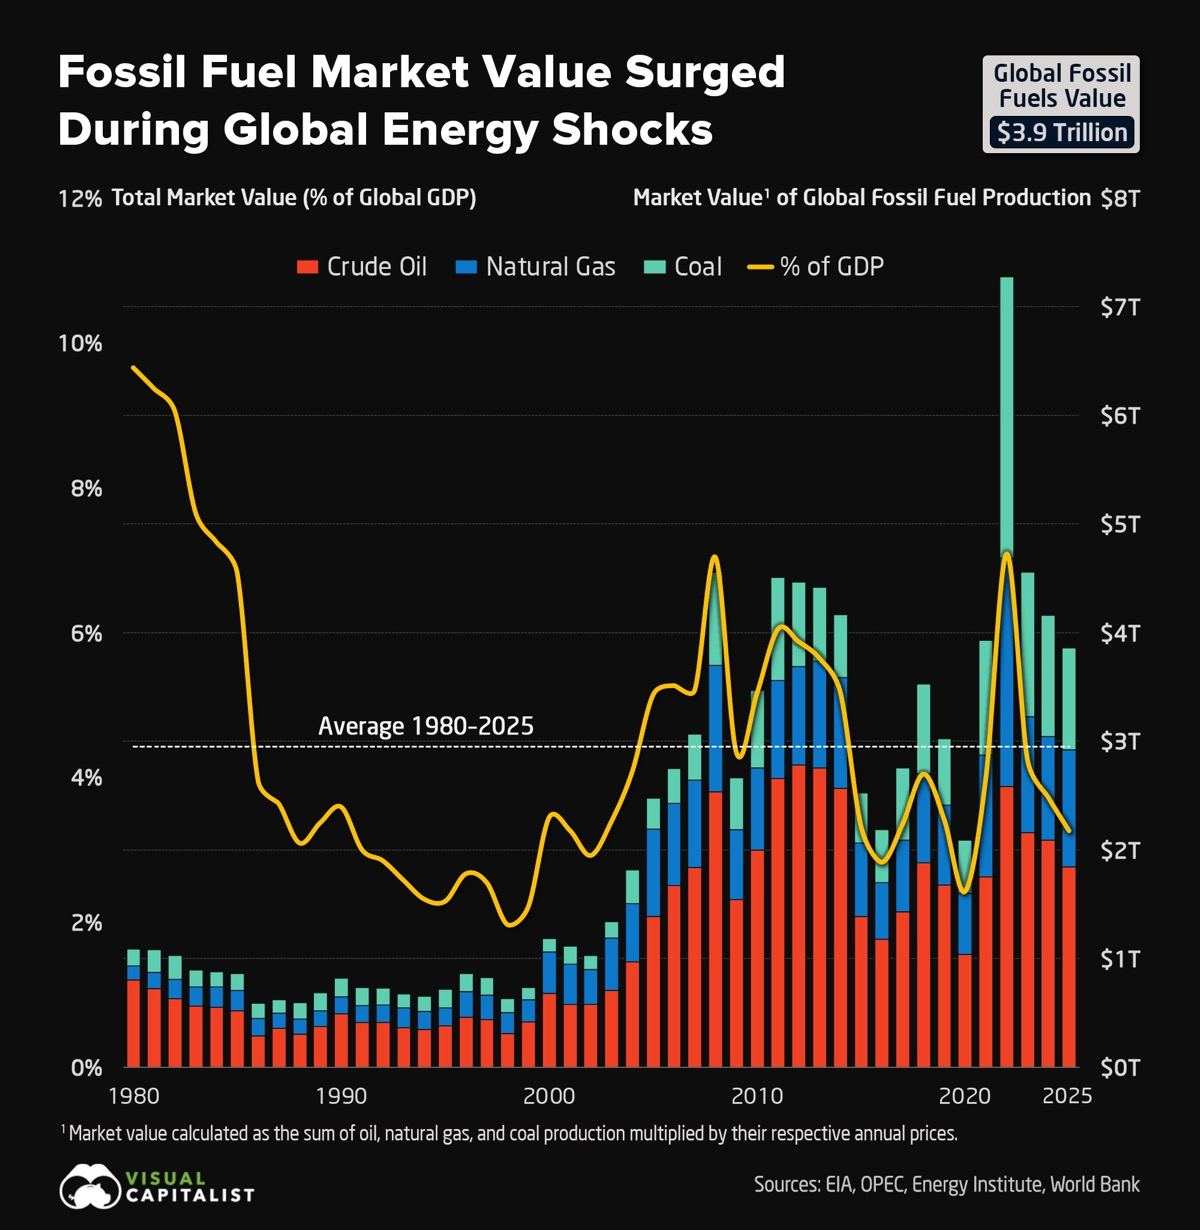
Fossil fuels swallow an outsized share of the world economy when prices spike. In 1980, oil gas coal production was 9.7% of global GDP. The measure has averaged around 4% since but surges with every crisis. The 2022 energy shock pushed value to 7.3 trillion, or 7.1% of world GDP. Today near 3.9 trillion. The 1980 high has never been surpassed. Source: Visual Capitalist.
The Good Wrap
What is left at the close. Exxon and Chevron put 150 to 160 dated Brent in the model when the operational floor hits. The UN going broke as the US and China withhold billions. Colombia’s first round runoff trigger. Hong Kong overtakes Switzerland as the largest cross border wealth hub, and the corporate services and family office build out underneath. The HK and Singapore AI chill in finance jobs. Cursor’s Developer Habits Report on the productivity dispersion beneath the AI doubles output headline. The JP Morgan Mid Year Outlook chart on the 25 largest S&P 500 IPOs ahead of the SpaceX print. Singapore durian season. Closing on biodynamic wine.
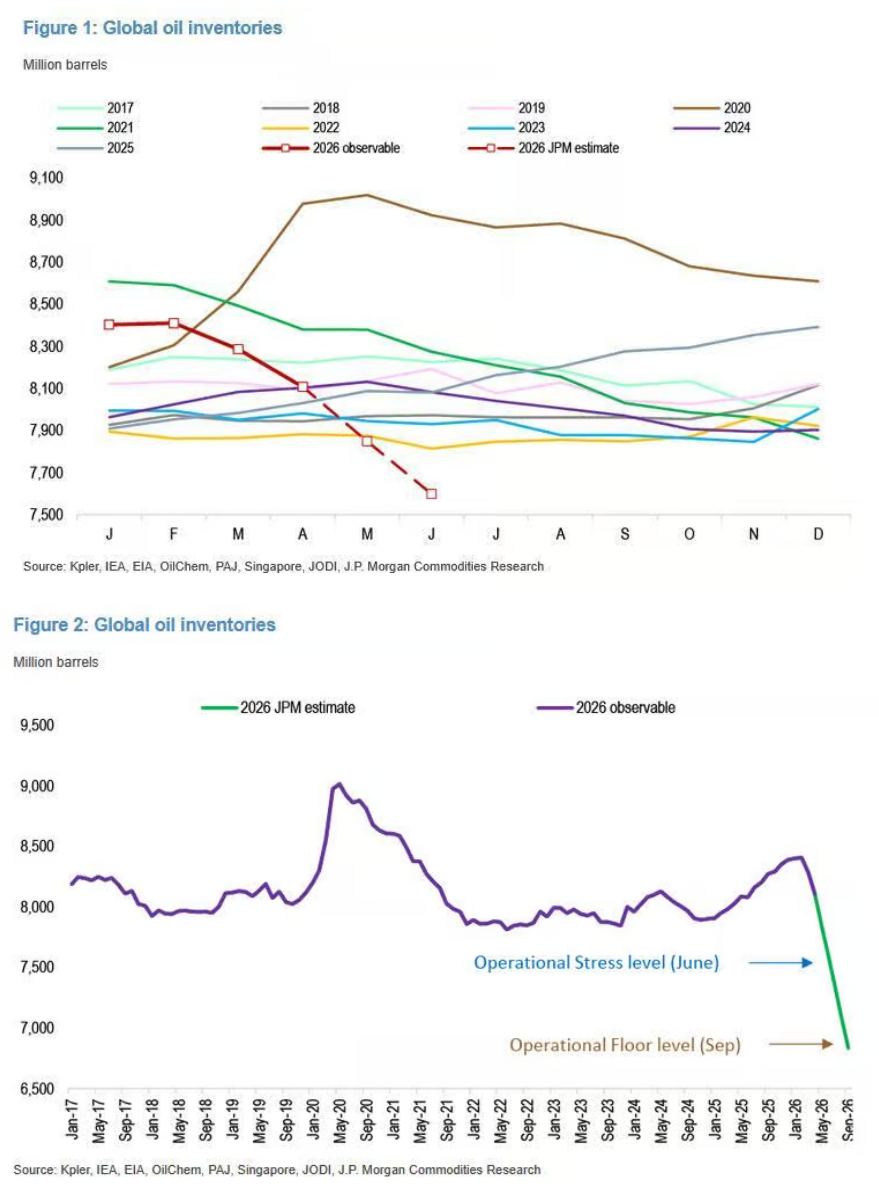
Approaching unheard of inventory levels, Exxon and Chevron issue an apocalyptic warning. Chevron CEO Mike Wirth: the buffers and shock absorbers are being steadily drawn down. Exxon SVP Neil Chapman: once you get to that really low inventory level, up to 150, 160. The war removed 12 to 13 million barrels a day from global markets. Adnoc says full Hormuz flows do not return before Q1 2027. Read the ZeroHedge writeup. Source: ZeroHedge.
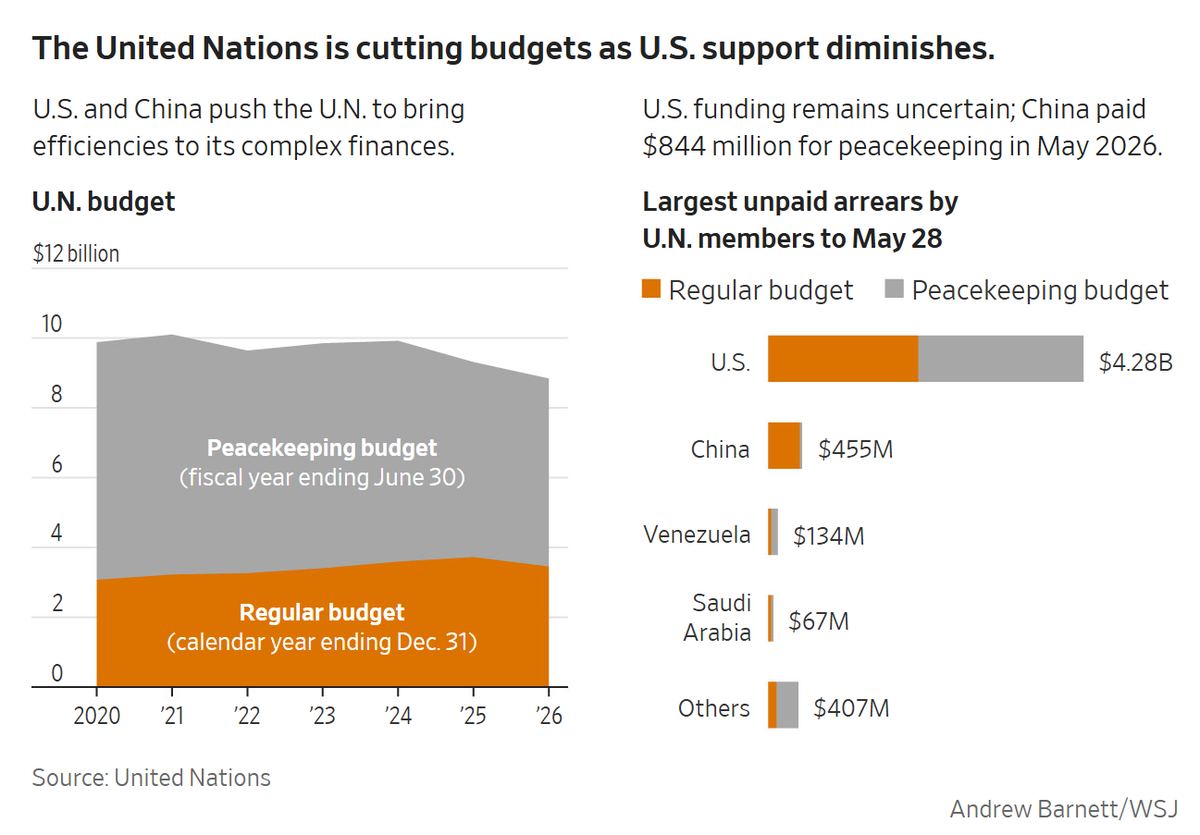
The UN is going broke as the US and China withhold billions. The US more than 4 billion in arrears. China still owes 455 million even after injecting 850 million during Wang Yi's visit. The UN relies on US and Chinese money for 42% of basic funding. Guterres warned of a race to bankruptcy by mid August. The UN closed offices and eliminated a record 3,000 secretariat posts. Read the WSJ piece. Source: WSJ.
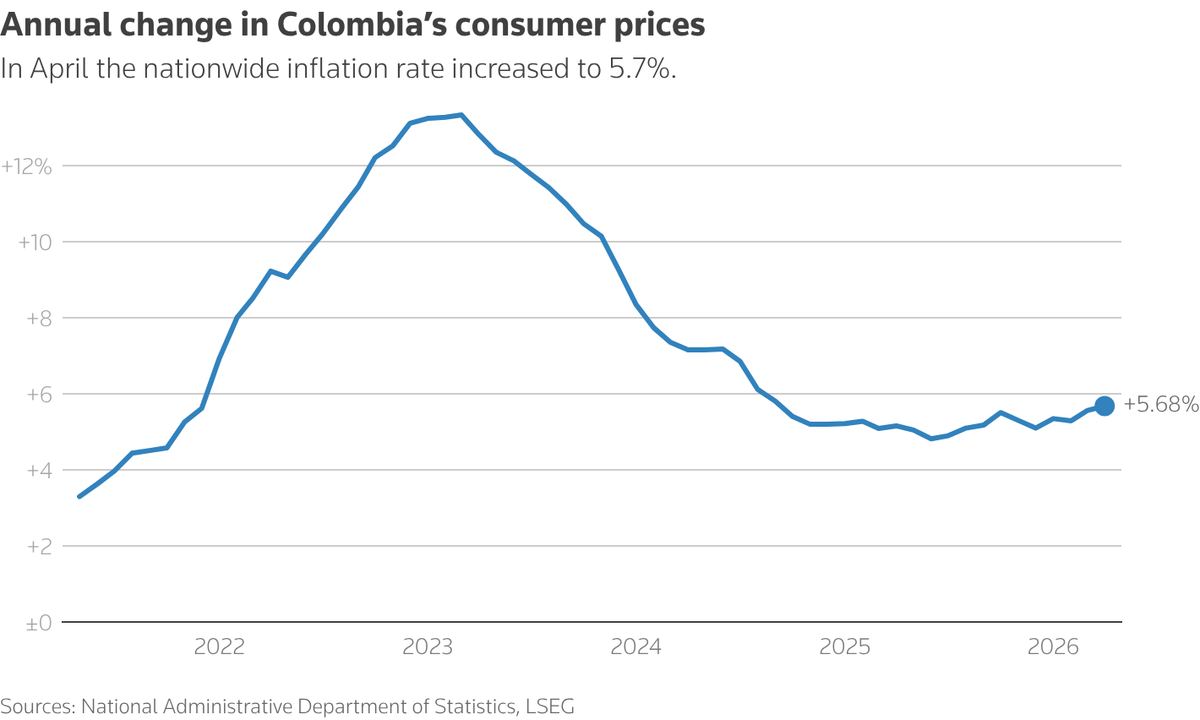
Colombia first round vote Sunday sets up the June 21 runoff. Leftist Senator Ivan Cepeda leads but is unlikely to secure outright. The focus is on who advances with him. Cepeda promises social spending continuity. Rivals tout tighter fiscal, market friendly incentives, tougher security. The peso and Ecopetrol shares offer immediate verdict. Source: Reuters.
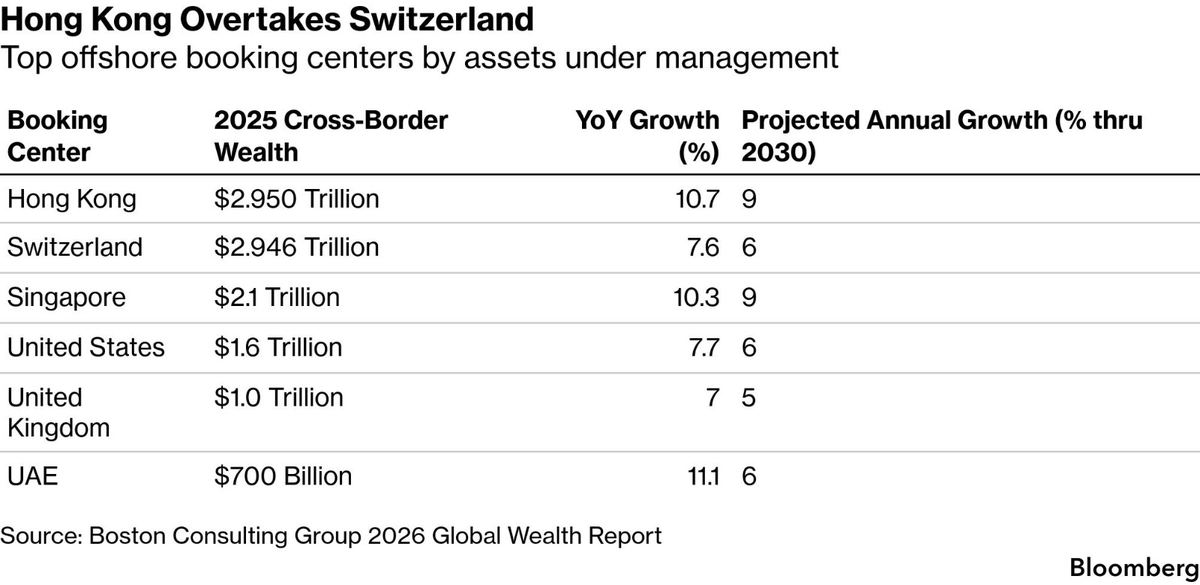
Hong Kong overtakes Switzerland as the world's largest cross border wealth hub. Driven by mainland Chinese capital and a resurgent local equity market. Global private fortunes total 333 trillion, the fastest expansion since 2021. Iran war geopolitics prompting the ultra wealthy to diversify into Asia. Source: Bloomberg.
The Asian wealth hub story has a second leg, the corporate services and family office build out. The infrastructure beneath the headline: funds, family offices, single family advisors, regional booking centres. The diversification flow that started in 2022 has accelerated with the Iran war. Source: Bloomberg.
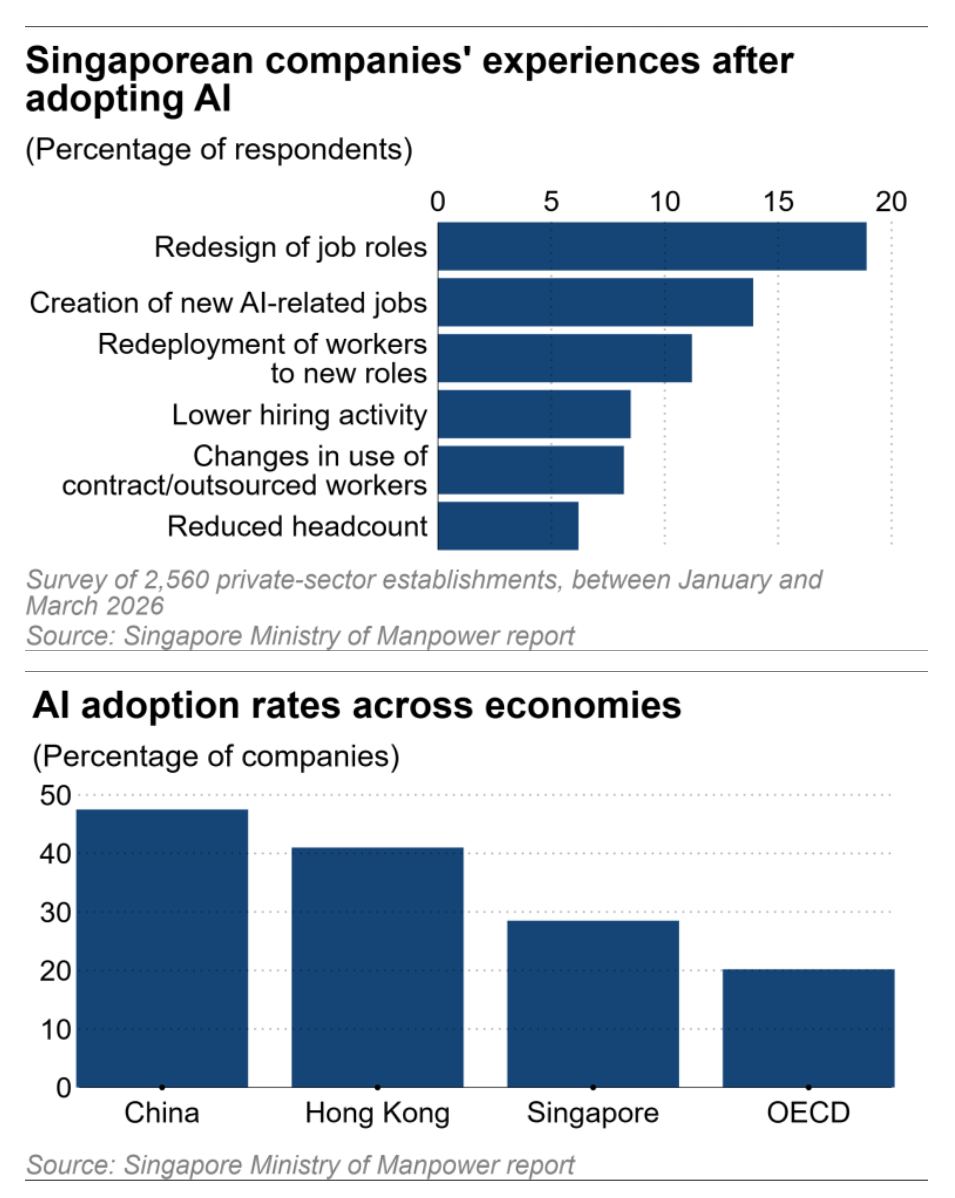
Hong Kong and Singapore brace for the AI chill in finance jobs. Junior and back office support roles among the first hit. Hong Kong graduate vacancies plunged over 60% in three years, from 80,000 in 2022 to 31,000 in 2025. HSBC and Standard Chartered the first global banks to warn of massive AI driven cuts. Meta cut 8,000 globally with Singapore staff among the first. Read the full Nikkei Asia piece. Source: Nikkei Asia.
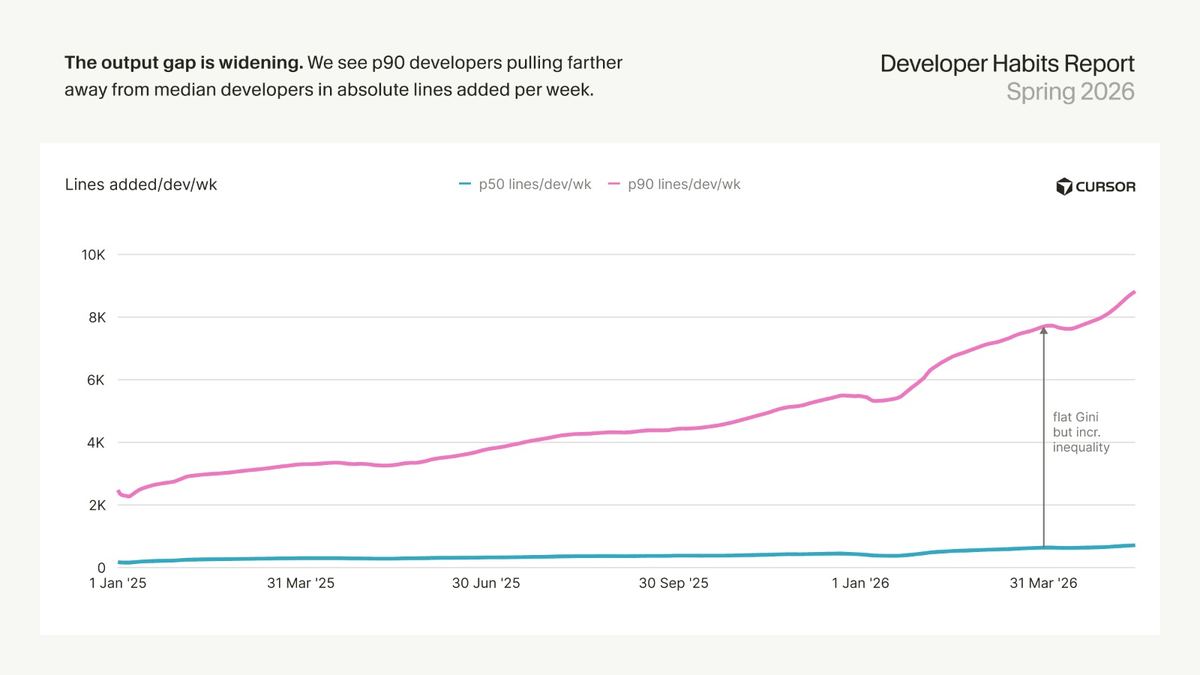
Cursor's Developer Habits Report, AI doubles dev output but not for everyone. Lines of code per dev per week from 3.6k to 8.6k in 18 months. Agent tool calls up 30% in two months and five times more AI made changes reach commits without manual review. The top 1% of devs produce 46 times more code than the median active user, and the gap widens every month. Read Cursor's report. Source: Cursor / The Rundown AI.
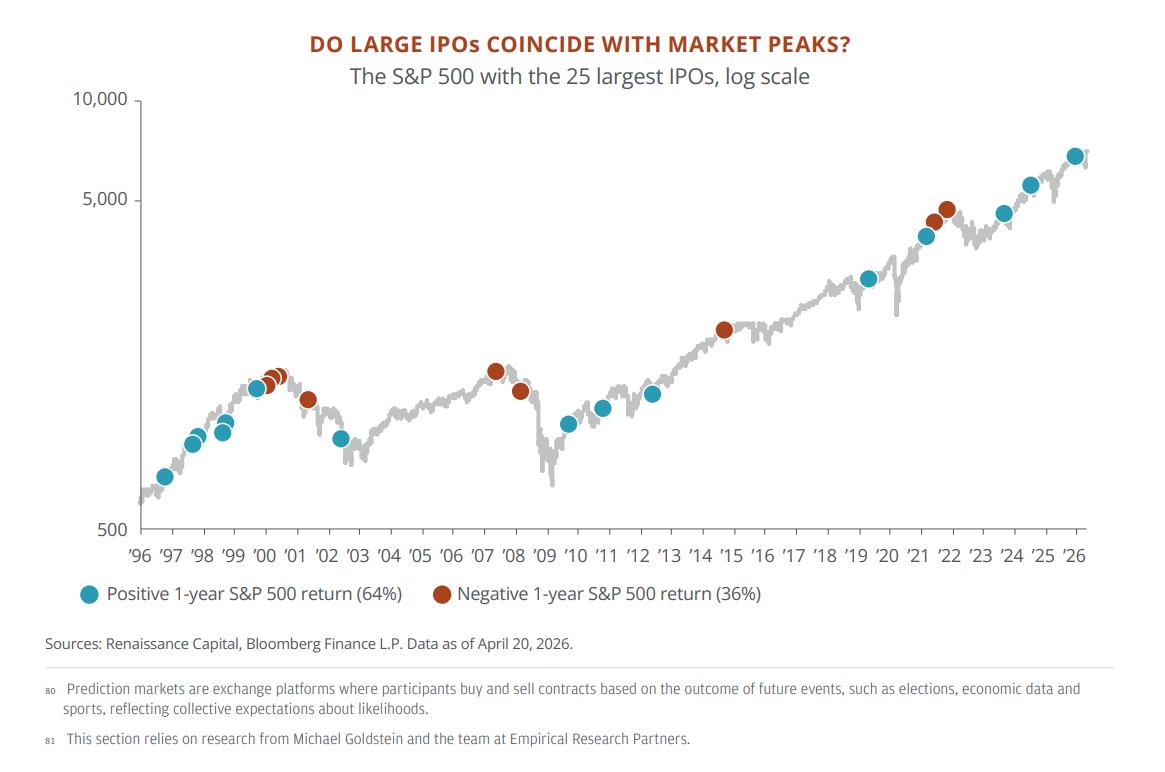
JP Morgan Mid Year Outlook, the 25 largest S&P 500 IPOs in three decades. SpaceX's expected 2 trillion IPO in June could become the largest public offering in history. Listings often take place around market peaks. 18 of the 25 largest IPOs underperformed the S&P by a median of 30% in the year after listing. First day returns averaged 35% in 2025 versus 50% in 2021. Read the JPM Outlook. Source: J.P. Morgan Mid-Year Outlook 2026.
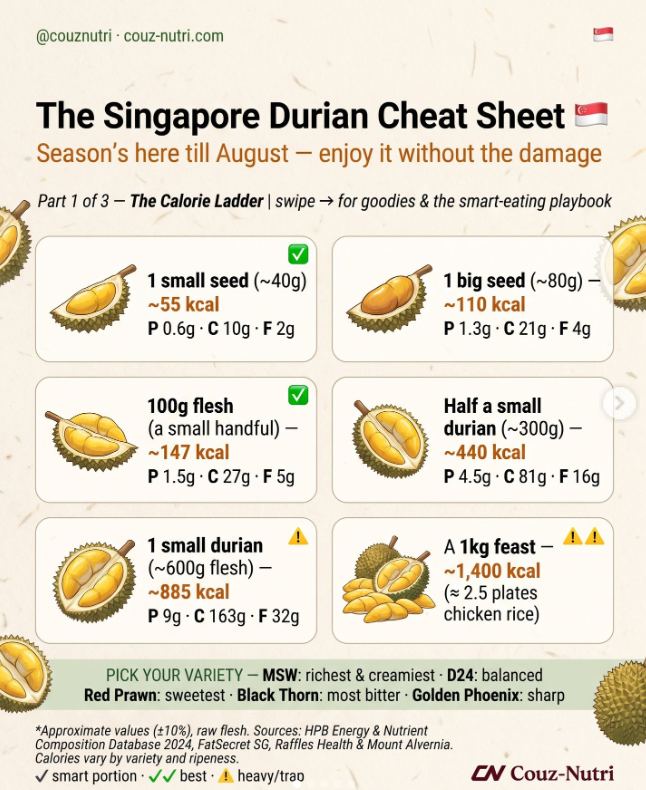
Durian season back in Singapore. One small durian about 885 kcal, nearly half the day's calories. A durian puff 77 kcal. A whole durian snowskin mooncake 819 kcal and 42 grams of fat, more fat than a whole small durian. The trap is not the fruit. It is the goodies. Source: Instagram (Singapore durian).
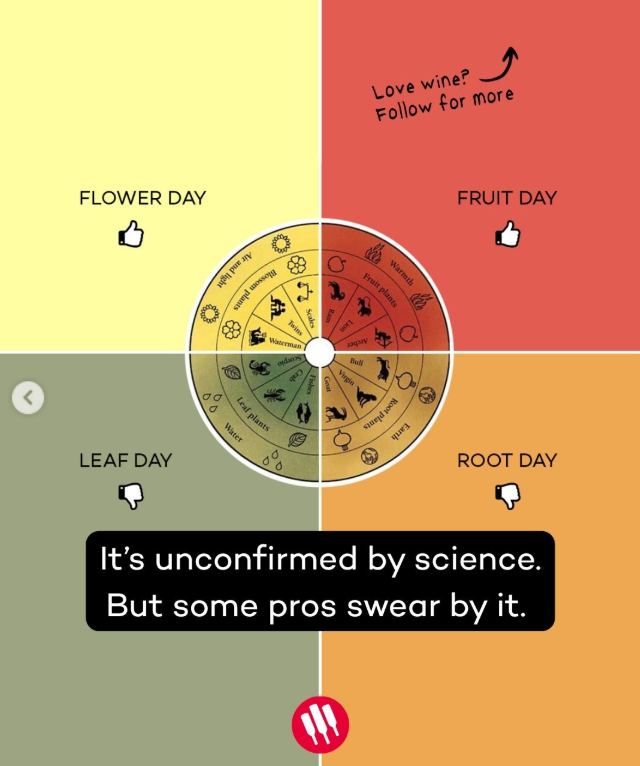
Biodynamic wine and the calendar. Days divided by the moon's position relative to zodiac constellations. Fruit, flower, leaf and root. Fruit days favour structured reds. Flower days flatter aromatic varieties. Root and leaf days can make wines feel muted. Science has not confirmed the lunar tasting link. The idea persists because tasters notice consistent patterns. Source: WineFolly.
Best,
Hoelon
WITPTW is a personal publication. Everything here is personal opinion and market commentary, written in a personal capacity. It is not investment advice and not a recommendation to buy or sell any security. It is not associated with, endorsed by, or representative of any employer, fund or company. Charts and images are reproduced from their original publishers, credited to their sources for commentary and discussion; all rights remain with the respective copyright holders.