The Path of Least Resistance
Personal views and market commentary. Not investment advice. Not associated with any employer or firm.
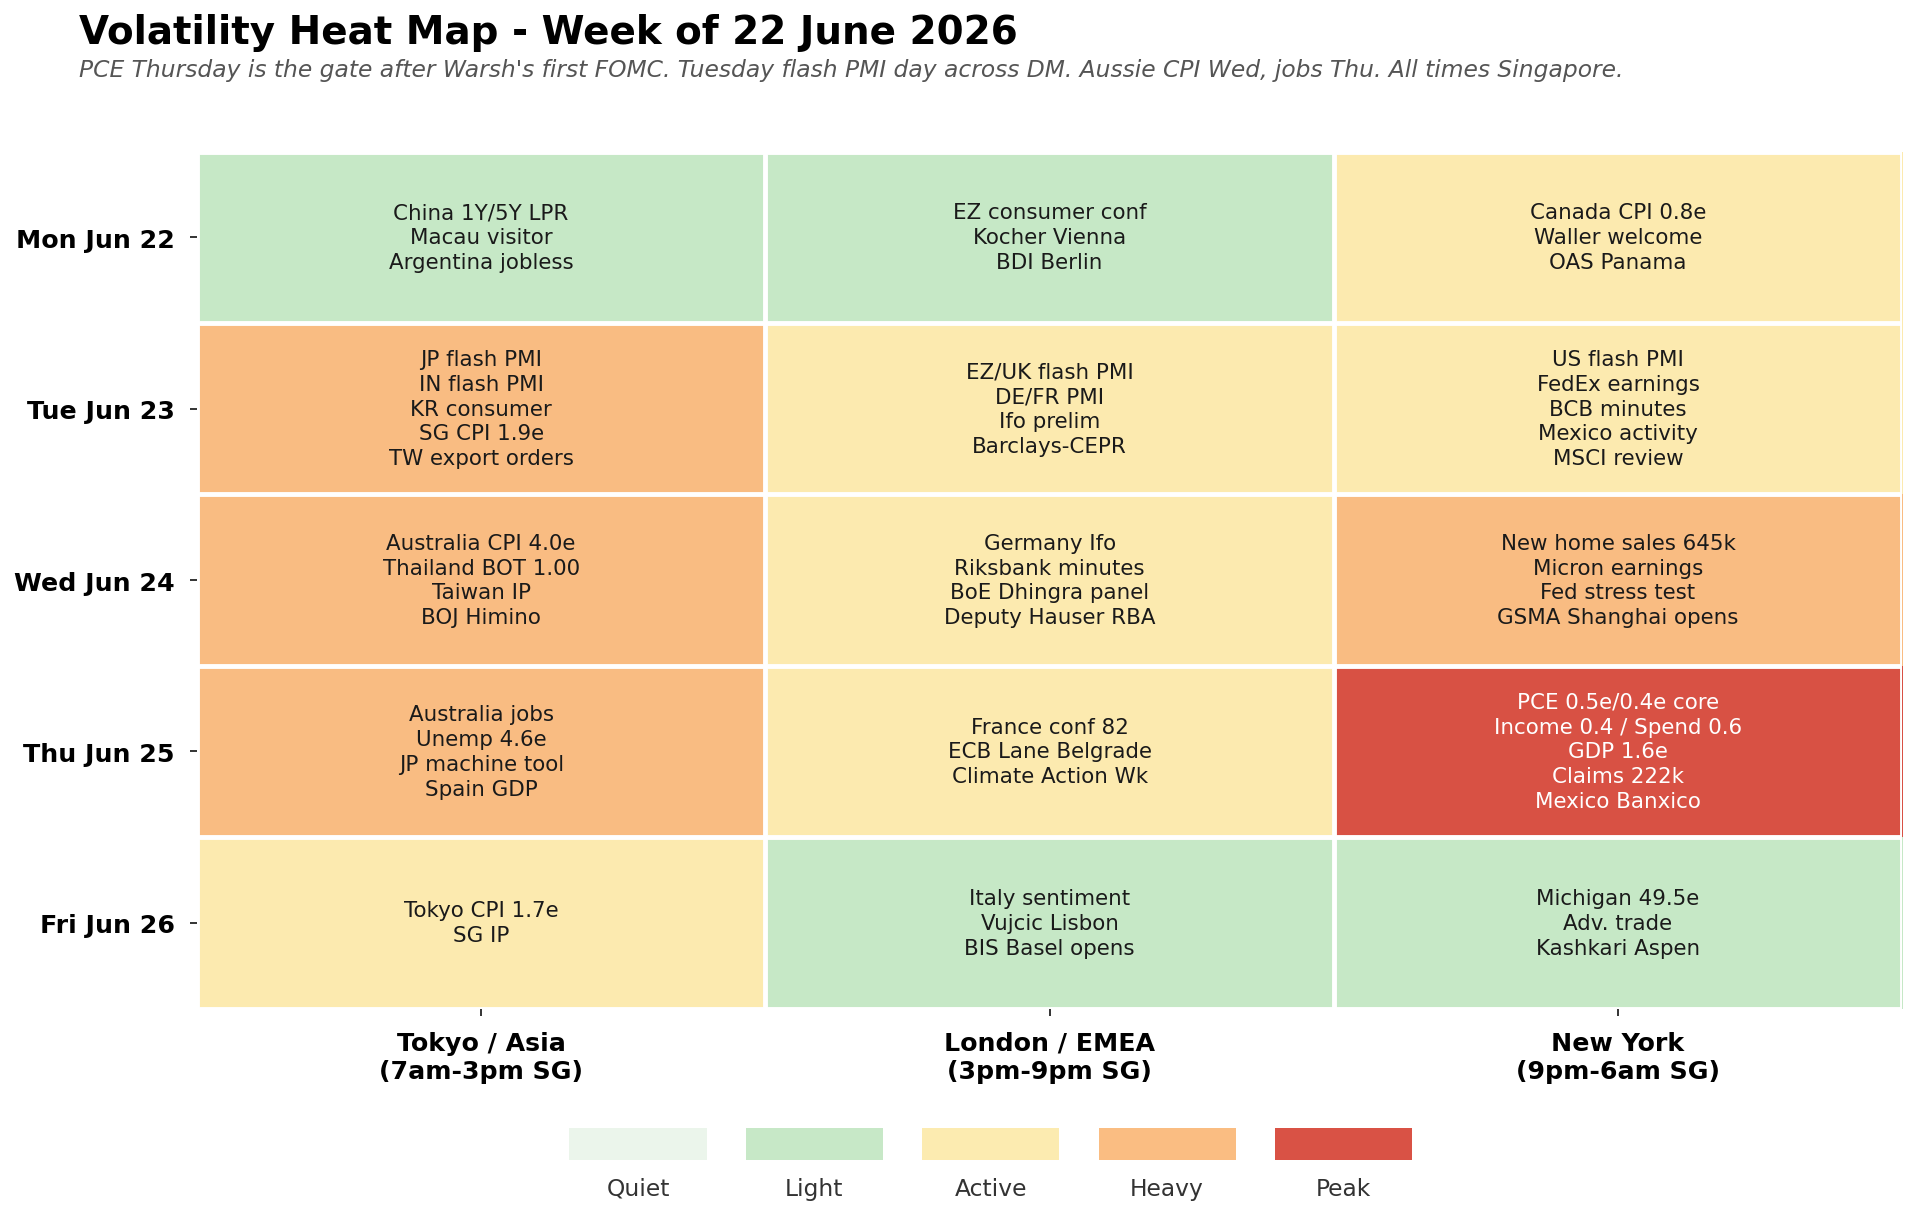
Volatility heat map for the week ahead, all times Singapore. Data-light week but PCE Thursday is the gate. Tuesday is the DM flash PMI day across Japan, India, Korea, eurozone, UK and the US. Wednesday brings Australia CPI, Thailand BOT, Germany Ifo, Micron earnings and the Fed bank stress test. Thursday is the busiest — Australia jobs and Mexico Banxico in Asia and London, PCE plus GDP plus durable goods plus claims in New York. Friday closes with Tokyo CPI, Michigan sentiment and the 25th BIS Annual Conference in Basel.
"Inflation is well ahead of the Fed's 2% goal. The 2% inflation target remains the Fed's long-held objective, and I see no reason to revisit that goal until it is achieved. Forward guidance is not well-suited to the current policy stance. The Fed will deliver price stability." — Kevin Warsh, first FOMC press conference as Chair, June 17, 2026. A dramatically shorter statement, no forward-guidance reference, the chair himself absent from the dot plot. Nine of the remaining eighteen members baked in at least one hike this year. Markets repriced a hike in as early as October. The two-year jumped 13 basis points, the largest one-day move since April 2025. The dollar broke to a fresh high since May 2025. The post-Powell era is here and the first read is hawkish.
"Fauci worked with politicized career leadership in the Intelligence Community to suppress the truth about his actions, the virus' lab leak origins, and his role in directing U.S. funding for this dangerous research that caused immeasurable harm and countless lost lives." — Office of the Director of National Intelligence, June 2026. The statement accompanied a release of declassified documents by outgoing DNI Tulsi Gabbard and is among the strongest official accusations made against Dr Anthony Fauci since the pandemic began. Whether this is a deliberate cover-up remains contested. The documents raise serious questions and reignite the lab-leak debate but do not by themselves establish criminal wrongdoing, nor do they conclusively prove that COVID originated from a laboratory. Six years on the origin question remains one of the most politically charged and scientifically disputed issues of our time. Markets have a habit of revisiting questions long after consensus has moved on. The lesson is less about who was right and more about how quickly uncertainty gets mistaken for certainty.
"The demand for great portfolio managers has never been higher. But the layer of people underneath them is disappearing fast. Firms aren't building teams around PMs anymore, they're handing one person an AI tool and calling it a day." — Sean Sweeney, CW Talent Solutions, via Bloomberg. Postings for entry-level finance analyst roles in London fell from 350 to roughly 80 in a year. The jobs that survive and expand alongside AI are the ones built on judgment, relational intelligence, and pattern recognition that no document captures, the tacit layer that takes years of starting-from-the-bottom experience to develop. Sweeney's sentence is the structural break the markets industry is now living through. Strip out the early-career bench and the future PM bench goes with it. The trade is to be the person who keeps the tacit layer alive, and to read the implications of an AI-driven analyst shortage for compensation, deal flow, and the next cycle of talent allocation.
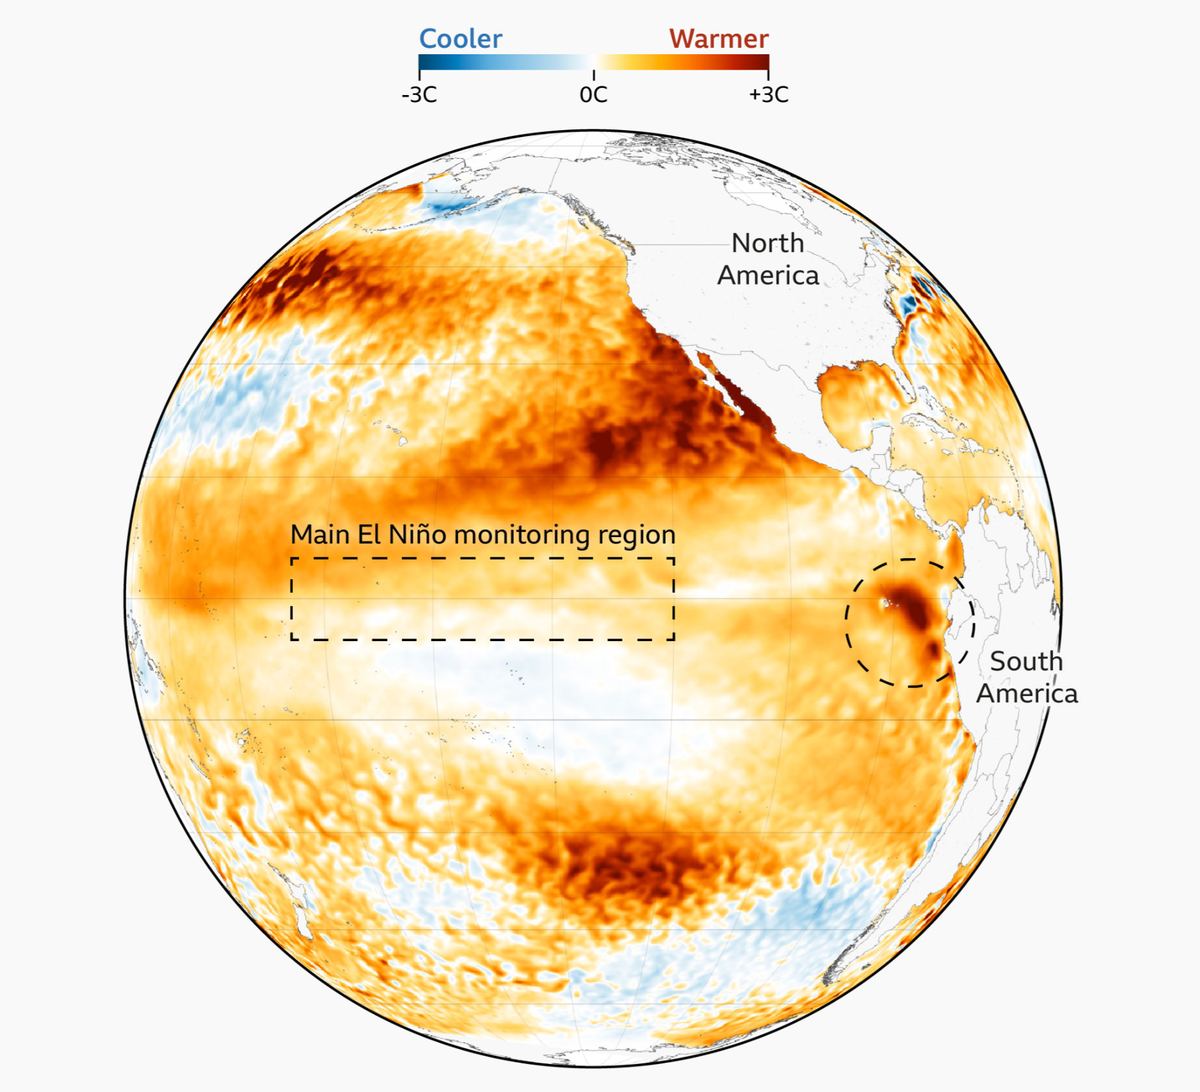
El Niño SST anomaly — the Pacific is running warm again. Sea-surface temperature anomalies of +2 to +3°C across the main monitoring region. Per the Bloomberg piece this weekend, a high probability of a "Super El Niño" heading into 2027 may drive up temperatures, hurt crop yields and reignite inflationary pressures, complicating the outlook for central banks at a moment when global equities sit at record highs. Already being felt — a delayed start to the Indian monsoon, a temporary halt to Peru's fishing season. The sectors investors are watching are agriculture, energy, mining and insurance. Source: NOAA / BBC.
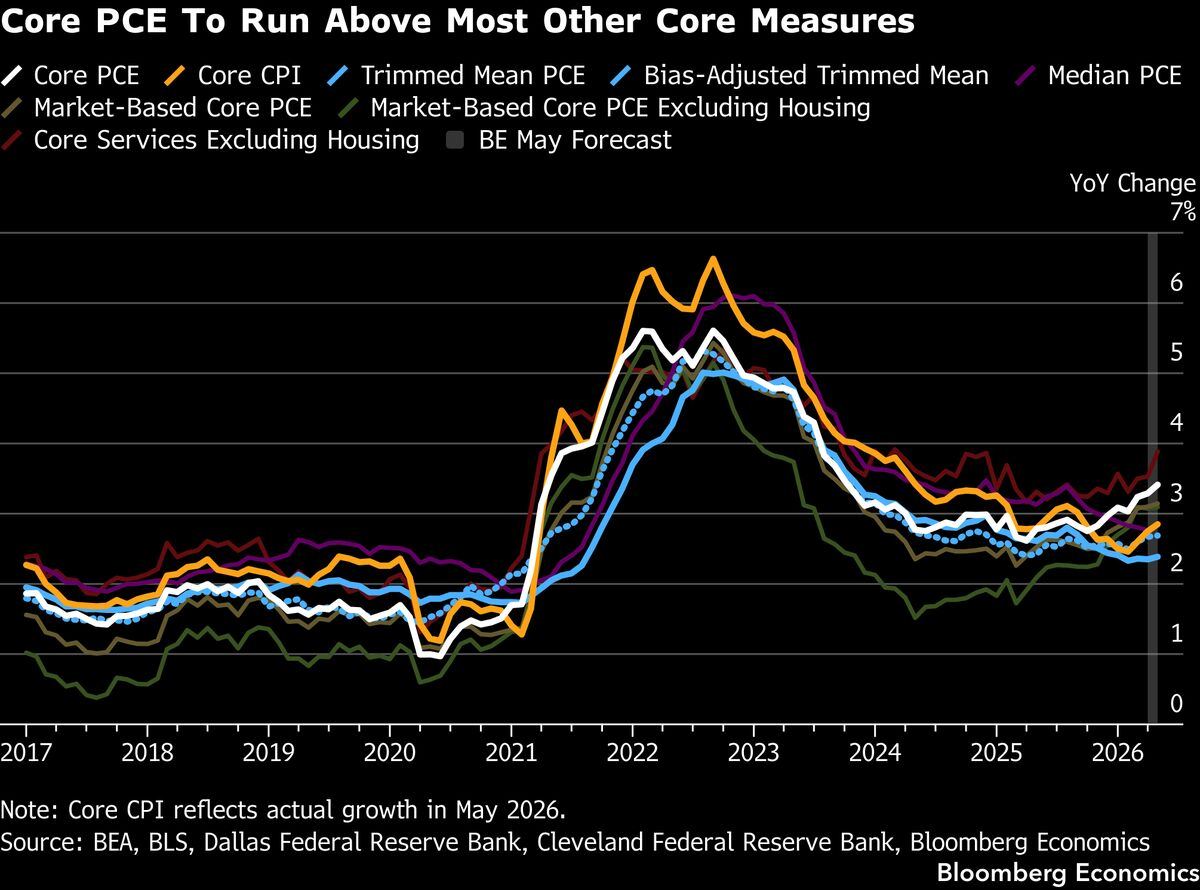
US PCE Thursday — the gate. BE estimates the May PCE deflator +0.48% MoM lifting YoY to 4.1% from 3.8%. Core PCE +0.35% MoM, YoY to 3.4% from 3.3% — hot vs the cooler CPI core read. Airfares, healthcare and portfolio-management fees account for the bulk of the monthly increase. A hot print reinforces the hawkish Warsh tone and pulls forward the October hike pricing. Source: Bloomberg Economics.
What is the plan this week?
The peace deal, although hiccups here and there, looks set to go ahead anyway as the Trump administration just wants to move ahead. The IRGC ends up financially better but commentaries are controlled so the US can off-ramp and move on. Oil prices have been heavy for almost two weeks already, looking like making a floor here, just slightly higher than pre-war as restocking flows balance off the over-hedges. The Geneva follow-up Friday was called off, Lebanon and Israel remain a flashpoint, and Hapag-Lloyd still says it takes three months for traffic to normalise after a deal. The macro tape has moved past the headline.
The bigger development is the Warsh Fed coming short-term super hawkish and the dollar moving accordingly. Markets are buying USD like there is no tomorrow. The Dollar Index broke to a new high since May 2025 just below 101.15, with 102.85 the next target at the 50% retracement and 200-day. The largest EURUSD selling in a while took the euro from above 1.1620 mid-week to below 1.1420 ahead of the weekend, a touch above the March year-low at 1.1410. USDJPY printed 161.80 the day after the FOMC, near the July 2024 high. USDCAD reached almost 1.418, the loonie down 4.15% since start of last month and the worst G10 performer. US exceptionalism flows are back in vengeance, the front-end backed up 13bp on the two-year, the biggest single-session move since April 2025. The market that was leaning into a Fed-cut tape is now positioned the other way, and the path of least resistance for the next few sessions is to keep adding to USD longs.
Smaller but more important is the AI development, still moving in hyper-speed. I really urge everyone to subscribe to newsletters tracking it. I personally read Rundown AI as there is massive progress daily. Apple's Tim Cook called rising memory costs a "100-year flood" and warned device prices will rise. Jensen Huang locked the SK Hynix supply for the next Vera Rubin chip architecture over a chicken-and-beer dinner. SpaceX kicked off calls for a $20 billion bond offering. Anthropic's Fable 5 was pulled at US government request on national security grounds while Chinese open-weights GLM 5.2 cracked the top of the frontend coding leaderboard. Stay long the buildout, stay nimble around the regulatory layer now upstream of the IPO calendar.
A relatively data-light week sits in front of us and it will all be about how much central banks are being priced for the next move. The Asia open lands on the China LPRs Monday, held for the 13th straight month at 3.00% one-year and 3.50% five-year. The interesting twist is that the PBOC has signalled a switch of its benchmark from the 7-day reverse repo to an overnight rate, which the market is reading as dovish framing of the next easing leg. DM flash composite PMIs across Japan, India, Korea, eurozone, France, Germany, UK and US fill Tuesday — the first read on whether the post-MOU sentiment lift caught the survey window. Singapore CPI Tuesday and Tokyo CPI Friday should both pick up on the Iran fuel pass-through. Australia CPI Wednesday is the test of whether fuel-tax rebates and the stronger Aussie pulled the May print back to 4.0% from 4.2% and how much of the next RBA move that erases. And then PCE Thursday, the most important print of the week.
The plan this week. A hot PCE reinforces the hawkish Warsh message, BE calls 4.1% headline and 3.4% core, well above the 2% target, with personal income and spending Thursday robust despite weak Michigan sentiment Friday. The Warsh Fed is trending in a very hawkish direction and the cost of that path will be higher unemployment later. Get into USD longs with the path of least resistance, probably low-yield currencies. The well-bashed currencies should do well over the summer even with a USD rally, INR and IDR come to mind with prohibitive carry to be short. Can CNH stall here or keeps rallying through, and will local USD hoarders stop the flow and start keeping USD again. The USD yield curve flattened massively, mainly the 2-year rates higher, are some of the Asia curves priced too much with oil tracking lower, and is the US pricing in enough. Long USDJPY held into MOF risk. USDCNH small short held with the trail stop on the 6.82 break. USD long against EUR and AUD the cleanest path-of-least-resistance trade. Tight stops, smaller size into PCE, ready to add on confirmation. Stay nimble.
What did I learn last week?
Mon Jun 15: China May retail sales -0.6% vs -0.2%e, the lowest since December 2022. China May industrial production +4.5% vs +4.4%e. BOJ raised target rate to 1.00% as expected, reiterated willingness to keep raising rates. US May industrial production +0.1% vs +0.3%e. June Empire Manufacturing 5.7 vs 13.5e, new orders 3.5 vs 22.7 prior, supply availability worst since June 2022. B-52 accident at Edwards killed eight crew. Roku acquired by Fox at $160/share in $22B deal.
Tue Jun 16: RBA held at 4.35% as expected. PBOC announced six new policies at Lujiazui Forum, including exploring yuan FX futures. US and Iran MOU allows Tehran to begin selling oil immediately per WSJ. Qatar restoring 50% LNG output in a month, 80% in two months. UK first country to sanction Russian shadow-fleet LNG vessels (27 ships). US May import prices +1.9% vs +1.0%e, YoY +6.7% vs +5.7%e. Treasury 20y auction at 4.927% vs 5.122% prior. Atlanta Fed cut Q2 GDPNow estimate from 3.29% to 2.83%. BMW cut 2026 auto EBIT margin outlook to 1-3% from 4-6%. Olin/Huntsman $13B all-stock merger of equals.
Wed Jun 17: FOMC held 3.50-3.75%, removed reference to additional rate adjustments, dramatically shorter statement. Warsh first press conference: inflation well ahead of 2% goal, forward guidance not well-suited, did not offer projections, introduced five new task forces, sees no reason to revisit the 2% goal. Iran-US MOU text finalised, both presidents signed. New Zealand Q1 GDP +0.8% QoQ, +1.5% YoY beating consensus. UK May CPI +0.2% MoM, +2.8% YoY vs +3.0%e cooler. Atlanta Fed raised Q2 GDPNow from 2.83% to 3.0%. US Pres Trump: It's alright the Fed held rates, whatever. US May pending home sales +3.8% vs +0.9%e. Apple CEO Cook: rising memory costs are a "100-year flood", will unavoidably raise device prices. CarMax beat Q1 EPS $1.31 vs $0.94e. Steel Dynamics guided Q2 EPS lower.
Thu Jun 18: SNB held at 0.00%. Czech CNB +25bp to 3.75%. BOE held at 3.75% (7-2 split per Marc Chandler). US initial jobless claims 226k vs 225ke, continuing 1.81M vs 1.79Me. BofA card spending +5.9% week-to-Jun 13. Saudi VLCCs reappeared outside Hormuz with ~6M barrels — repositioned, not new production yet. Accenture roughed up on bookings disappointment. Kroger missed EPS $1.56 vs $1.59e, lost investor confidence on promotional difficulties. Anthropic's Fable 5 pulled by US government on national security grounds. China open-weights GLM 5.2 cracked top of frontend coding leaderboard, only behind Fable 5 itself.
Fri Jun 19: S&P +0.9%, DJIA +0.7%, Nasdaq +2.4% for the week. US Juneteenth shortened week. DXY broke to 101.10 ahead of weekend, the high since May 2025. EUR settled below 1.15. USDJPY 161.80 day after FOMC, near July 2024 high. USDCNH 6.7980 from a mid-week 3-year low at 6.7540. USDCAD 1.418 the highest since April 2025, loonie -4.15% since start of last month. Sterling 1.3165 near year low 1.3160. AUDUSD 0.7025 off the 0.6990 low. Yield curve flattened — 2y +13bp largest since April 2025, 30y mortgage actually slipped.
What to look out for next week?
Sun Jun 21: Colombia presidential runoff — De La Espriella (right, market-friendly) vs Cepeda (left, continuation of Petro). Summer solstice. F1 Canadian GP.
Mon Jun 22: Canada CPI 0.8e — likely lifts YoY to 3.0% from 2.8%. China 1Y/5Y LPR held for 13th straight month at 3.00%/3.50%. Argentina unemployment. Macau visitor arrivals. Eurozone consumer confidence. Fed Waller delivers welcoming remarks at the international dollar conference. BDI Day of Industry Berlin with Merz, Pistorius. OAS General Assembly opens in Panama City. Fourth China International Supply Chain Expo Beijing.
Tue Jun 23: DM flash composite PMI day across Japan, India, Korea, eurozone, France, Germany, UK and US. Singapore CPI 1.9e from 1.8% on Iran-fuel cost pass-through. FedEx earnings — bellwether for global economic activity. Brazil BCB minutes. US congressional primaries Maryland/New York/Utah. Mexico activity, retail sales. Argentina GDP. Barclays-CEPR Monetary Policy Forum London. MSCI annual market-classification review — South Korea watchlist for DM status, Indonesia downgrade question. Jane Street appeal at India's Securities Appellate Tribunal.
Wed Jun 24: Australia CPI Wed — 4.0e from 4.2%, fuel-tax rebates trim 60bp. Bank of Thailand likely holds at 1.00%. Germany Ifo. Sweden Riksbank minutes. Mexico bi-weekly CPI. Russia IP. US current account, new home sales 645k. Micron earnings the memory-chip read after Apple's 100-year-flood quote. Fed Wall Street bank stress test results. RBA Deputy Hauser at the Economic Society of Australia, BOJ Deputy Himino at Shinkin Conference. Bank of Canada policy deliberations summary. GSMA MWC Shanghai opens. APEC Tourism Ministerial Meeting Macau.
Thu Jun 25: US PCE — the gate. BE estimates 0.5% MoM headline / 0.4% core, lifting YoY to 4.1% / 3.4%. US GDP final 1Q 1.6%, durable goods -2.0% headline / +0.5% ex-trans, claims 222k. Mexico Banxico unanimous hold 6.50%. Australia unemployment 4.6%. Japan machine tool orders. Spain GDP. Chicago Fed Goolsbee, NY Fed Williams. ECB Lane at IEA World Congress Belgrade. BOJ Tamura Hyogo.
Fri Jun 26: Tokyo CPI 1.7e from 1.3% on base effects — keeps BOJ on the December +25 path. Italy economic sentiment. Singapore industrial production. US advance economic indicators, Michigan sentiment final 49.5e. ECB Vujcic Lisbon. Minneapolis Fed Kashkari Aspen Ideas Festival. 25th BIS Annual Conference Basel focuses on macro-financial stability in a fragmented global economy. EU energy ministers meet on European grids package.
All week: The week of US PCE post-Warsh, with Tuesday flash PMI day and Thursday the data peak. Summer Davos in Dalian (China) through Jun 25. London Climate Action Week through Jun 28. US Open golf at Shinnecock Hills closes Sunday. FIFA World Cup continues through July 19. Amazon Prime Day opens Tuesday through Jun 26. The full attention on Warsh's communication style and what PCE does to the pricing of the October hike.
Beyond next week
Jun 25: US PCE the gate — the cleanest validation or rejection of Warsh's hawkish framing.
Jun 30: Quarter-end. SpaceX index-inclusion debate continues. BIS Annual Report.
Early Jul: NATO summit. ECB July meeting. BOC July decision after the May CPI Tuesday.
Mid Jul: Earnings season opens — AI capex, consumer stress, memory-chip pass-through.
Jul 19: FIFA World Cup final in the US.
Jul 28-29: FOMC — futures price ~40% odds of an October hike already after Warsh.
Late Jul: Anthropic IPO rumoured after the Fable 5 takedown noise settles. OpenAI S-1 already filed confidentially.
Aug: UN funding cliff — Guterres flags mid-August financial collapse on current trajectory.
Regimes
Warsh hawkish hold becomes the regime — front-end repricing, the dollar bid, EUR selling pressure. First FOMC removed forward guidance. Nine of eighteen dot-plotters baked in at least one hike. Two-year +13bp largest since April 2025. DXY broke to 101.10. The October hike pricing is the live tape now. evolved, week 1 under Warsh
G7 bear flattener accelerates, the curve catch-up at the front while the long end catches an oil bid. Pay US short end on Warsh-hawkish. 30-year mortgage actually slipped — first time in several weeks. The 2s-10s flattens from both ends as oil pulls the long end and Warsh pulls the front. Same trade across UK, JGB, EU rates. evolved, week 7
European structural rebalance pauses on the dollar bid, the long-EUR sleeve stays stopped. EUR through 1.16 to below 1.14 in the largest selling in a while. Year low 1.1410 set in March within reach. ECB swap pricing still leans toward another hike, the September follow-up the deeper question. The cyclical USD bid dominates the structural rebalance. evolved, week 5
AI capex regime moves to the regulatory-envelope test. Anthropic Fable 5 pulled at US government request. Apple Cook calls memory cost a 100-year flood. NVIDIA-SK Hynix Vera Rubin supply locked over chicken and beer. SpaceX kicks off $20B bond. The export-control layer is now upstream of the IPO calendar. evolved, week 9
Asia FX divergence sharpens — CNH strongest, the rest of Asia in the dollar bid. CNH +3.20%/3.40% YTD offshore/onshore, the strongest in Asia. SGD second a distant 0.2%. CNH hit 6.7540 mid-week, reversed to 6.7980 on the broad dollar bid. PBOC fix walked another 35 weeks of mostly lower. The local USD hoarders question is the swing factor. evolved, week 4
Shifts (if → then)
If PCE prints hot Thursday at 4.1%/3.4% as BE forecasts → October hike pricing confirms, DXY extends to 102.85, bear flattener accelerates, EUR breaks 1.1410 year low. new
If PCE misses to the downside → curve eases, bear flattener pauses, USD gives back, gold rallies, EM Asia FX can rally over the summer. new
If USDJPY breaks 162 ahead of MOF → intervention returns with potential US Treasury support this time, the yen carry trades unwind, JPY vol spike continues. new
If Aussie CPI Wednesday surprises hot or Aussie jobs Thursday strong → AUDNZD shorts under pressure, RBA August hike pricing returns, the wider Asian curve repriced. new
If China retail sales weakness persists into next print → CNH consolidation continues, the AI-hardware import surge thesis is the only counter, PBOC may pause appreciation walk. carried
If Anthropic IPO timing slips on the Fable 5 noise → the AI-tape leadership rotates from frontier model maker to capex supplier — memory chips, data centre infra, power generation. NVIDIA-SK Hynix the playbook. new
If MOVE keeps rising while FX vol stays pinned → the gap closes the wrong way, FX vol catches up, the VAR shock arrives. carried
Tails
Bear flattener accelerates into forced deleveraging → positioning wrong-footed across G7 rates books, the curve shifts violently. The most painful repricing scenario, now with Warsh as the catalyst. week 3, evolved
Hormuz physical reopening lags the MOU headline → Hapag-Lloyd still says three months minimum to normalise. Lebanon-Israel airstrikes a flashpoint. Saudi VLCCs repositioning rather than producing. week 12
JPY intervention returns with US Treasury cooperation this time → BOJ has raised to 1%, the US side may finally play ball. Spec short JPY positions largest since July 2024, vol at 8.1% highest since May 7. week 3, evolved
Warsh forced into pragmatism → a hot PCE confirms the hawkish hold, a cool PCE forces a softening of tone. Either way the volatility of short-term rates expands under the new chair. week 9, evolved
AI capex bubble pops → SpaceX now publicly tradeable and adding $20B in bonds. The regulatory envelope is widening from chips to model releases. The Fable 5 takedown is the first model-level export-control event. The risk is the second-derivative — when does regulatory drag overwhelm capex momentum. week 3, evolved
Wealth destruction at top 10% kills the consumer engine → BofA data shows the gap in total card spending between higher- and lower-income households narrowing in recent days. The top 10% holds the spending channel. Equity drawdown into PCE breaks the wealth-effect. week 3
UN funding cliff in August → the 1945 architecture fragments visibly. Guterres flags mid-August financial collapse on current trajectory. week 5, carried
Manic Monday
Asia opens with the Colombian runoff result already in. China LPRs first thing Singapore morning, held for the 13th month at 3.00% and 3.50% as expected. The eurozone consumer confidence print runs through the London afternoon. Canada CPI 8:30pm Singapore likely lifts YoY to 3.00% from 2.80% on rising gasoline. Quiet day overall as the market positions into the Tuesday flash PMI dump.
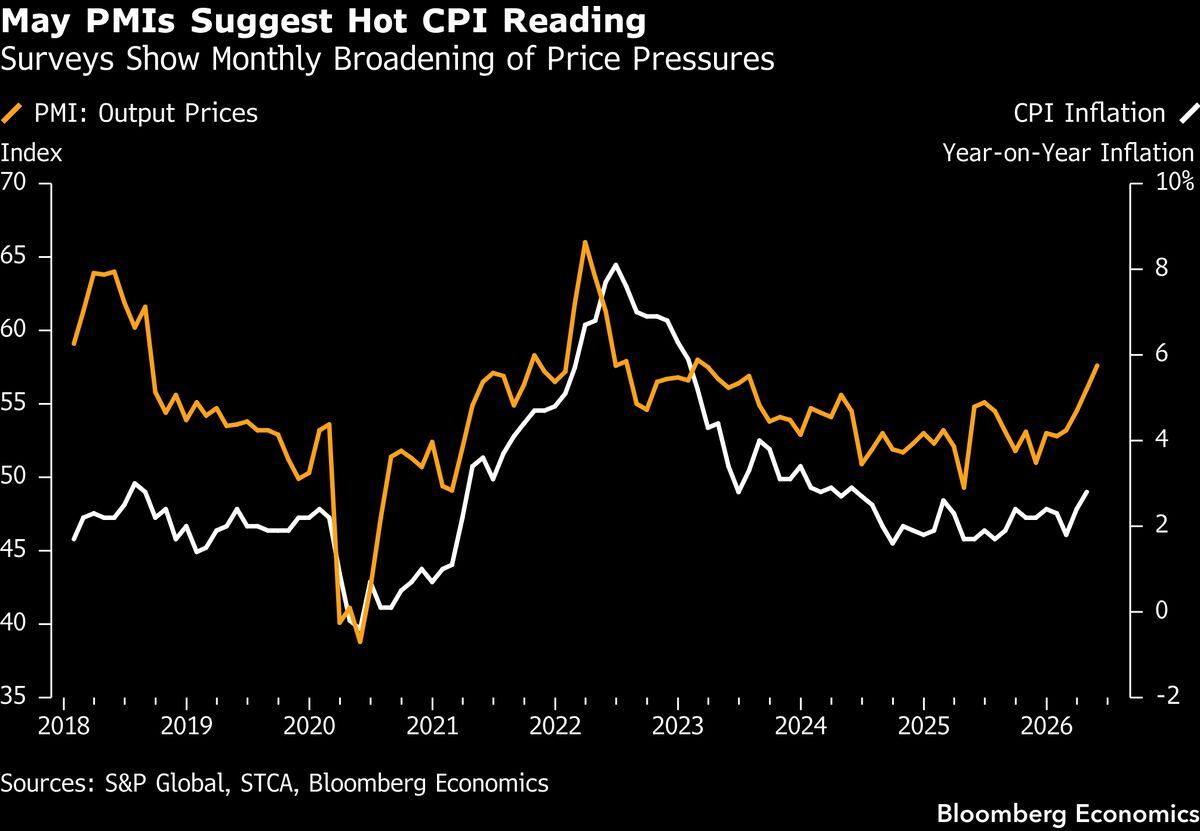
Canada CPI Monday — likely +0.8% MoM unadjusted, pushing YoY to 3.0% from 2.8%. Rising gasoline drove the headline. BE's reasoning chart — May PMIs suggest a hot CPI reading, with surveys showing monthly broadening of price pressures. PMI output prices have led CPI inflation higher historically. BoC stays on the sidelines into year-end. Source: Bloomberg Economics.
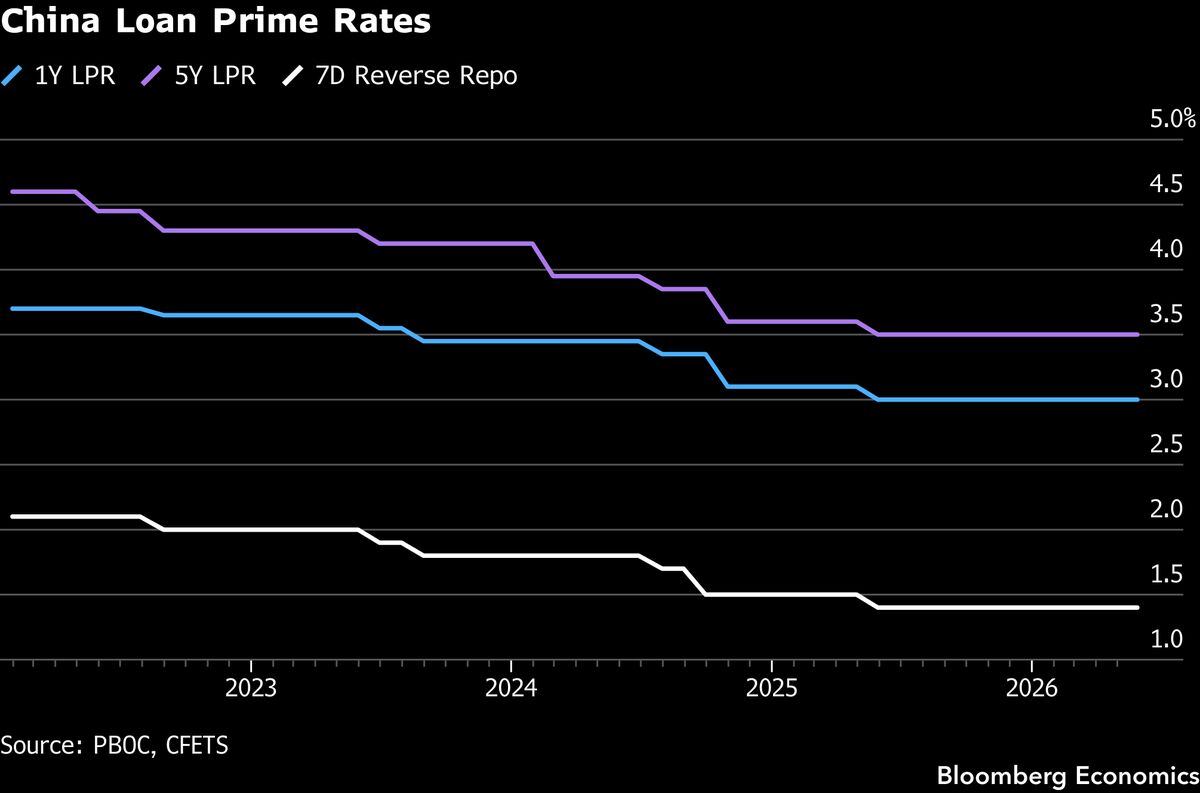
China LPRs Monday — held for the 13th straight month at 3.00% one-year and 3.50% five-year. PBOC policy rate steady since the 10bp cut in May 2025. The 7-day reverse repo has stepped down to 1.25%. The interesting twist: the PBOC has been signalling a switch of the benchmark from the 7-day to an overnight rate, which the market is reading as a dovish framing of the next easing. The US-Iran MOU eases the drag from geopolitical uncertainty; strong exports and AI boom buffer reduce the urgency to step up support. Source: Bloomberg Economics.
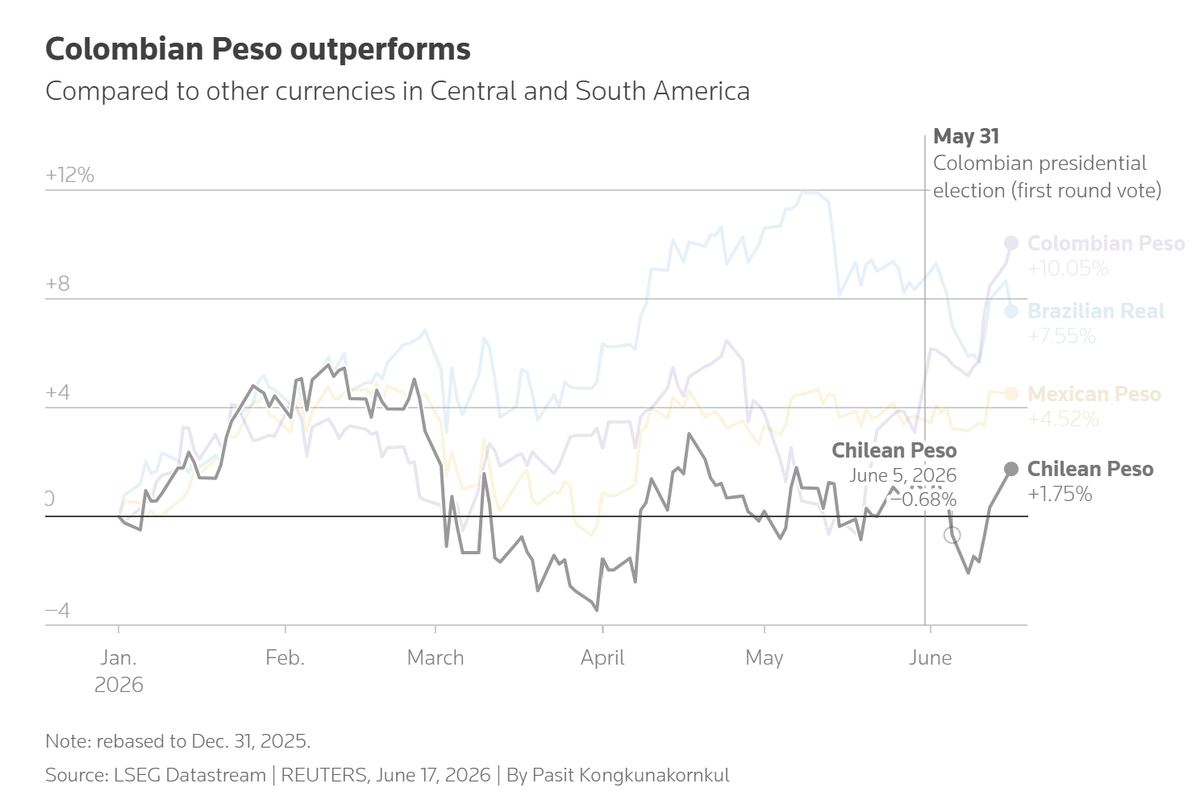
Colombian peso the standout LATAM trade so far this year — up +10% rebased to year-end 2025, beating the Brazilian real, Mexican peso and Chilean peso. The first-round vote in May was the inflection point. A Cepeda win Sunday would unwind some of it; a de la Espriella confirmation would extend it. Either way the moves get larger after Sunday's runoff result. Source: Reuters.
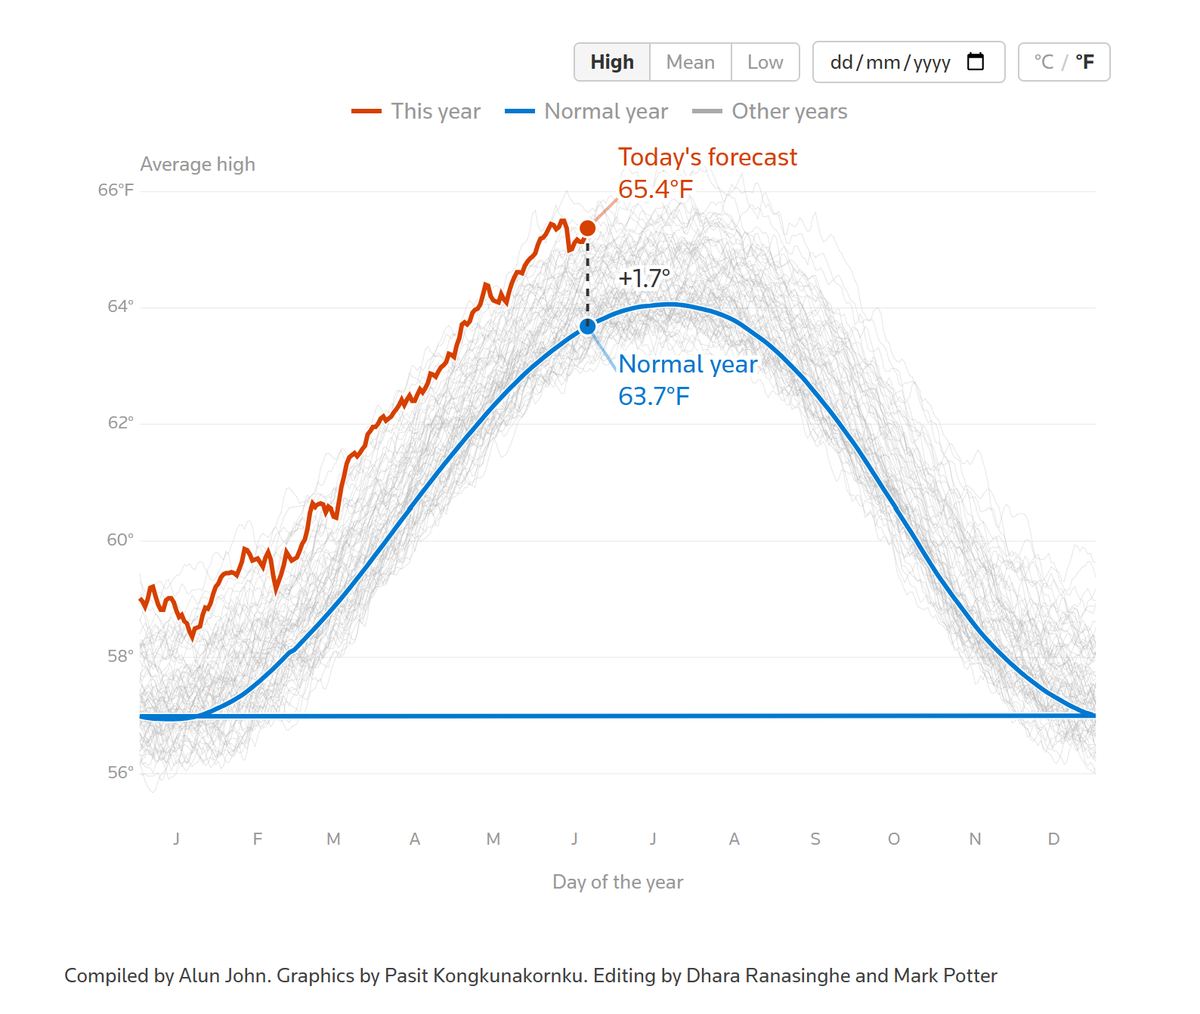
London Climate Action Week the largest ever — 75,000+ participants across 1,000+ events through June 28. Policymakers, financiers and corporate leaders focus on mobilising private capital for the transition. The debate comes as developed economies cut aid while boosting defence spending. A forecast heatwave overlays the politics. Attendees keep one eye on COP31 in Turkey in November. Source: Reuters.
Turnaround Tuesday
Asia opens with Japan flash PMI, then Singapore CPI at 1pm Singapore. Eurozone, France, Germany, UK flash composite PMIs through the London afternoon Singapore evening. US flash PMI in the late Singapore night. FedEx earnings post-close New York the bellwether on the parcel volume read. Brazil BCB minutes pre-Open New York. The MSCI annual market-classification review is the EM positioning event — South Korea for the DM watchlist, Indonesia for the potential downgrade. Amazon Prime Day opens.
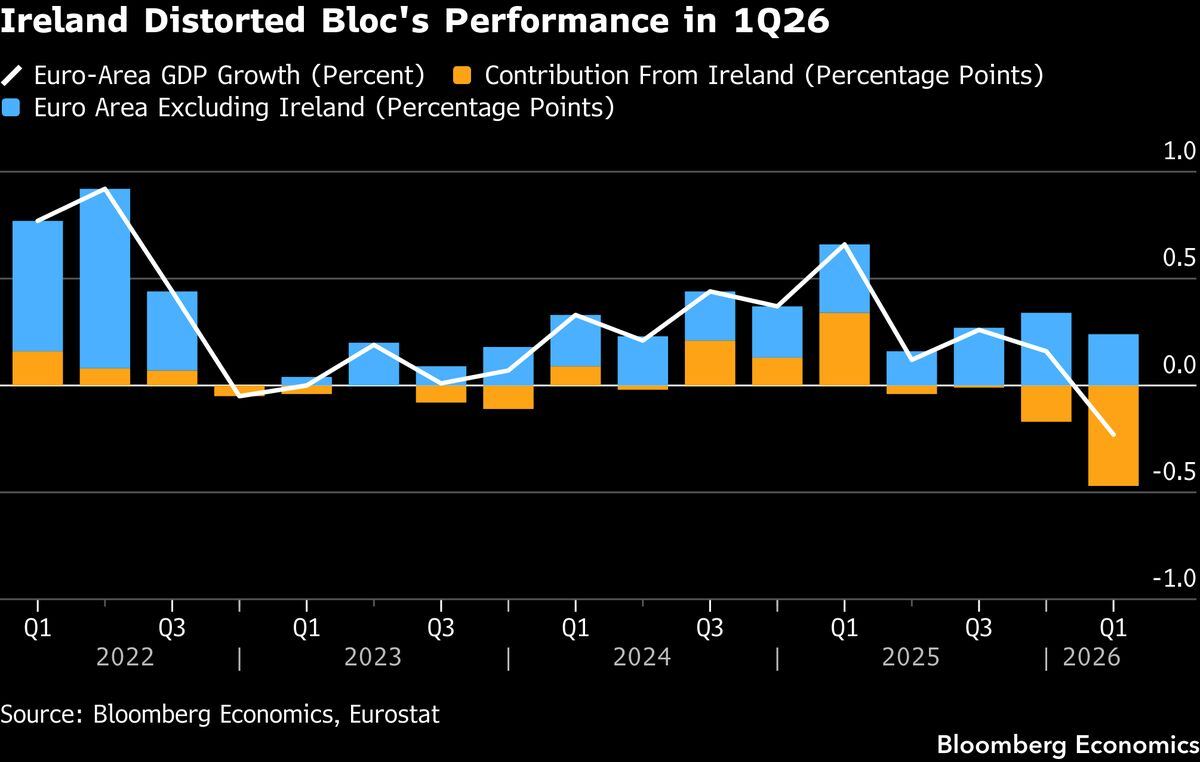
Euro-area flash composite PMI Tuesday — still sub-50. May composite fell to 48.5, the two-month average of 48.7 sits well below the 51.3 January-March print. The June survey straddles the US-Iran deal announcement and may catch a sentiment lift even before the energy relief feeds through. Ireland distorted the bloc's performance in 1Q26 — stripped out, Euro-area GDP grew 0.2% in 1Q. BE forecasts 0.1% in 2Q ex-Ireland. ECB swap pricing still leans toward another hike, ~80% in by year-end. Source: Bloomberg Economics.
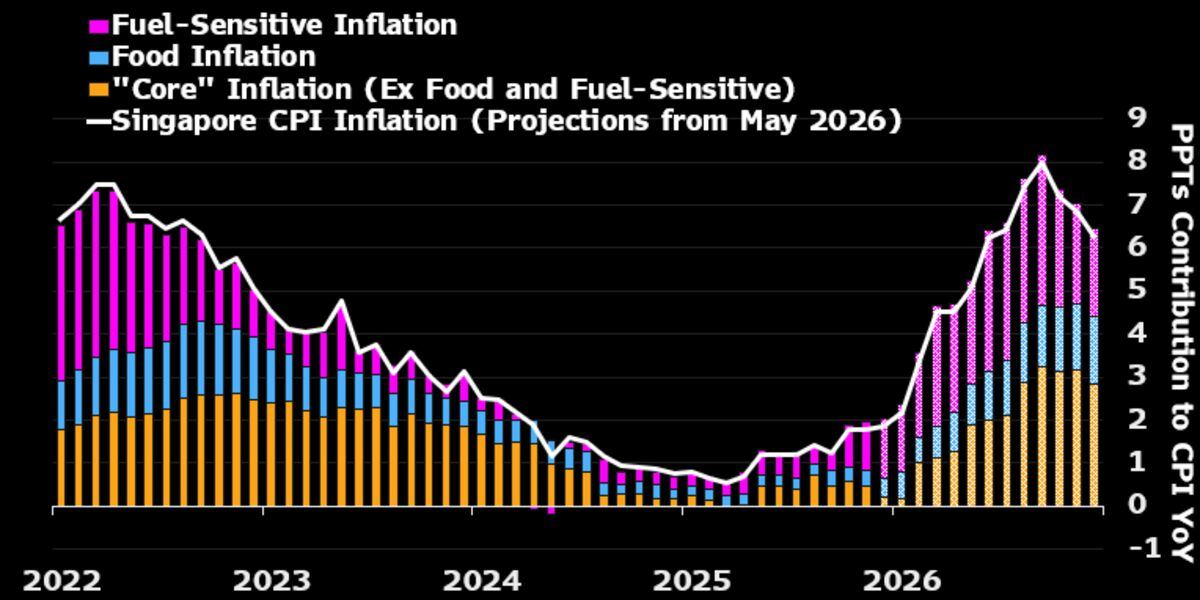
Singapore CPI Tuesday — likely +1.9% YoY from 1.8% as higher fuel costs from the Iran war lifted import prices. Even with the US-Iran MOU, the city-state expects inflation to climb further as the supply-chain spillovers ripple through. The MAS exchange-rate tightening continues to absorb the shock. Electricity rates lag fuel by a quarter, so the April-June hit is partial. Source: Bloomberg Economics.
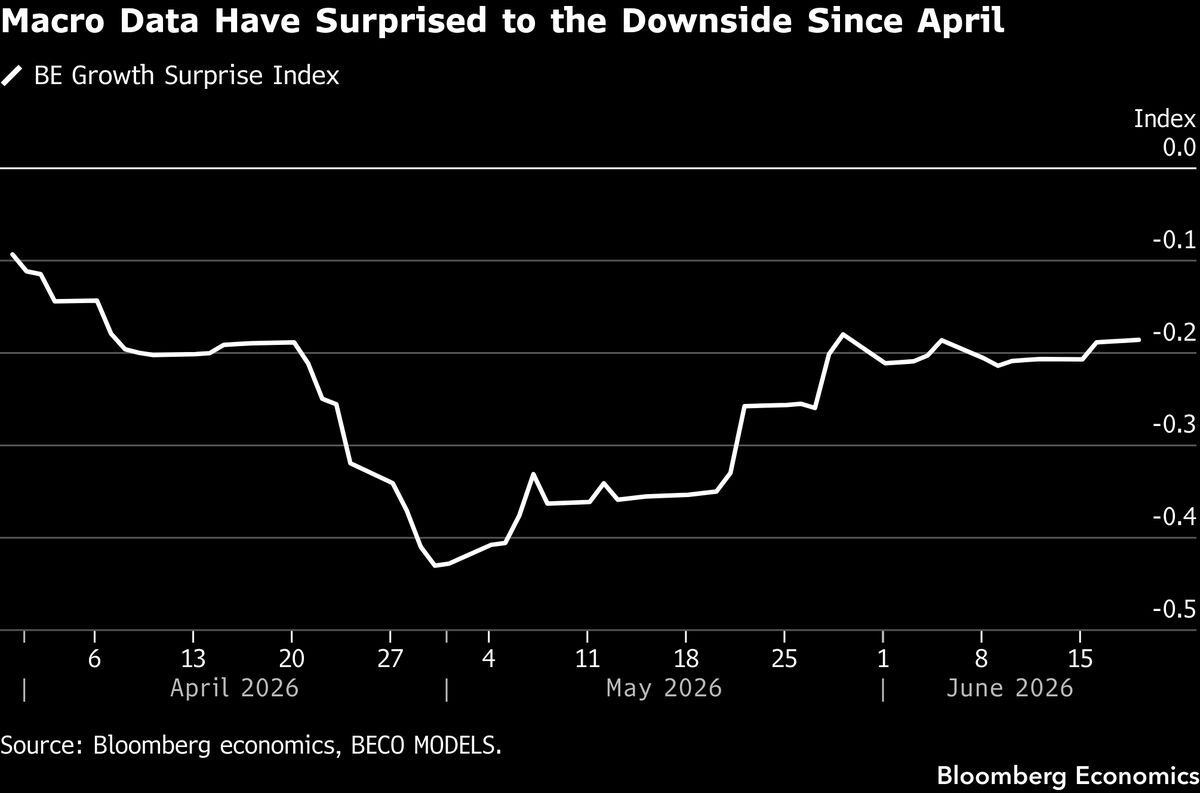
Eurozone macro data have surprised to the downside since April. BE Growth Surprise Index. PMI surveys may have been conducted around the time of the US-Iran interim agreement, so the signal will be blurred. The German Ifo, French and Italian confidence indicators all expected this week, with the durability of the energy relief the swing factor for second-half recovery. ECB hike priced for September. Source: Bloomberg Economics.
Waiting Wednesday
Australia CPI 9:30am Singapore is the Asia anchor — expected to ease to 4.0% from 4.2% on fuel-tax rebates. Thailand BOT 3pm Singapore likely holds at 1.00%. Germany Ifo in the London afternoon Singapore evening. Sweden Riksbank minutes the same window. US new home sales 10am New York. Micron earnings post-close New York the memory-chip read on Apple's 100-year flood comment. The Fed unveils the Wall Street bank stress test results — the regulatory backdrop to Warsh's task forces. Same day, the credit cycle continues to print payouts to PE owners as the loan market stays hot.
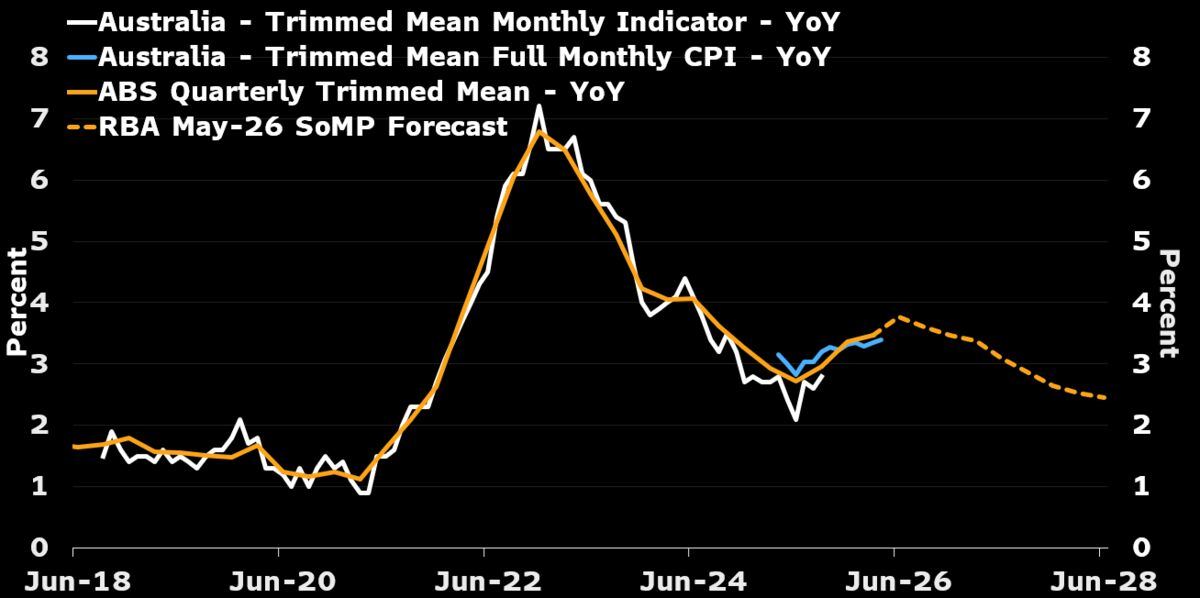
Australia CPI Wednesday — likely eased to 4.0% YoY from 4.2%. Fuel-tax rebates and a stronger Aussie have pushed pump prices back toward pre-war levels. The pullback through April-May could trim 60bp off inflation, with another 30bp likely in June. Trimmed mean still at 3.4%. RBA next meets in August after the June and 2Q prints supersede this read. Source: Bloomberg Economics.
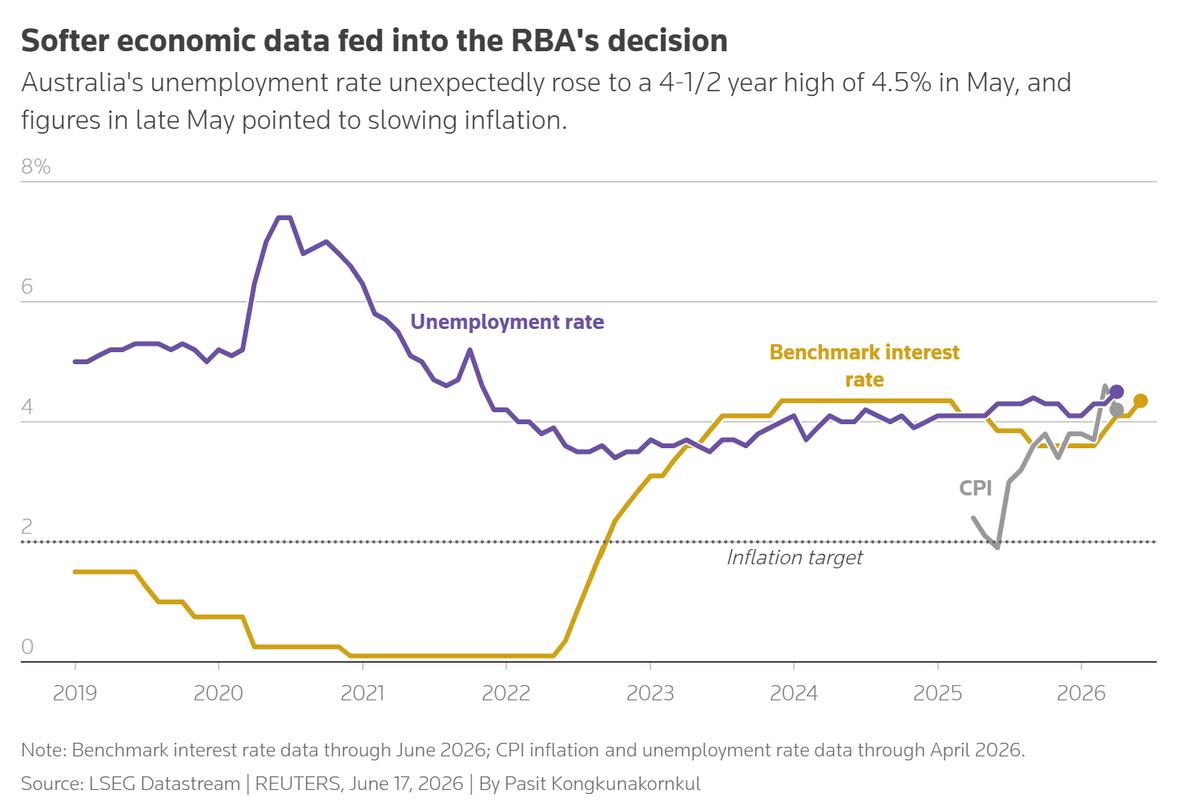
Softer Australian data fed into the RBA's hold. Unemployment unexpectedly rose to a 4½-year high of 4.5% in May. Inflation moderated. The RBA held at 4.35% Tuesday, the highest in developed markets, but flagged that another hike may still be needed. Swap pricing — one-in-four chance of an August hike, two-in-three by year-end. Wednesday CPI and Thursday jobs the next test. Source: Reuters.
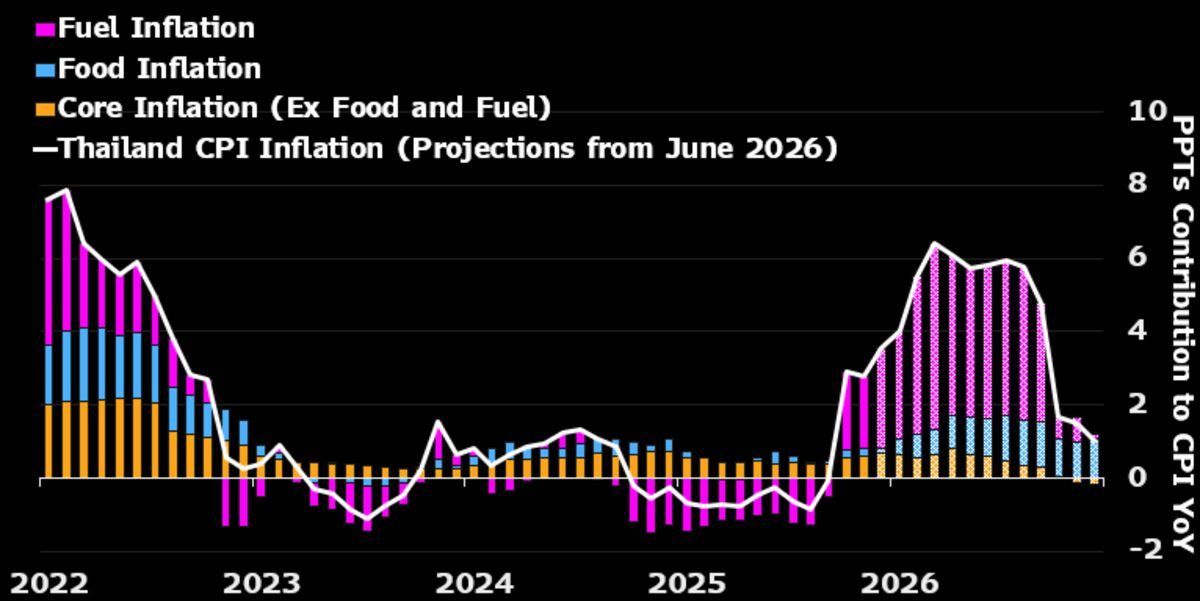
Thailand BOT Wednesday — likely holds at 1.00%. Inflation still inside the 1-3% target band, fuel inflation moderating as oil prices come off. BOT signalled early it would look through the supply shock for as long as possible. Growth faces multiple challenges — US trade concessions, a shrinking workforce, high household debt, China slowdown weighing on tourism. Source: Bloomberg Economics.
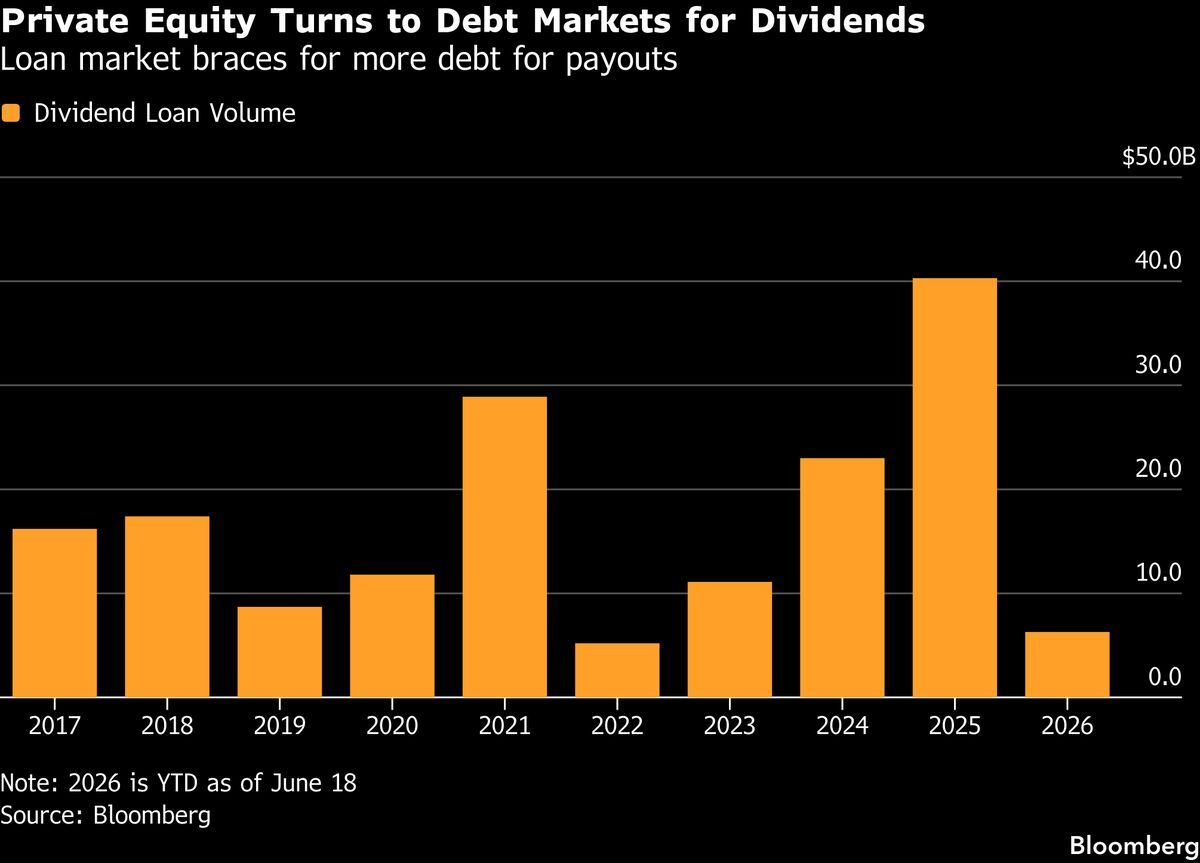
Private equity is tapping a hot loan market to pay itself. Over the last four weeks, ten borrowers launched more than $3.5 billion of leveraged loans and junk bonds to fund distributions for their owners — half of this year's entire dividend recap volume. Blackstone and Warburg Pincus piled more debt onto IntraFi for the seventh time in three years. With credit spreads near record tights, sponsors are eager to return capital before year-end. Investors clamour for any debt offering a floating rate as the Fed turns hawkish. Source: Bloomberg Credit Weekly.
TP Thursday
Australia jobs report 9:30am Singapore — expected +25k jobs after the surprise -18.6k April slump, unemployment up to 4.6%. PCE drops at 8:30pm Singapore. US GDP final 1Q 1.6%, durable goods -2.0% headline, jobless claims 222k all in the same release block. Mexico Banxico the late Singapore night, unanimous hold expected at 6.50%. The day to take profit on the bear-flattener trade ahead of Friday. A hot PCE confirms the Warsh hawkish hold and pulls forward the October hike pricing. The OECD baseline inflation picture pairs directly with this print — and the El Niño precipitation pattern reinforces the same channel through the slow food and energy spillover.
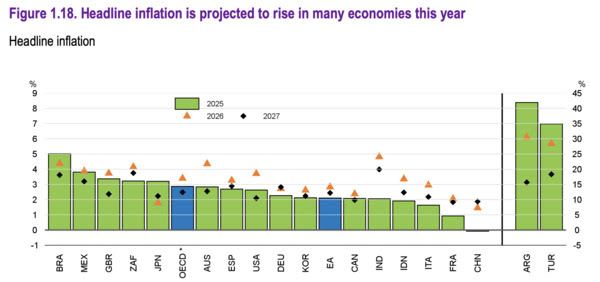
OECD headline inflation forecast paired with the PCE read. US inflation forecast to climb to 3.7% from 2.6% in 2025. India one of the sharpest spikes, projected from 2.1% to 4.8% (Middle East supplies ~55% of crude imports). Eurozone average 2.8% this year. The OECD baseline assumes Gulf disruptions ease from Q3 2026 onward; inflation moderates again in 2027 as commodity prices stabilise. The Iran shock and the structural inflation picture meet at this print. Source: OECD via Visual Capitalist.
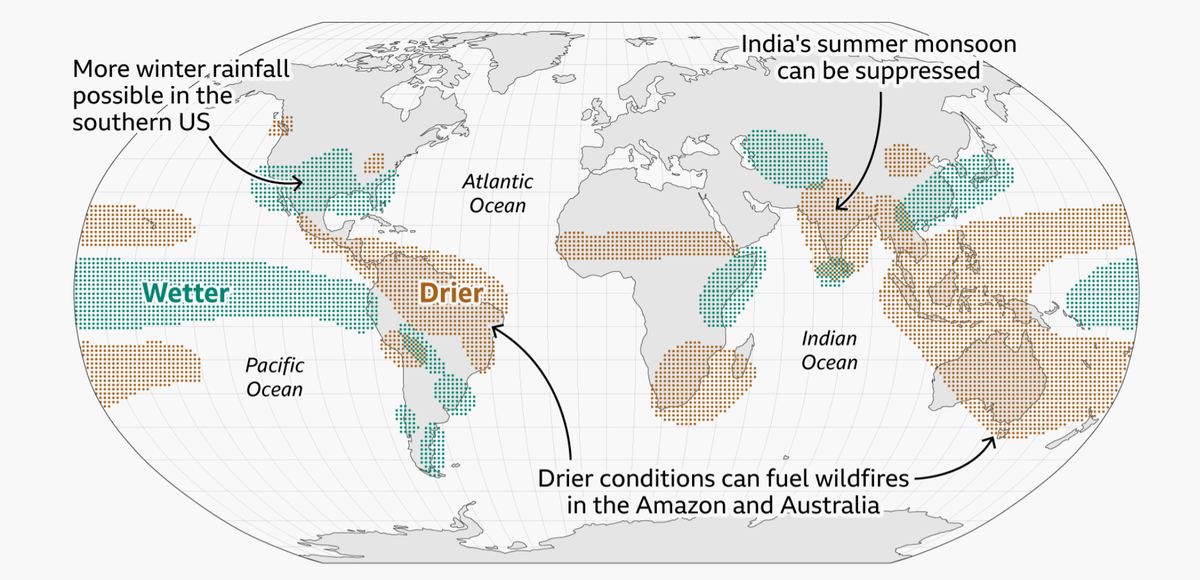
El Niño precipitation pattern — paired with the inflation print. More winter rain expected in the southern US. India's summer monsoon can be suppressed. Wetter in the central Pacific, drier in the western Pacific and South America. Wildfire risk rises in the Amazon and Australia. The slow inflation channel under the geopolitical headlines — read alongside the PCE chart, the OECD outlook, and the SST anomaly in the scene setter. Source: NOAA / BBC.
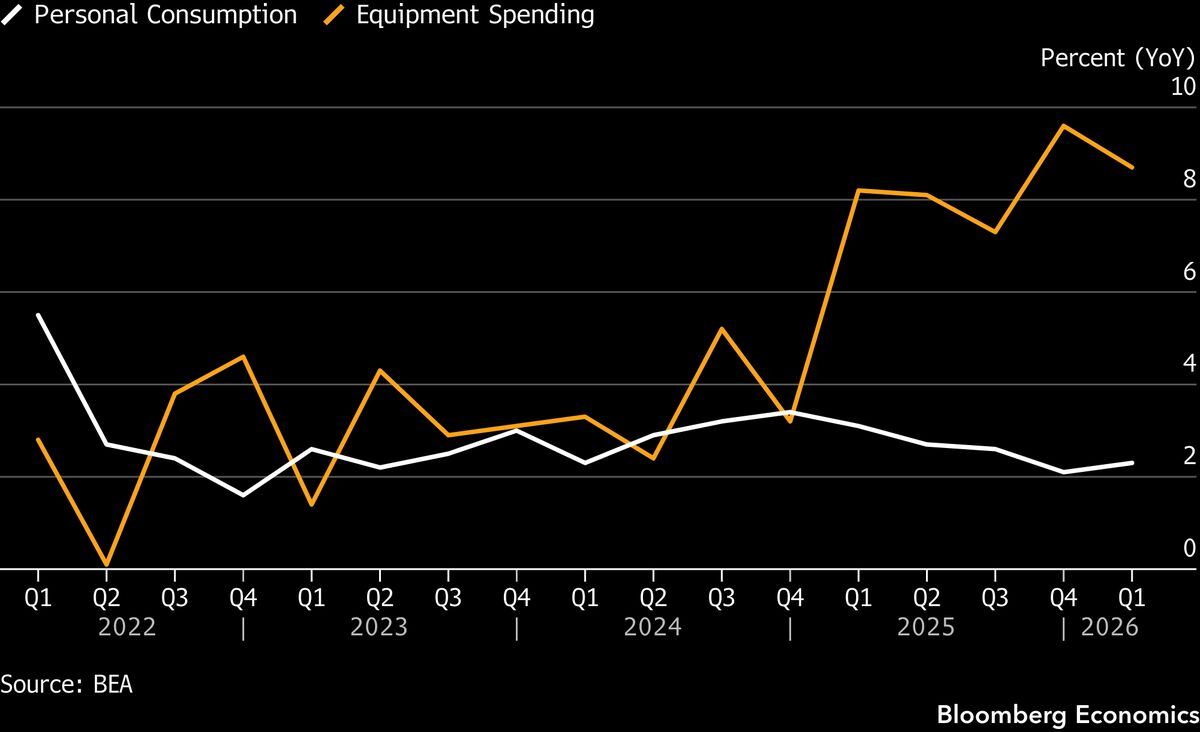
US GDP Thursday — final 1Q estimate likely +1.6% QoQ annualised. Personal consumption slowed to 1.4% annualised but Equipment Spending surged to roughly 8% YoY, the BEA chart shows the divergence — business investment outpacing consumer spending and AI infrastructure pulling the durable goods print. The 2Q rebound likely above 2% supported by elevated tax refunds and positive wealth effects. Source: Bloomberg Economics.
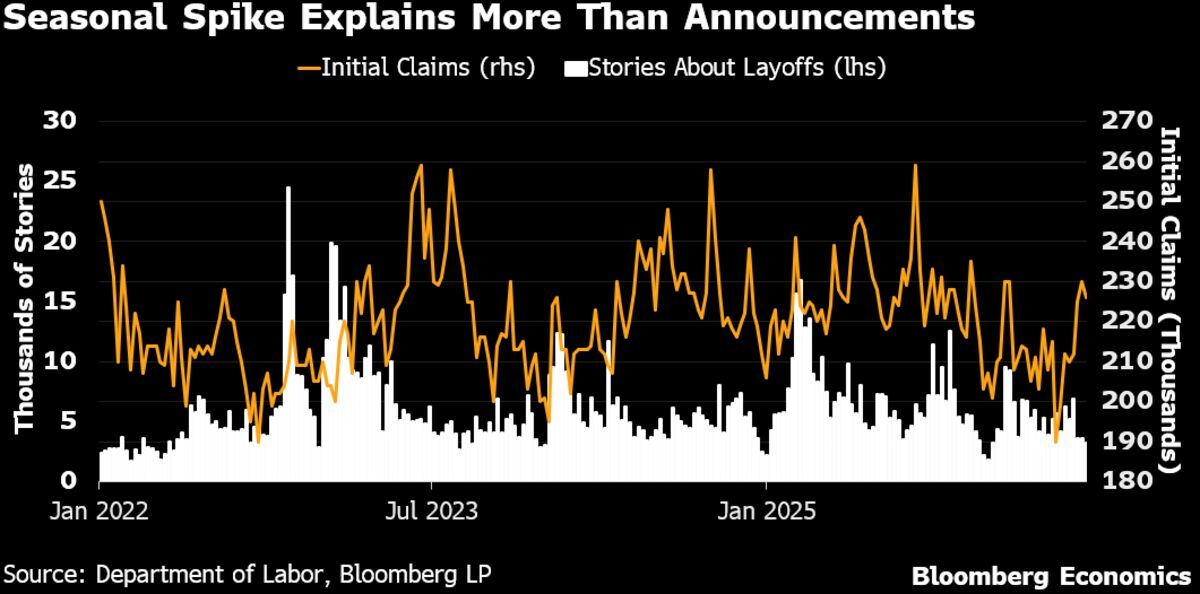
US initial jobless claims Thursday — likely fell -4k to 222k. Volatility is typical through summer as imperfect seasonal-adjustment processes, annual factory retooling and hiring plans dovetail. The BE chart highlights the seasonal spike explains more of the recent uptick than layoff announcements. Continuing claims also likely fell. Source: Bloomberg Economics.
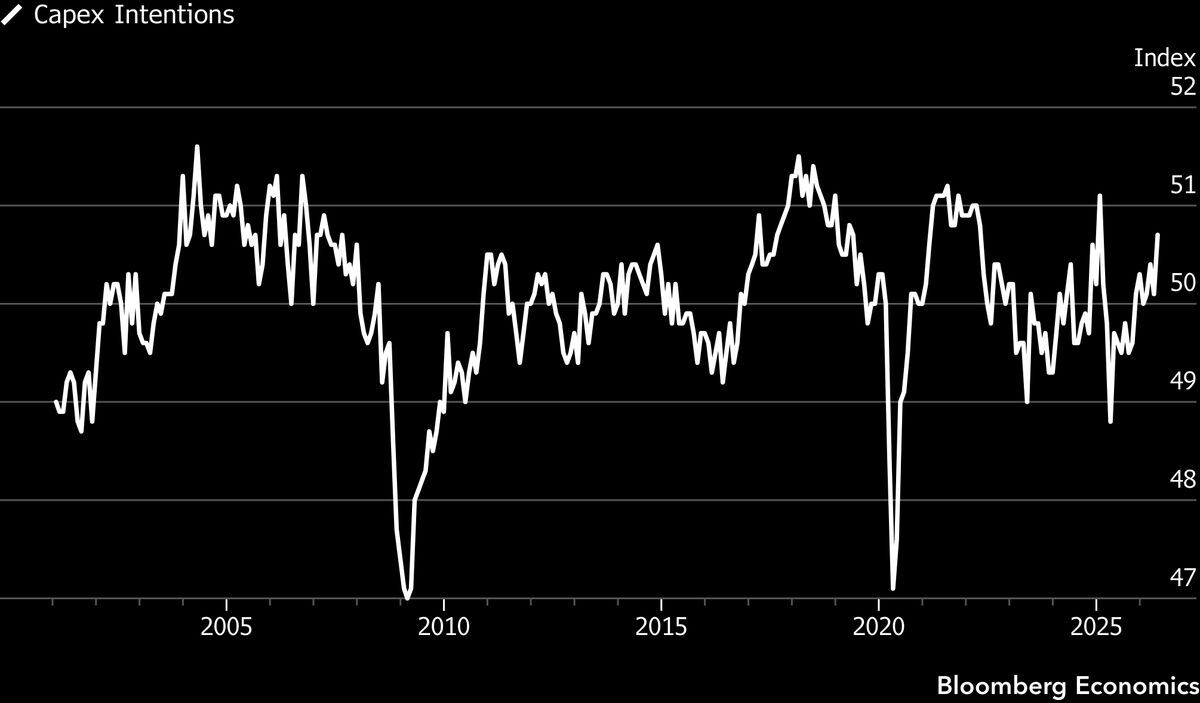
US durable goods Thursday — likely -2.0% headline after Boeing received just 27 aircraft orders in May from 136 prior. Ex-transport +0.5%. The BE Capex Intentions index is rising again — capex intentions strengthen across regional Fed surveys with business investment the bright spot driven by AI, data centres and digital infrastructure. Source: Bloomberg Economics.
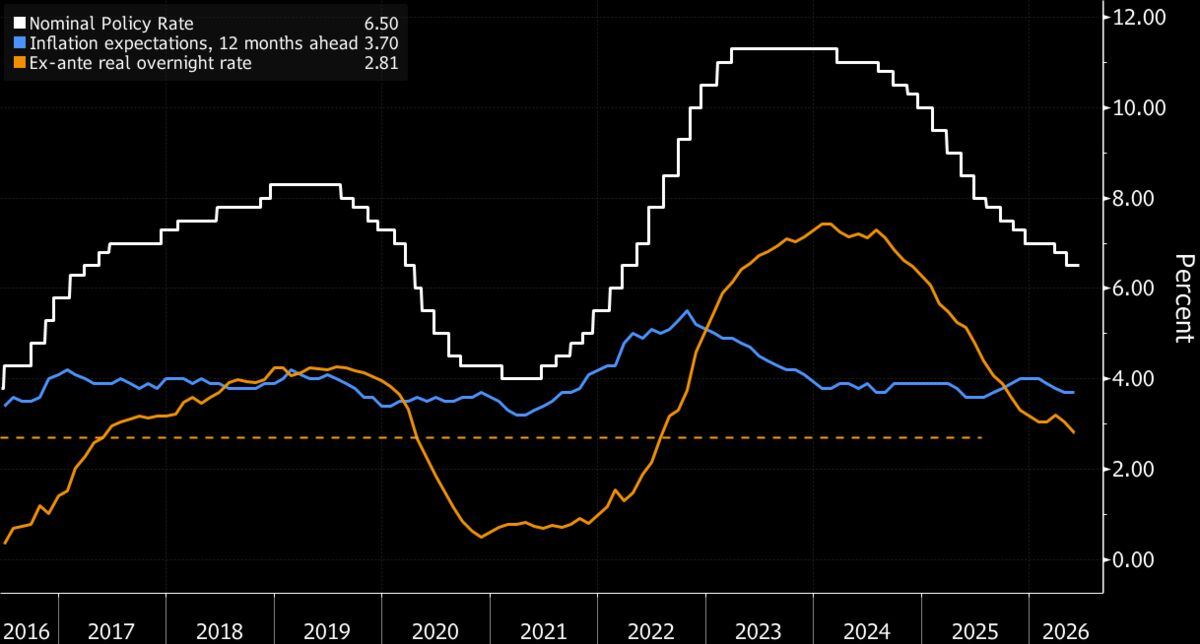
Mexico Banxico Thursday — unanimous hold at 6.50%. Forward guidance likely signals policymakers waiting for inflation to consolidate its downtrend before resuming cuts. Activity below potential, output gap wider than policymakers anticipated. Adjusted for one-year inflation expectations (3.7%) the ex-ante real overnight rate is close to 2.8% — close to neutral. Source: Bloomberg Economics.
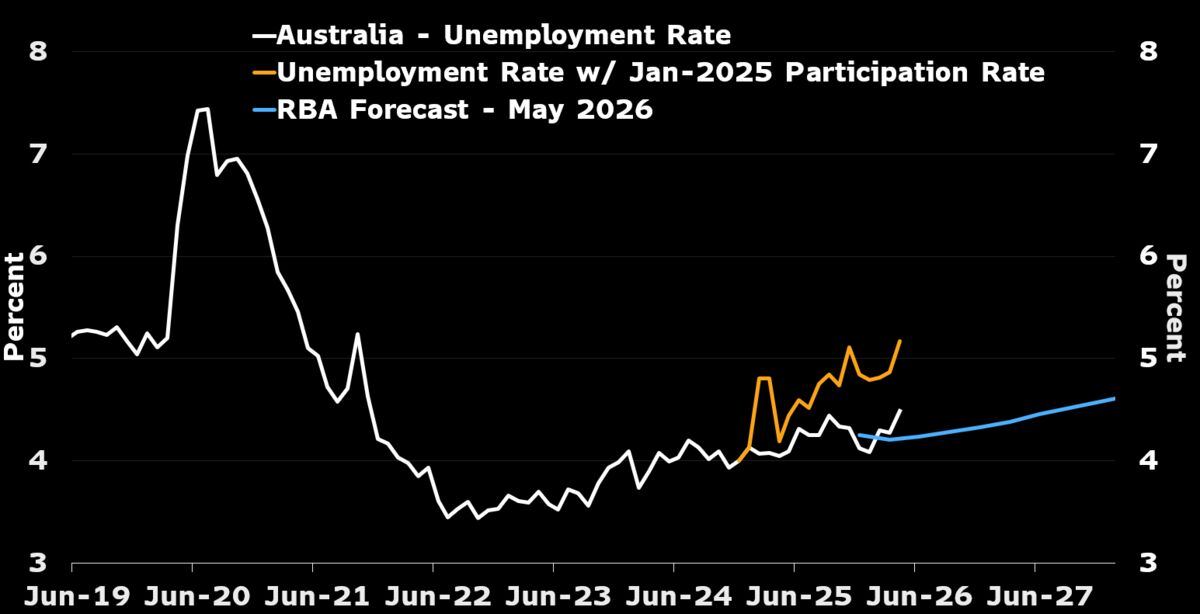
Australia labour market Thursday — likely back to job growth with a higher unemployment rate. BE expects +25k jobs after the surprise -18.6k April slump. Unemployment likely rose to 4.6%, with labour-supply growth exceeding new hiring. Job growth slowed through 2025 after strong 2024 gains. The Iran-war confidence shock should continue to slow hiring into 2026. Source: Bloomberg Economics.
Friday Fade
Tokyo CPI 7:30am Singapore — likely pickup on base effects from May's temporary water-charge waiver and gasoline-cap rollback. Core ex-fresh food 1.7% from 1.3%. Italy sentiment through London morning. US Michigan sentiment final at 10am New York. Minneapolis Fed Kashkari at Aspen Ideas Festival. The 25th BIS Annual Conference in Basel focused on macro-financial stability in a fragmented global economy. EU energy ministers meet on the European grids package. The week winds down into the BIS theme.
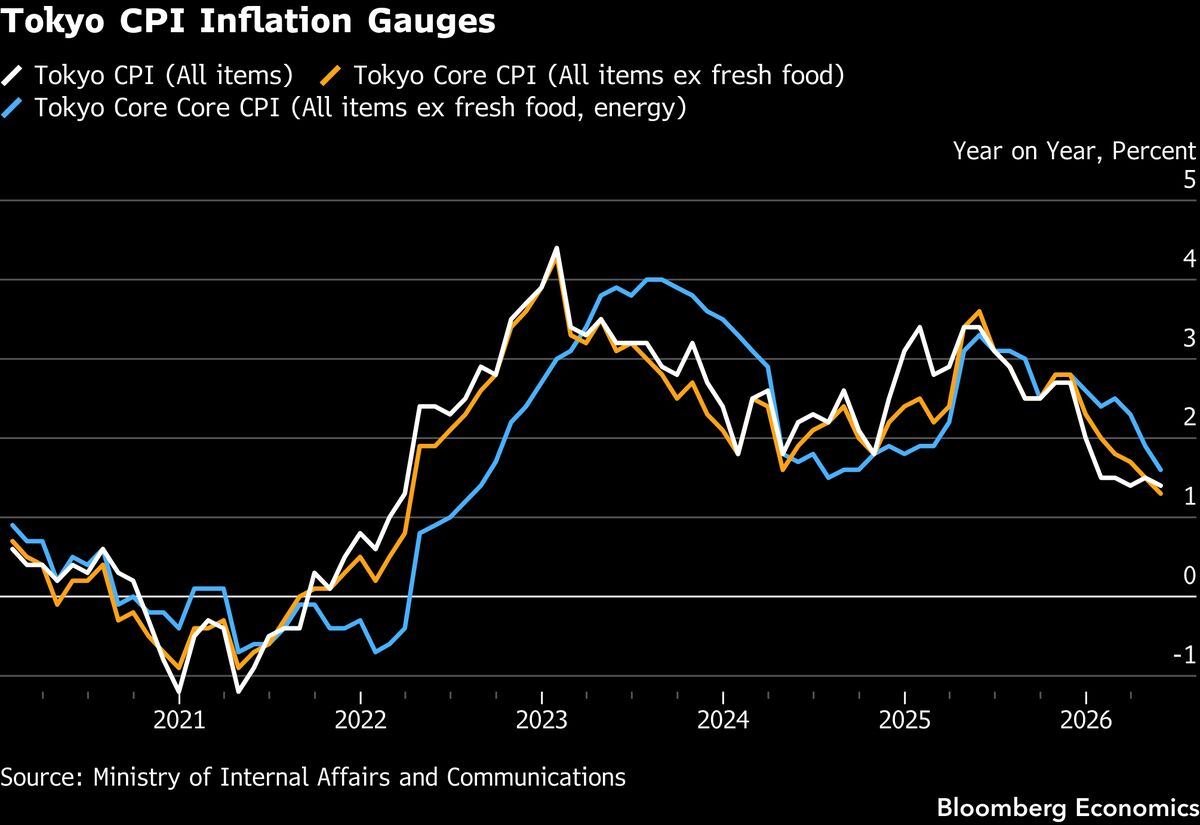
Tokyo CPI Friday — likely picked up on base effects. Core CPI ex fresh food to 1.7% YoY from 1.3% in May, headline to 1.8% from 1.4%. May's print was depressed by a temporary water-charge waiver and government gasoline-cap measures that lowered the year-earlier base for June. Strip the base effects and the underlying trend still looks hot. The report should keep the BOJ focused on further stimulus withdrawal. BE baseline is +25bp to 1.25% in December. Source: Bloomberg Economics.
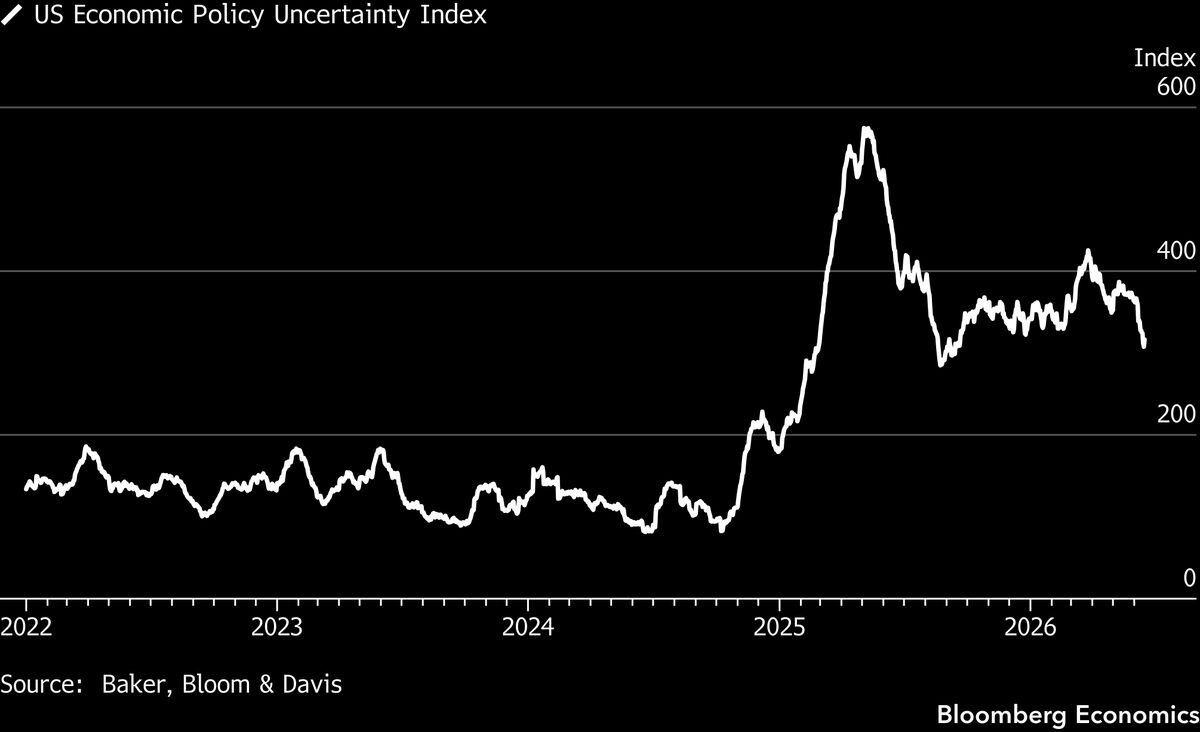
Michigan sentiment Friday — final 49.5e from a preliminary 50.5 and the prior 48.9. BE's reasoning is the US Economic Policy Uncertainty index has rolled off the early-2025 peak but is now back near 300, still well above the 2022-2024 range. A modest boost possible from the US-Iran MOU announcement. Improvement likely flows through easing geopolitical uncertainty and the perception that energy-price risks have fallen. Still, the boost may be limited if consumers remain focused on domestic concerns — inflation and interest rates. Source: Bloomberg Economics.
VC+ Special Dispatch — The Global Trust Deficit
A seven-chart dispatch on the corrosion of trust across nations, neighbours and institutions. The throughline: across 2025 and 2026 a remarkable run of surveys from Gallup, Pew, Transparency International and the Edelman Trust Barometer all point in the same direction. Global approval of US leadership has slipped behind China's for the first time in nearly two decades. The corruption-perceptions index posted its first decline in over a decade. Fewer than half of G7 democracies trust either their media or their government. Edelman frames 2026 as the year public grievance turns into social and political insularity. The macro implication is real — trust deficits compound into political volatility, which compounds into policy unpredictability, which compounds into risk premia. Credit to the VC+ team.
The World’s Verdict on America
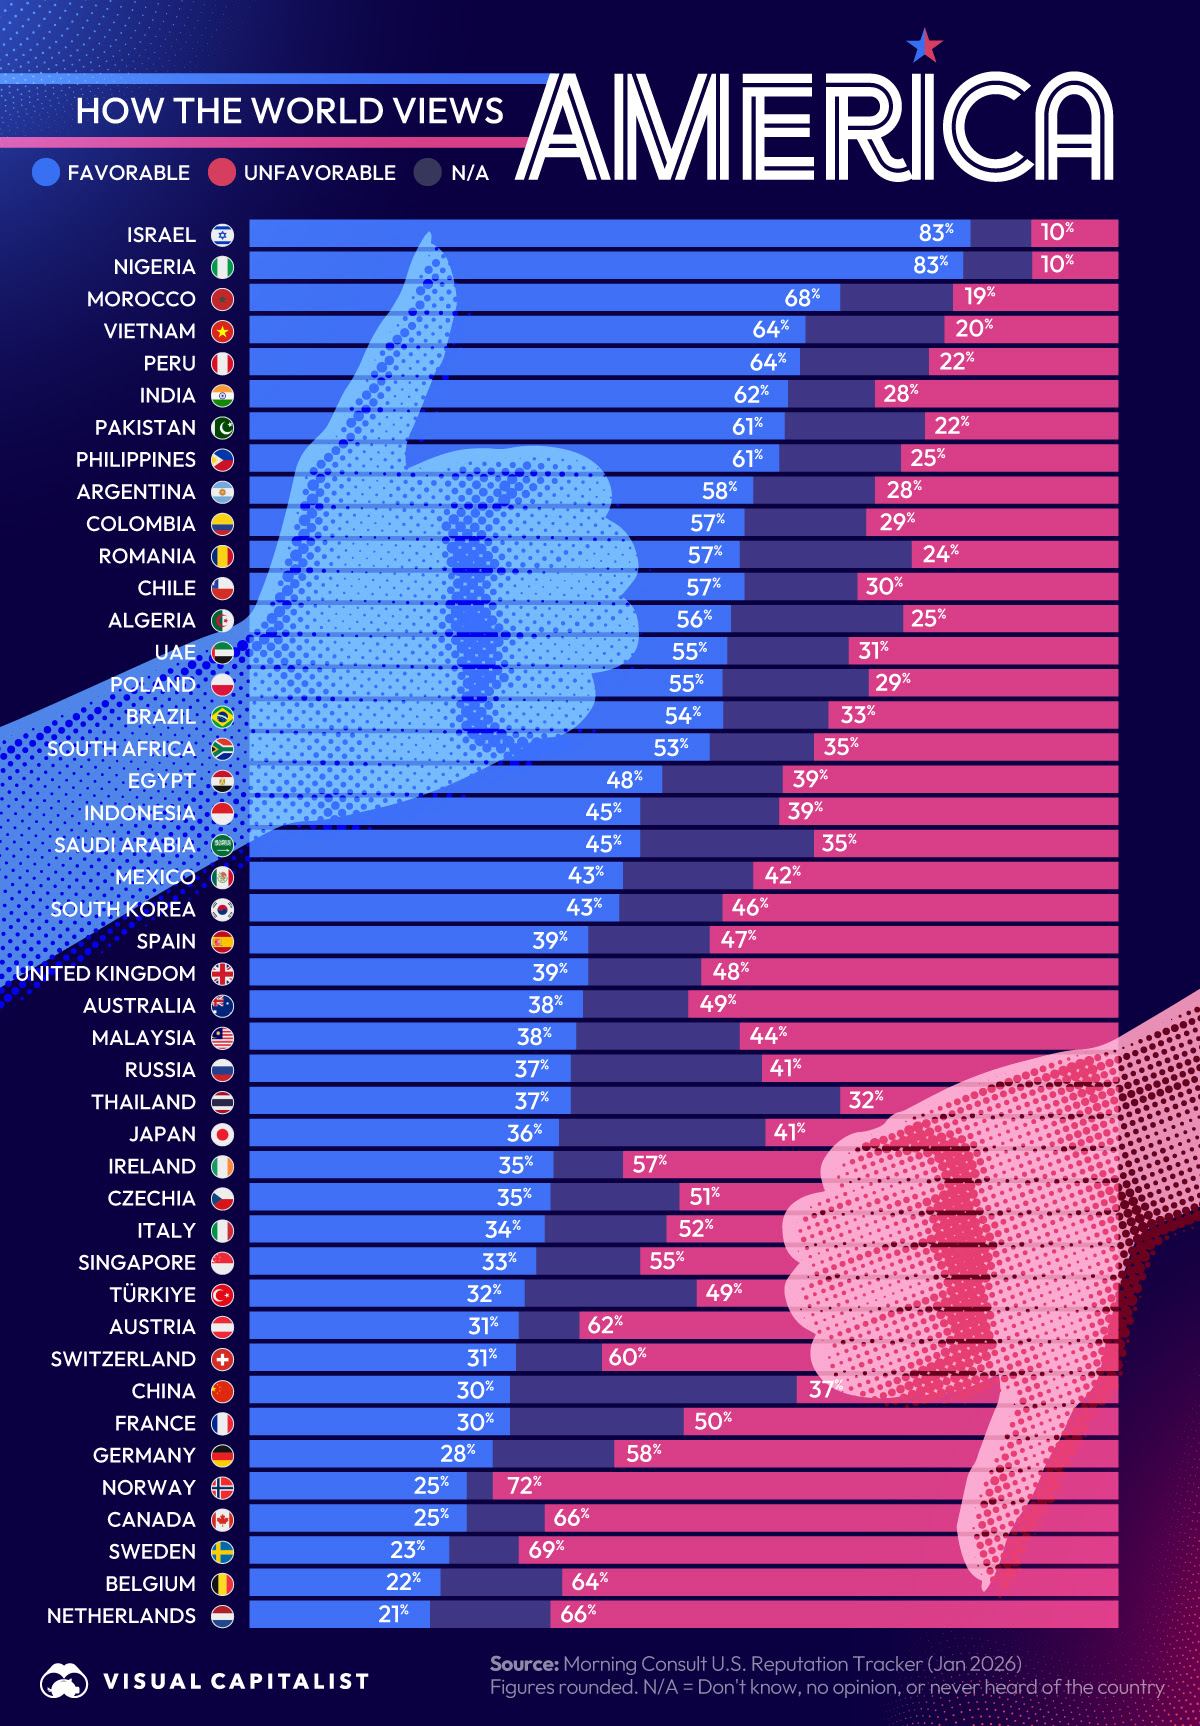
The world's verdict on America. Morning Consult's Reputation Tracker scored favourability toward the US across roughly 40 countries in early 2026. The result scrambles the usual map of friends and rivals — Israel, Nigeria, Morocco and Vietnam top the list while the Netherlands, Canada, Germany and France rank near the bottom. Gallup separately found global approval of US leadership slipped behind China's for the first time in nearly two decades. Approval inside NATO countries fell to 21%. Source: Morning Consult / Visual Capitalist.
America Returns the Gaze
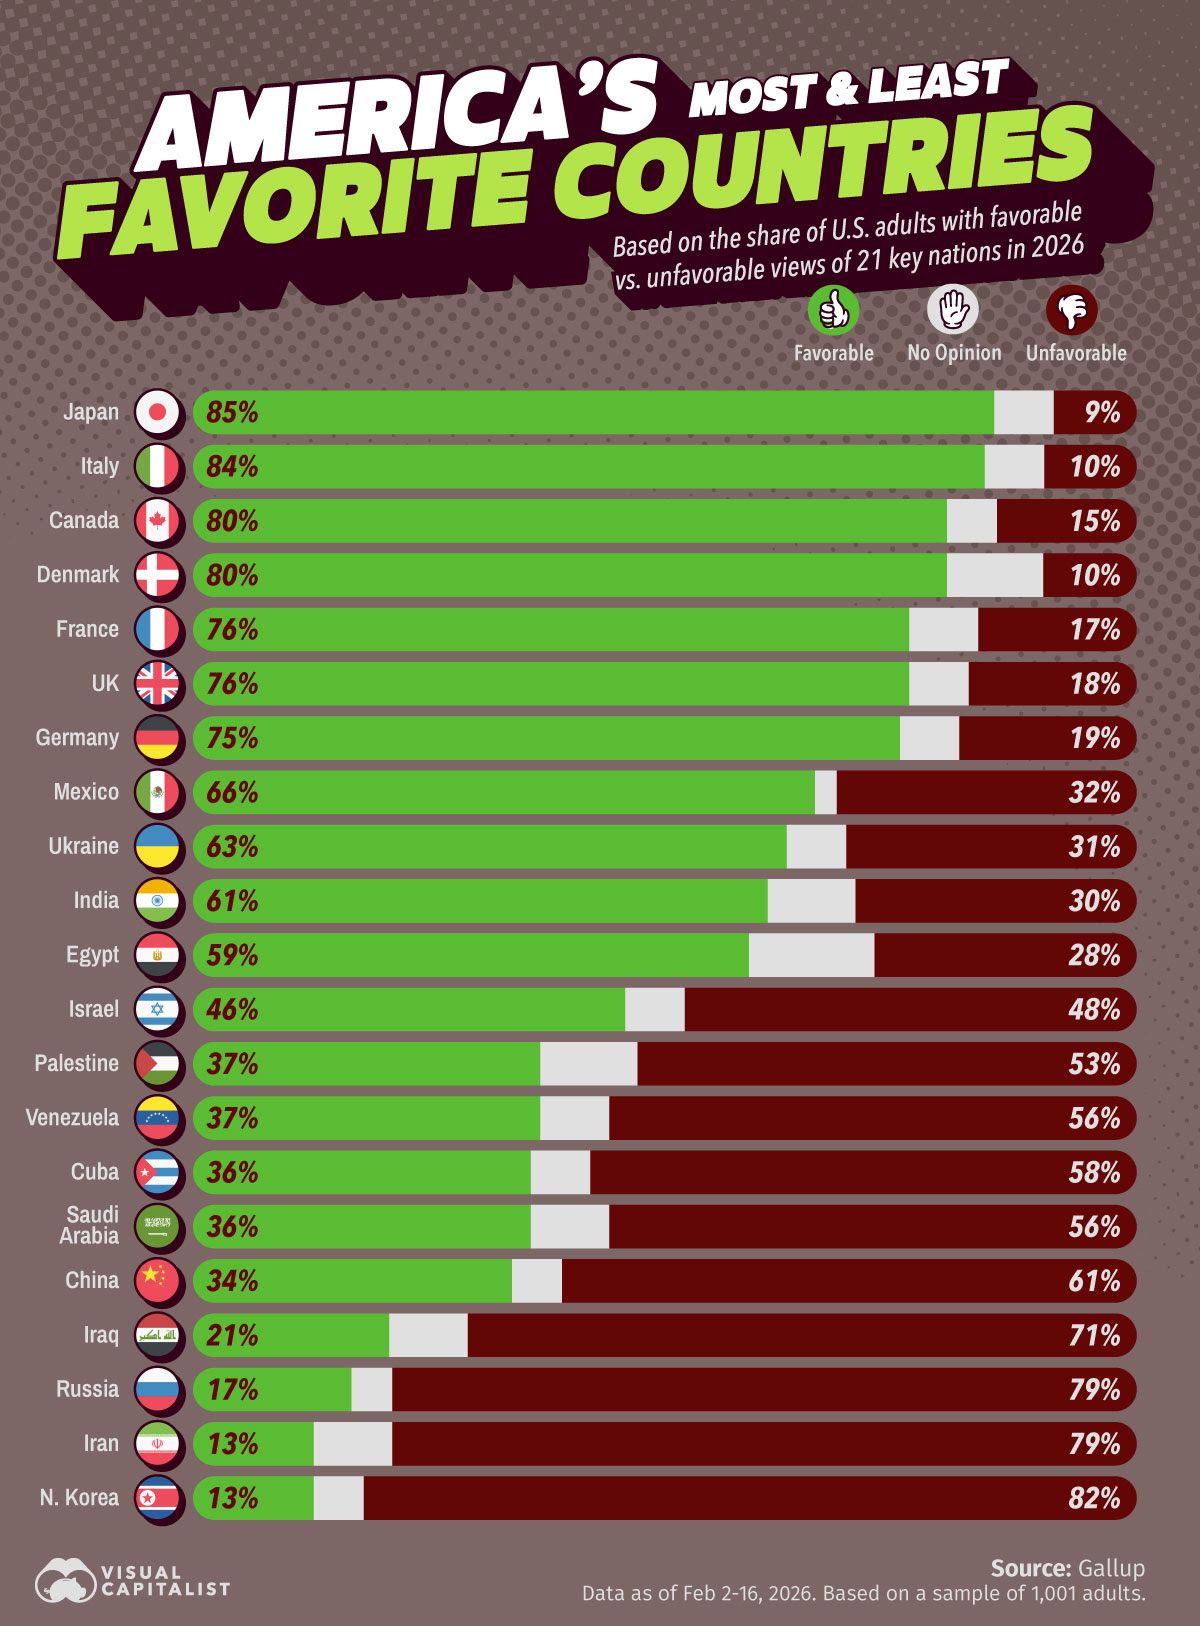
America returns the gaze. When Gallup asked Americans how they view 21 key nations in February 2026, the warmest feelings went to Japan (85% favourable), Italy, Canada and Denmark. The cold end sat North Korea, Iran and Russia, each viewed unfavourably by roughly eight in ten Americans. Favourability toward Canada and Great Britain hit record lows in 2026, the slide driven almost entirely by Republicans. For the first time since Gallup began tracking, Americans sympathise more with Palestinians than Israelis. Source: Gallup / Visual Capitalist.
The Global Reputation Leaderboard
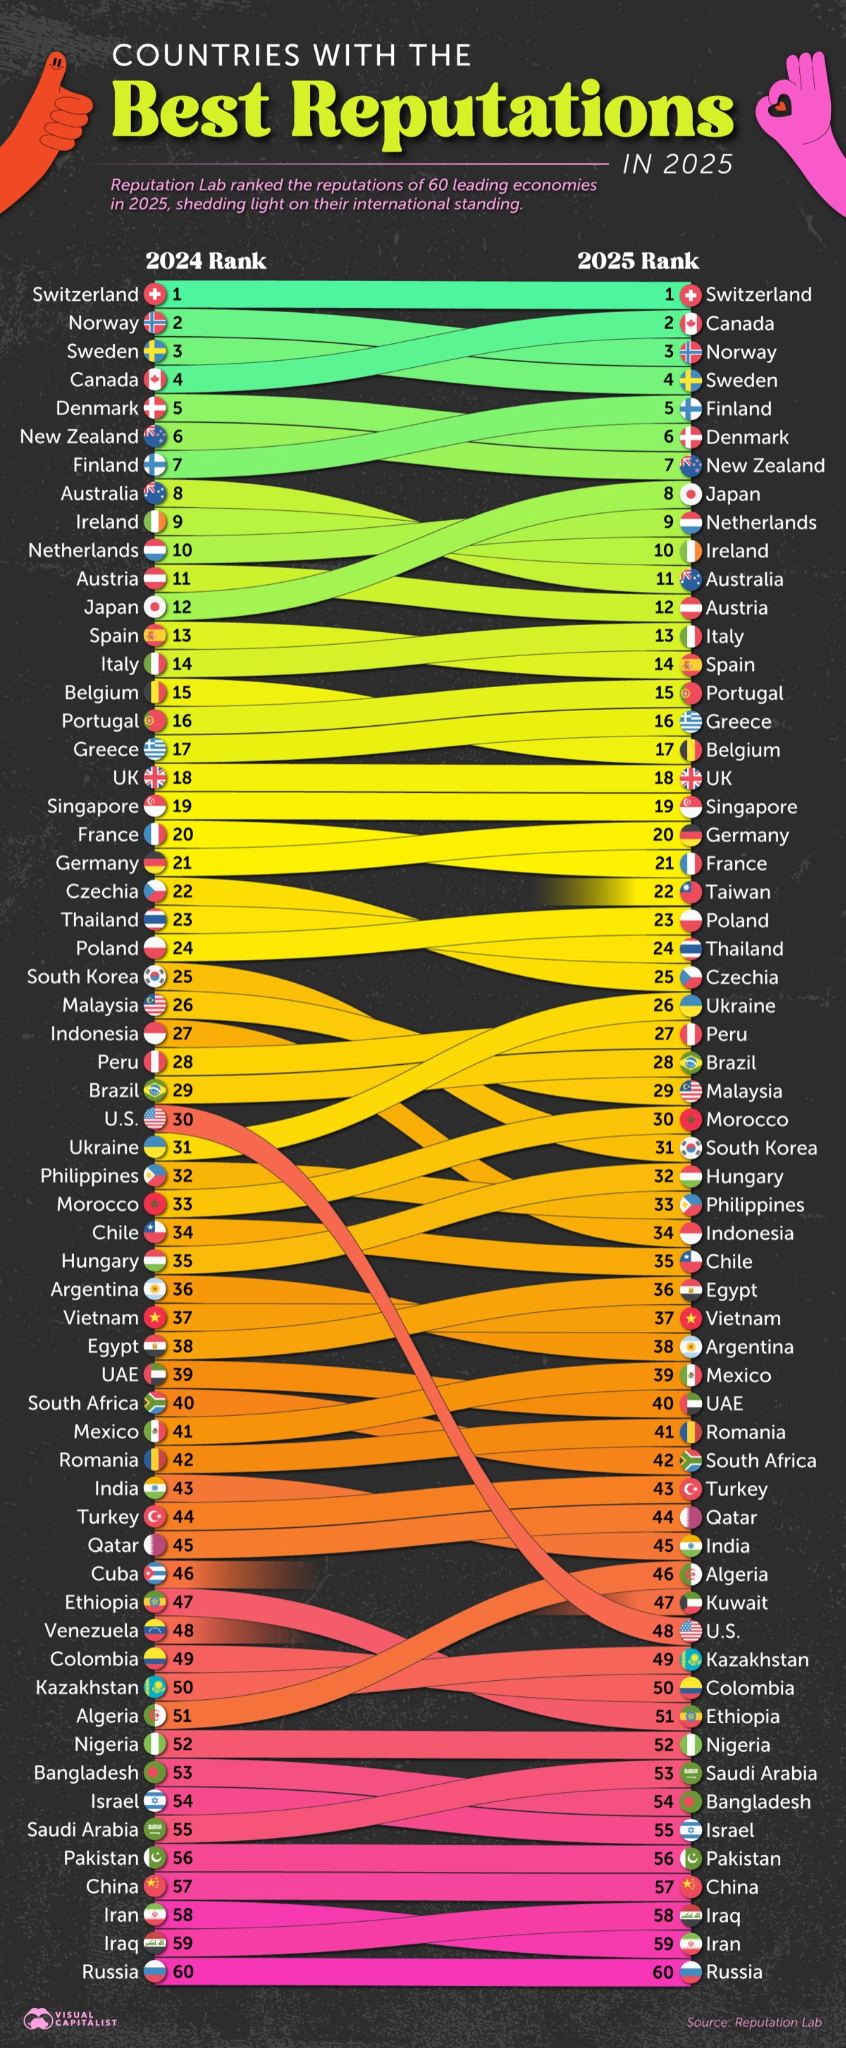
The global reputation leaderboard. Reputation Lab's RepCore Nations study ranks the world's 60 leading economies on how they are perceived by G7 nations. Switzerland, Canada and the Nordics dominate the top. The United States suffered the single largest drop of any country, sliding from 30th to 48th in a single year. Reputation Lab traces the fall to declining perceptions of international engagement, climate action and leadership. The same study estimates that each one-point gain lifts a nation's tourism revenue by roughly 7% and foreign investment by about 1%. Source: Reputation Lab RepCore Nations / Visual Capitalist.
Who Still Trusts Their Neighbours
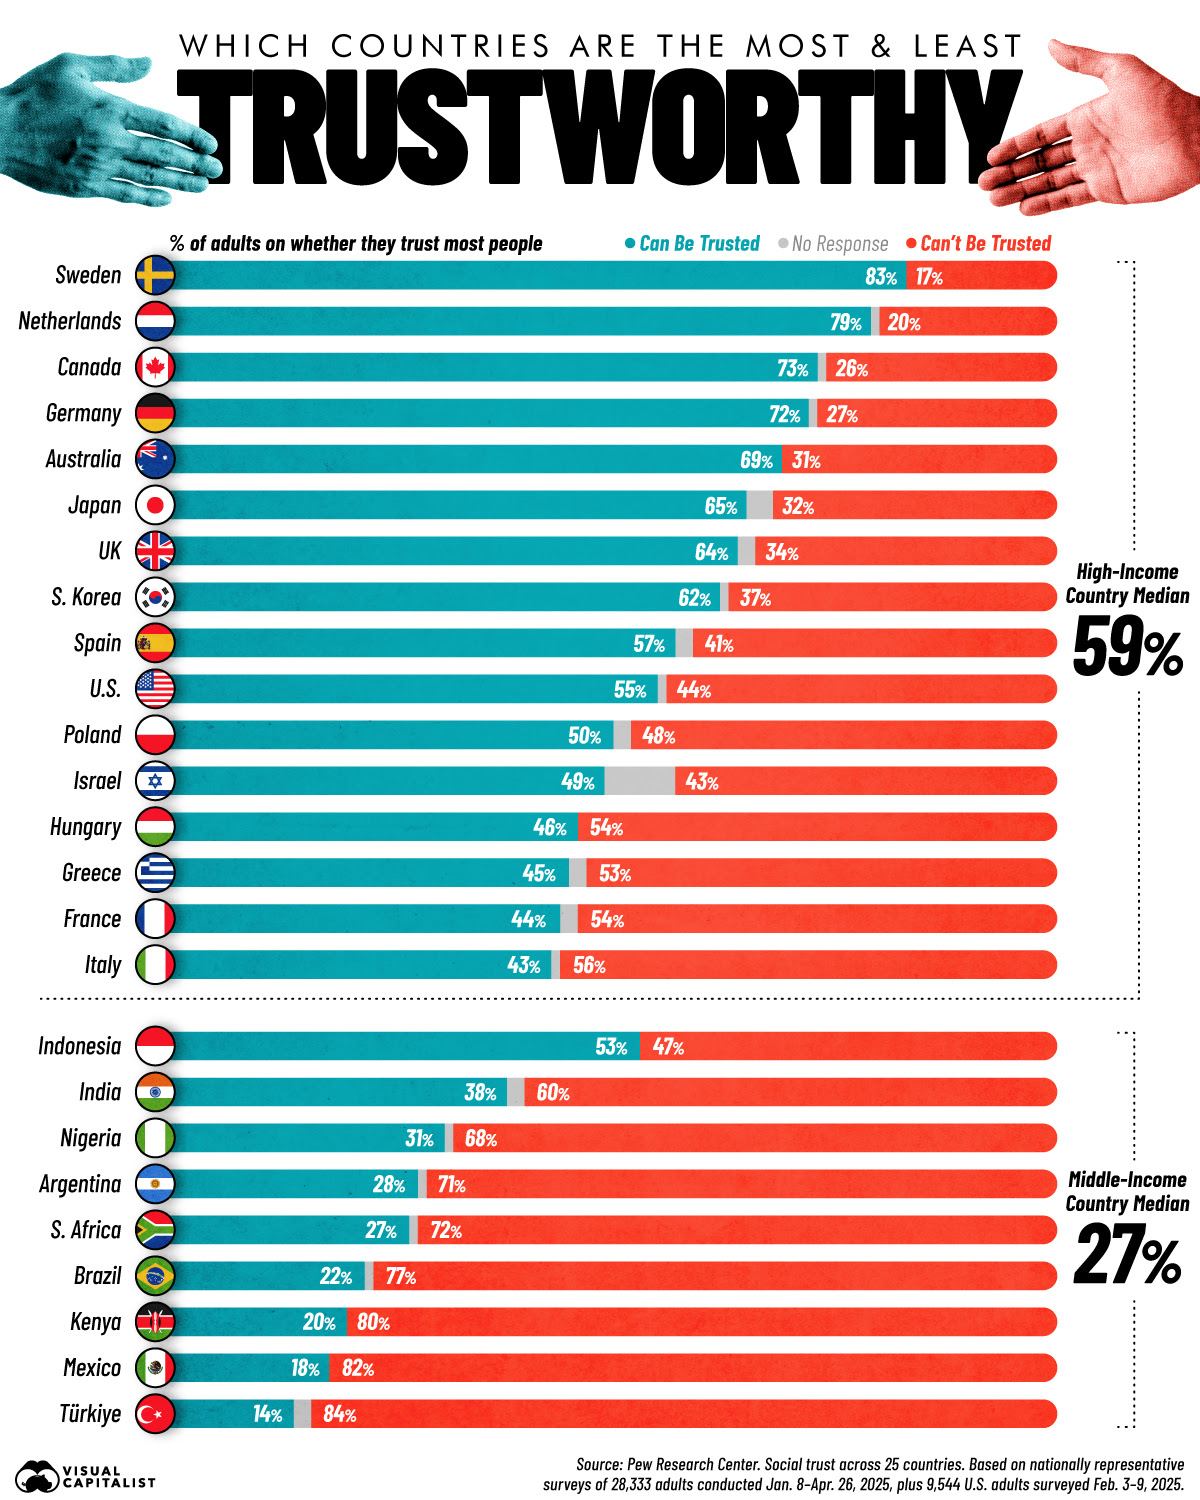
Who still trusts their neighbours. Pew asked adults in 25 countries whether most people can be trusted. The median was 59% in high-income countries but just 27% in middle-income ones. Sweden topped at 83%; only 14% of Türkiye said the same. Pew finds trust rises with income and education. Within the US it has eroded for half a century — from 46% in 1972 to 34% by 2024. Source: Pew Research / Visual Capitalist.
A Crisis of Faith at Home
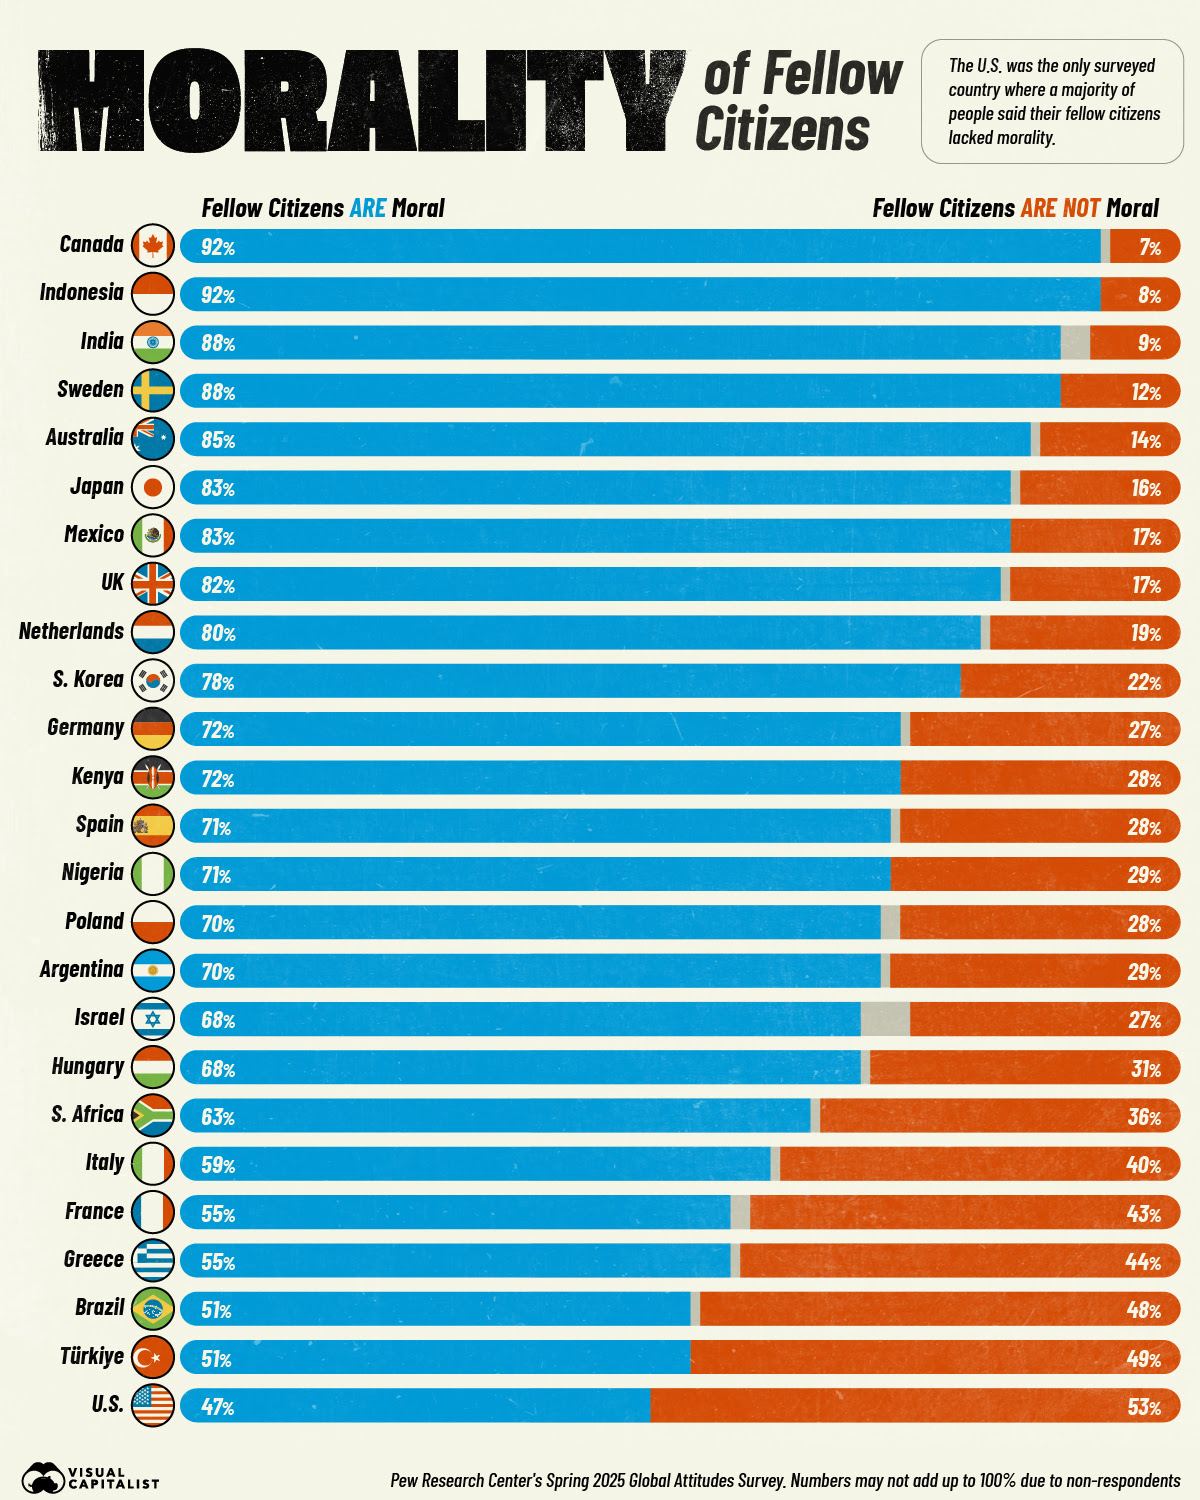
A crisis of faith at home. In a separate 25-country survey, Pew asked people whether their fellow citizens are basically moral. In every nation but one a clear majority said yes, with the United States the lone exception. Only 47% of Americans viewed their fellow citizens as moral. By contrast 92% of Canadians and Indonesians saw their compatriots as moral. Pew links the gloom to political polarisation. Source: Pew Research / Visual Capitalist.
Corruption’s First Comeback in a Decade
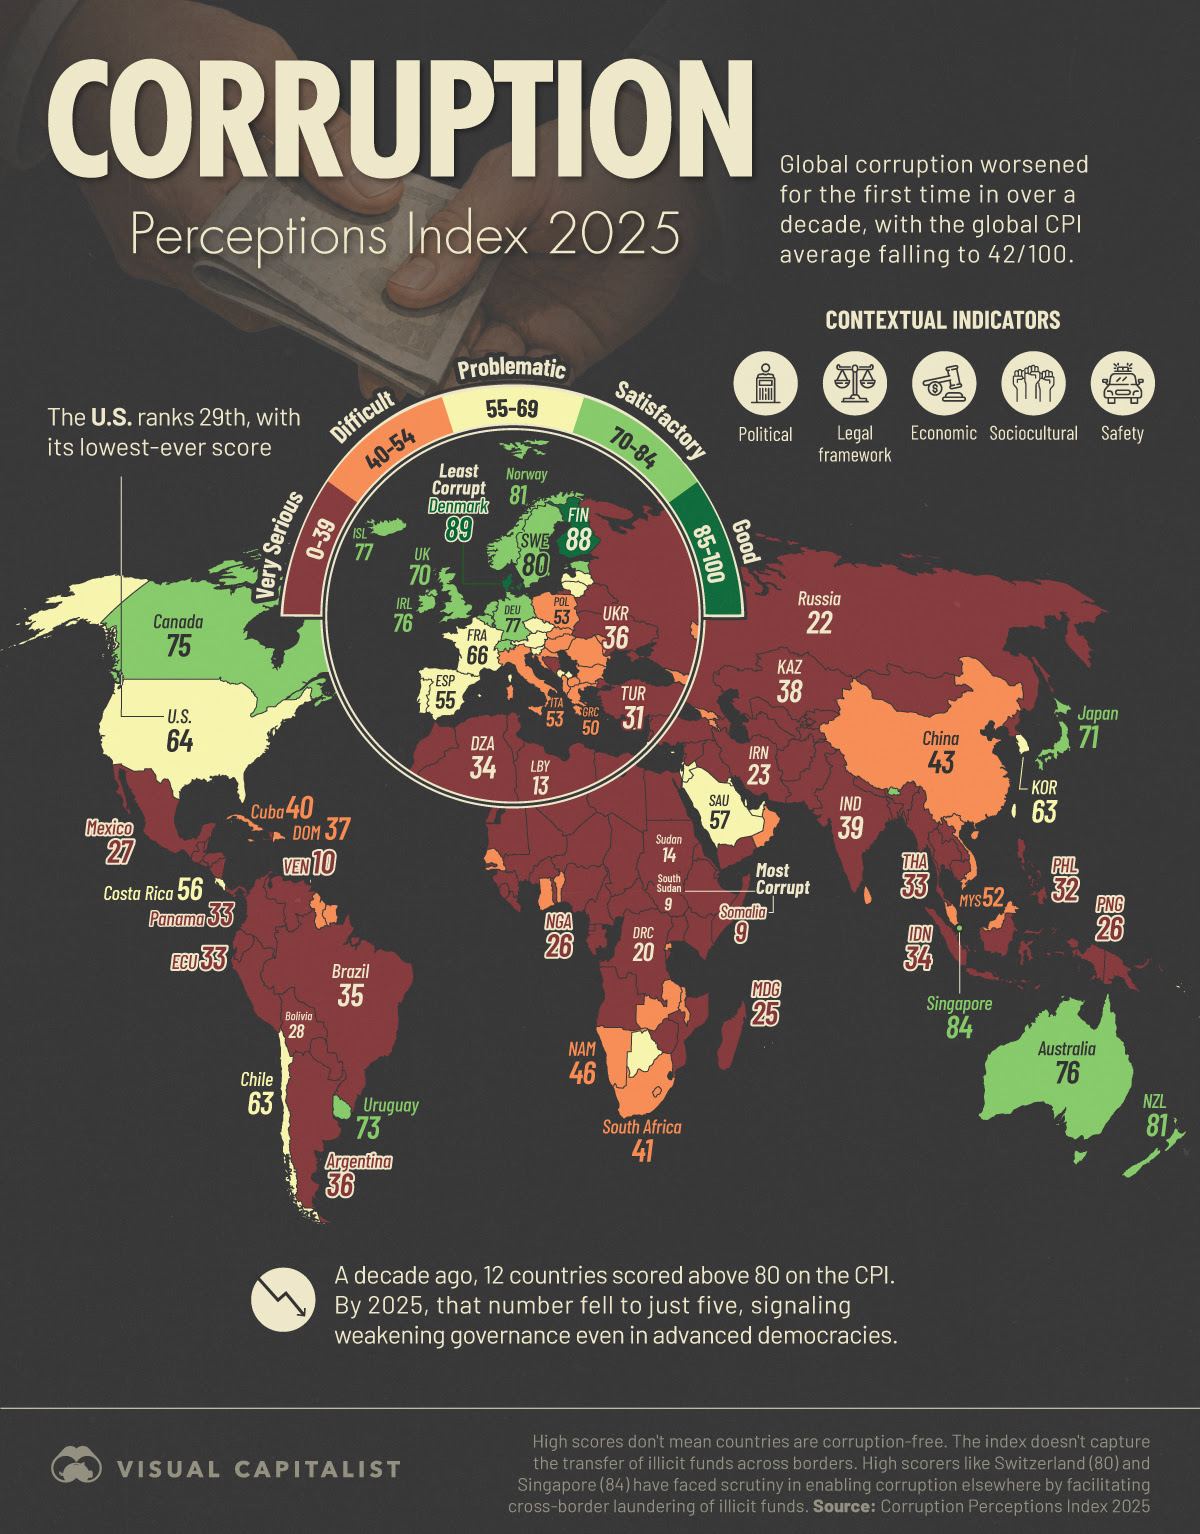
Corruption's first comeback in a decade. Transparency International's Corruption Perceptions Index scores 180 countries on perceived public-sector integrity. The 2025 global average fell to 42 out of 100 — the first decline in over a decade. The slide is concentrated where it is least expected. A decade ago 12 countries scored above 80; today only five do. The United States fell to 29th with a score of 64, its lowest ever recorded. Source: Transparency International / Visual Capitalist.
When Nobody Trusts the Institutions
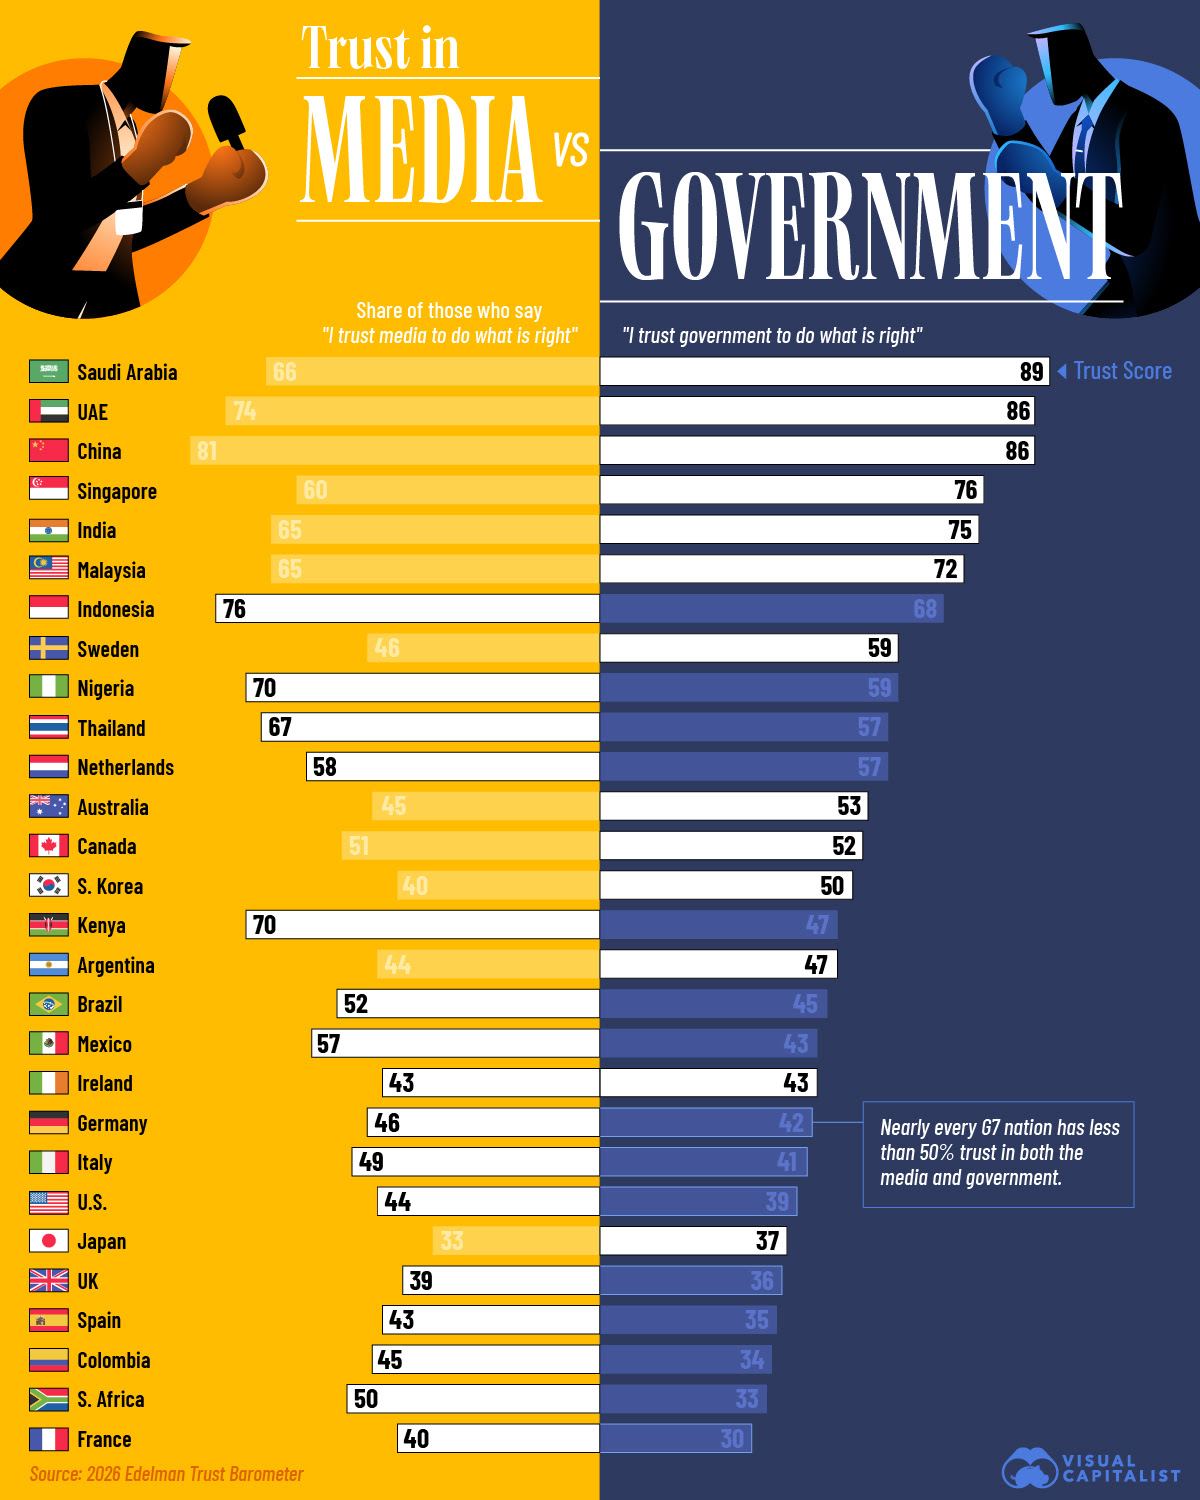
When nobody trusts the institutions. The 2026 Edelman Trust Barometer asked whether people trust their media and government to do what is right. In nearly every G7 democracy the answer for both is no. Fewer than half of Americans, Britons, Germans and Japanese trust either their media or government. The highest scores belong to Gulf monarchies and one-party states. Edelman frames 2026 as the year public grievance turns into social and political insularity — seven in ten now reluctant to trust those who hold different values. Source: Edelman Trust Barometer 2026 / Visual Capitalist.
The Good Wrap
What is left at the close. The government-debt-to-GDP picture with Poland leading at +8 percentage points and the US joining the worst-deteriorating cohort. The fertility map showing only Chad and Somalia still above replacement, India already down to 1.9 with New Delhi at 1.2 — the demographic shape of the next half century. The Tax Justice Network's 2025 Financial Secrecy Index with the US first, Switzerland second, Singapore third, Hong Kong fourth — the uncomfortable mirror of trust deficits. Cloudflare's read that bot traffic has overtaken human traffic for the first time, 57.4% versus 42.6%. The Economist read that AI-generated e-books now total ~300k a month on Amazon versus ~100k pre-ChatGPT-3.5, the tail of the public-corpus inflation. Sportsbook stocks getting eaten by prediction markets — Flutter -50% YTD, DraftKings -26%. The ISAPS 2025 global plastic surgery numbers — eyelid surgery 2.1M, botulinum toxin 7.9M — the discretionary-consumer barometer with a quiet AI twist as filters and AI-generated comparison images keep the pipeline full. Closing on the cellar discipline — blind wine tasting and the trader's discipline are the same thing.
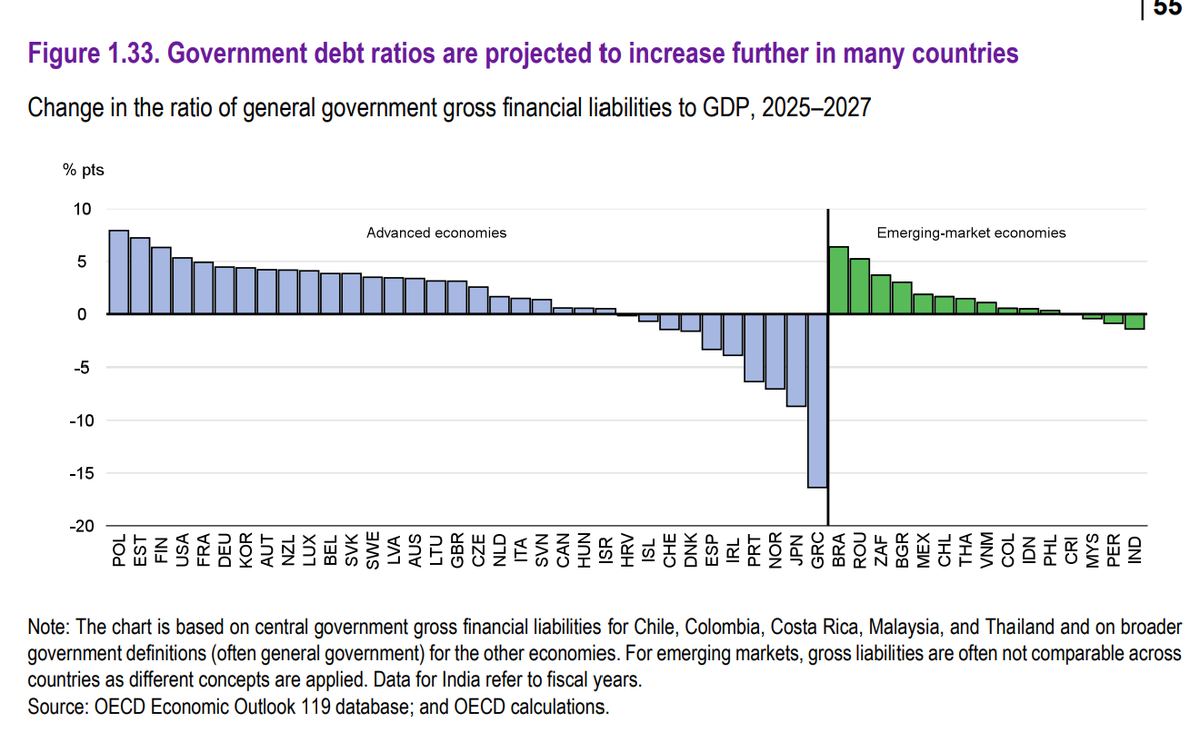
Government debt ratios projected to increase further in many countries through 2025-2027. Poland leads on advanced economies at +8 percentage points. The US among the worst-deteriorating with a +6 jump. Greece projected to deleverage the most (-16). The fiscal expansion side of the constraint as central banks try to control inflation from the demand side. Source: OECD Economic Outlook.
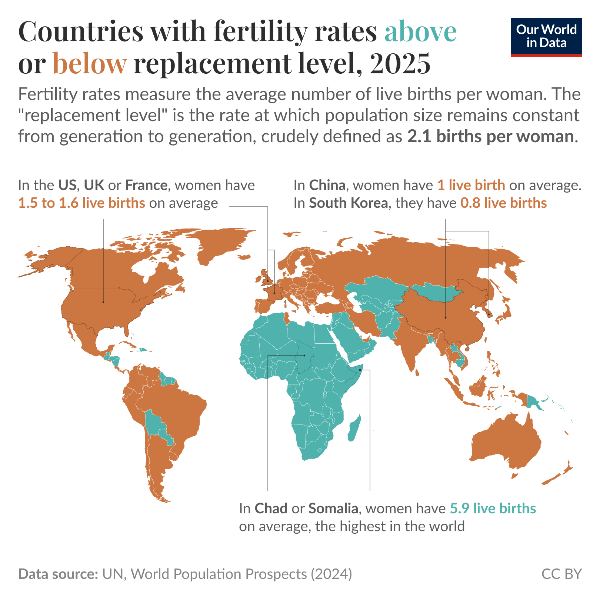
Fertility below replacement in most of the world now. US, UK and France average 1.5-1.6 live births per woman. China 1.0, South Korea 0.8. Only Chad and Somalia retain 5.9. Replacement level is 2.1. India recently fell below replacement at 1.9 — New Delhi already at 1.2. Global population projected to grow just 24% over the next 75 years, vs +231% over the prior 75 years. Source: Our World in Data via Visual Capitalist.
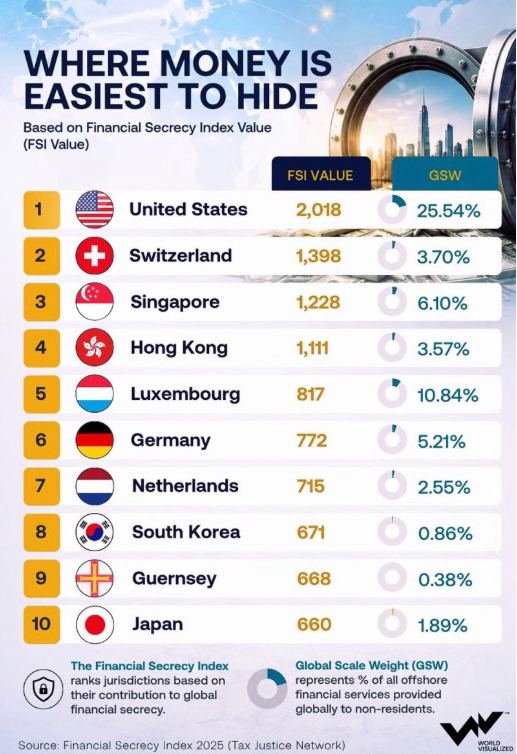
Where money is easiest to hide. Tax Justice Network's 2025 Financial Secrecy Index ranks the US first at 2,018 — and gives the US a Global Scale Weight of 25.5% of all offshore financial services provided to non-residents. Switzerland a distant second (1,398), Singapore third (1,228), Hong Kong fourth (1,111). The US the world's largest secrecy jurisdiction while pressing others to reform. Source: Tax Justice Network / World Visualized.
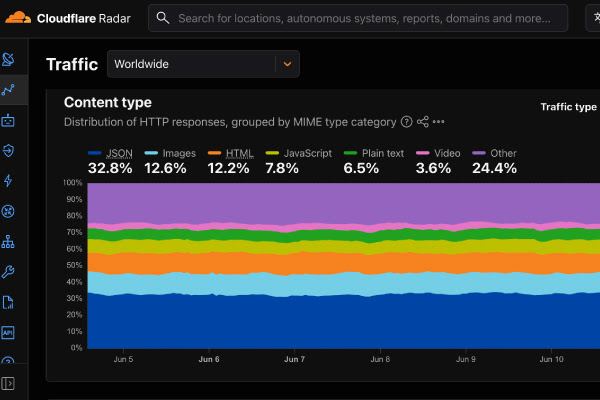
Bot traffic has overtaken human traffic for the first time. Cloudflare Radar — 57.4% of requests from bots, 42.6% from humans. People typically click on five websites before a purchase; AI bots can click 5,000. In Singapore, Iran and Ireland the share of automated traffic exceeded 72% earlier this month. AI agents consume content without clicking ads. Publishers will increasingly explore ways to control, license or charge for access to their content. Source: Cloudflare Radar via Visual Capitalist.
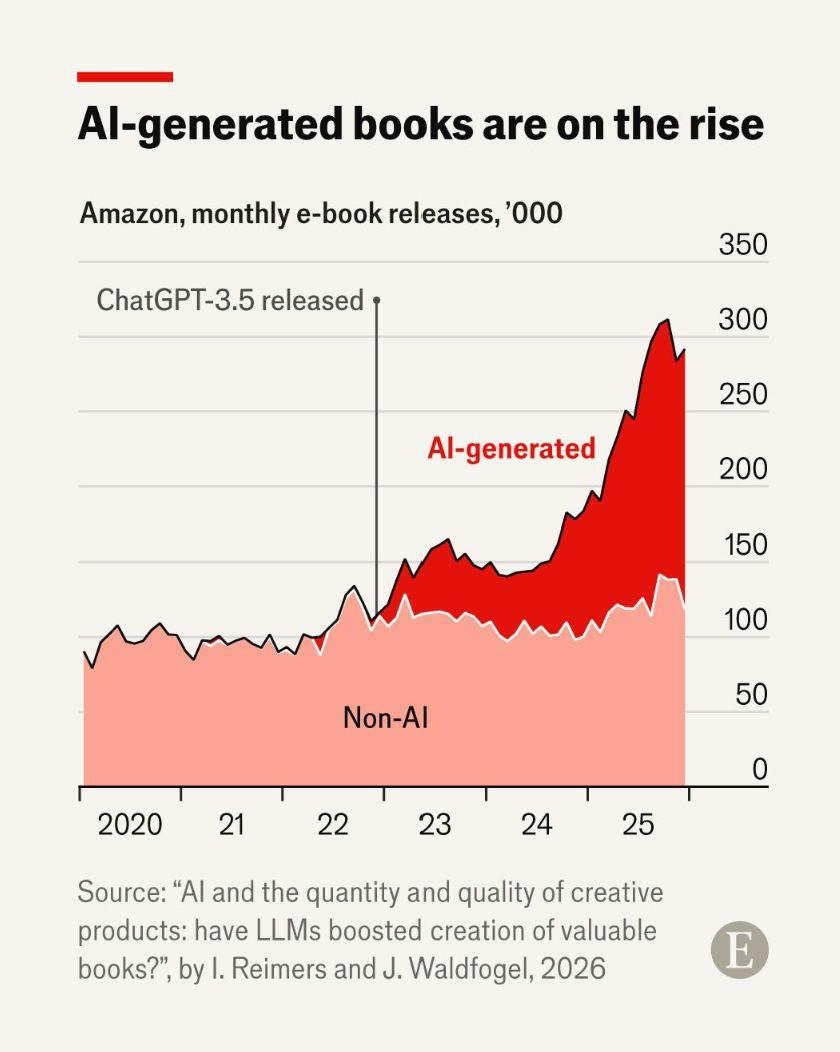
AI-generated books are on the rise — Amazon monthly e-book releases. By end of 2025 approximately 300,000 e-books are released monthly on Amazon versus roughly 100,000 pre-ChatGPT-3.5 in November 2022, with AI-detection tools confirming chatbots drove the increase. The Economist read. Tail of the public-corpus inflation. The supply curve of explicit knowledge is going asymptotic while the demand for tacit knowledge keeps rising. Source: The Economist via Instagram.
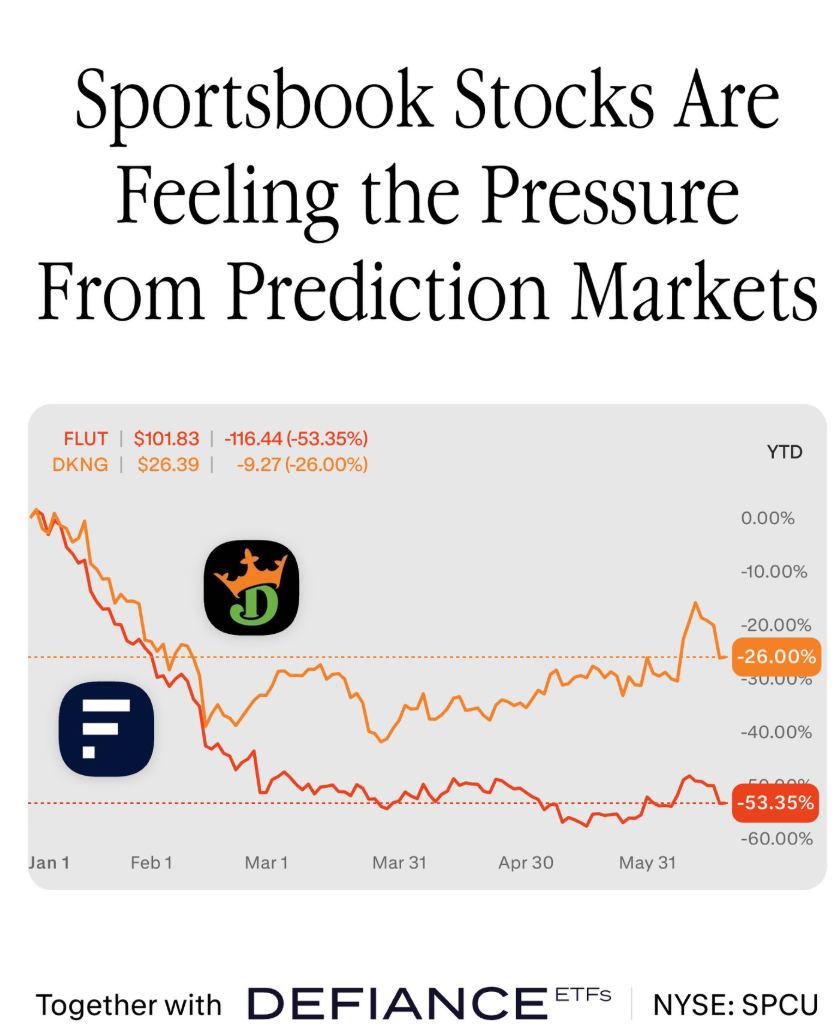
Sportsbook stocks are feeling the pressure from prediction markets. Flutter (FLUT) down more than 50% since January 1. DraftKings (DKNG) down 26% over the same period. Polymarket and Kalshi are siphoning market share. Kalshi saw more than $1.3 billion in estimated revenue from sports contracts, roughly 20% of DraftKings revenue per the FT, and the regulated arbitrage between betting and prediction markets is closing fast. Source: Instagram.
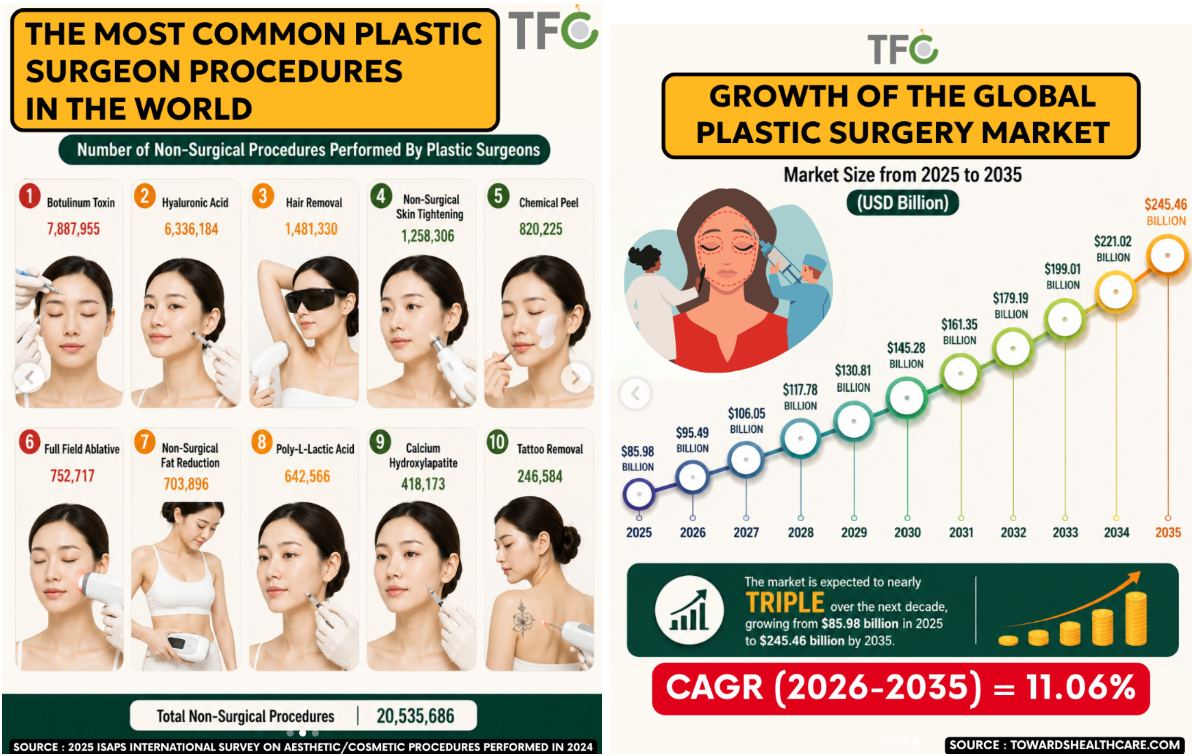
Global plastic surgery trends — 2025 ISAPS survey. Eyelid surgery 2.1M procedures globally, liposuction 2.1M, breast augmentation 1.7M. Non-surgical dominated by botulinum toxin (7.9M worldwide) and hyaluronic acid (6.3M). The discretionary-consumer barometer with a quiet AI twist — Instagram filters and AI-generated comparison images keep the pipeline full. Source: ISAPS via Instagram.
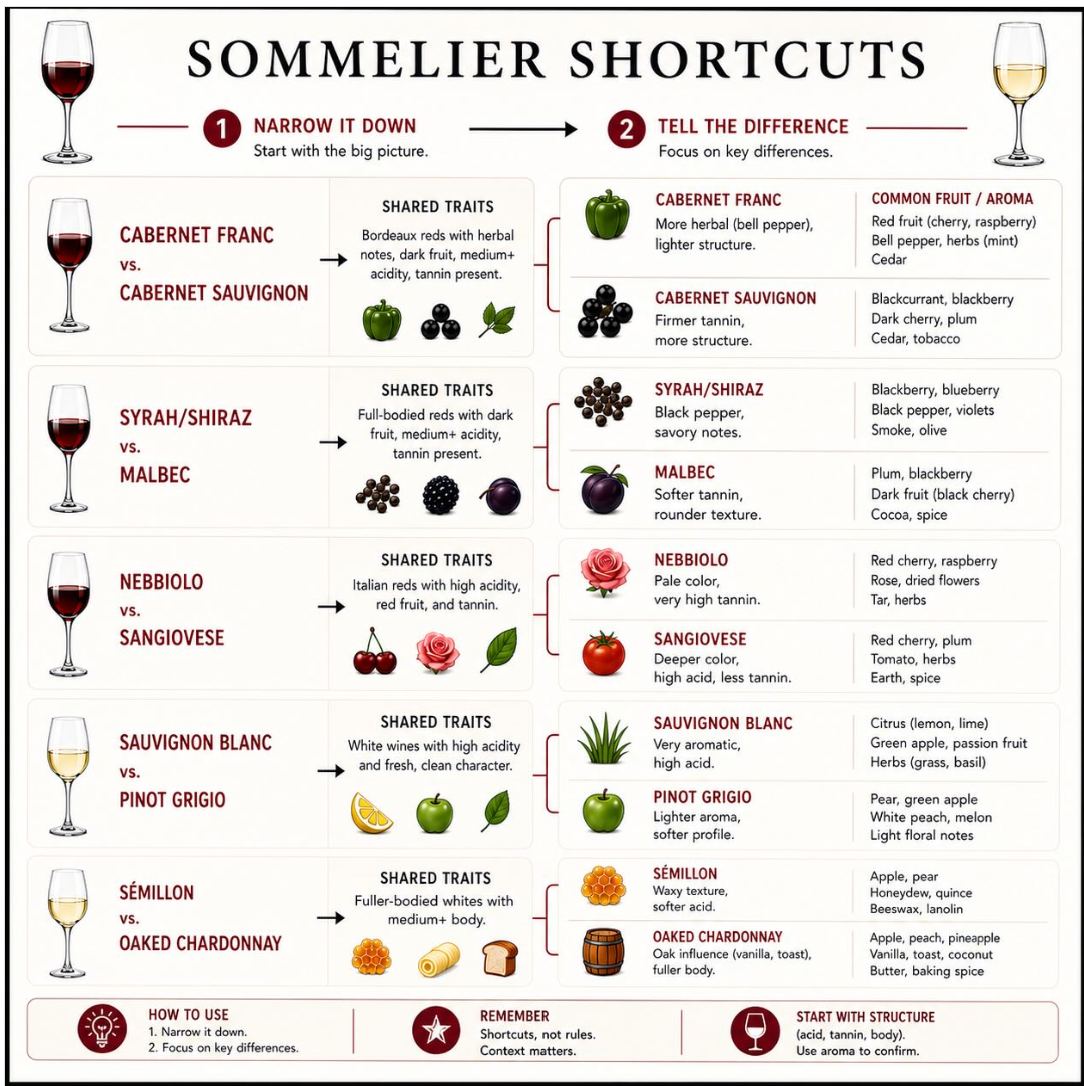
Common blind wine tasting mixups and how to avoid them. A reminder that tasting under uncertainty is the same discipline as trading under uncertainty. The cellar is the carry trade with longer holding period and better optics. A Sunday closer. Source: Instagram.
Best,
Hoelon
WITPTW is a personal publication. Everything here is personal opinion and market commentary, written in a personal capacity. It is not investment advice and not a recommendation to buy or sell any security. It is not associated with, endorsed by, or representative of any employer, fund or company. Charts and images are reproduced from their original publishers, credited to their sources for commentary and discussion; all rights remain with the respective copyright holders.