The Cloud Test
Personal views and market commentary. Not investment advice. Not associated with any employer or firm.
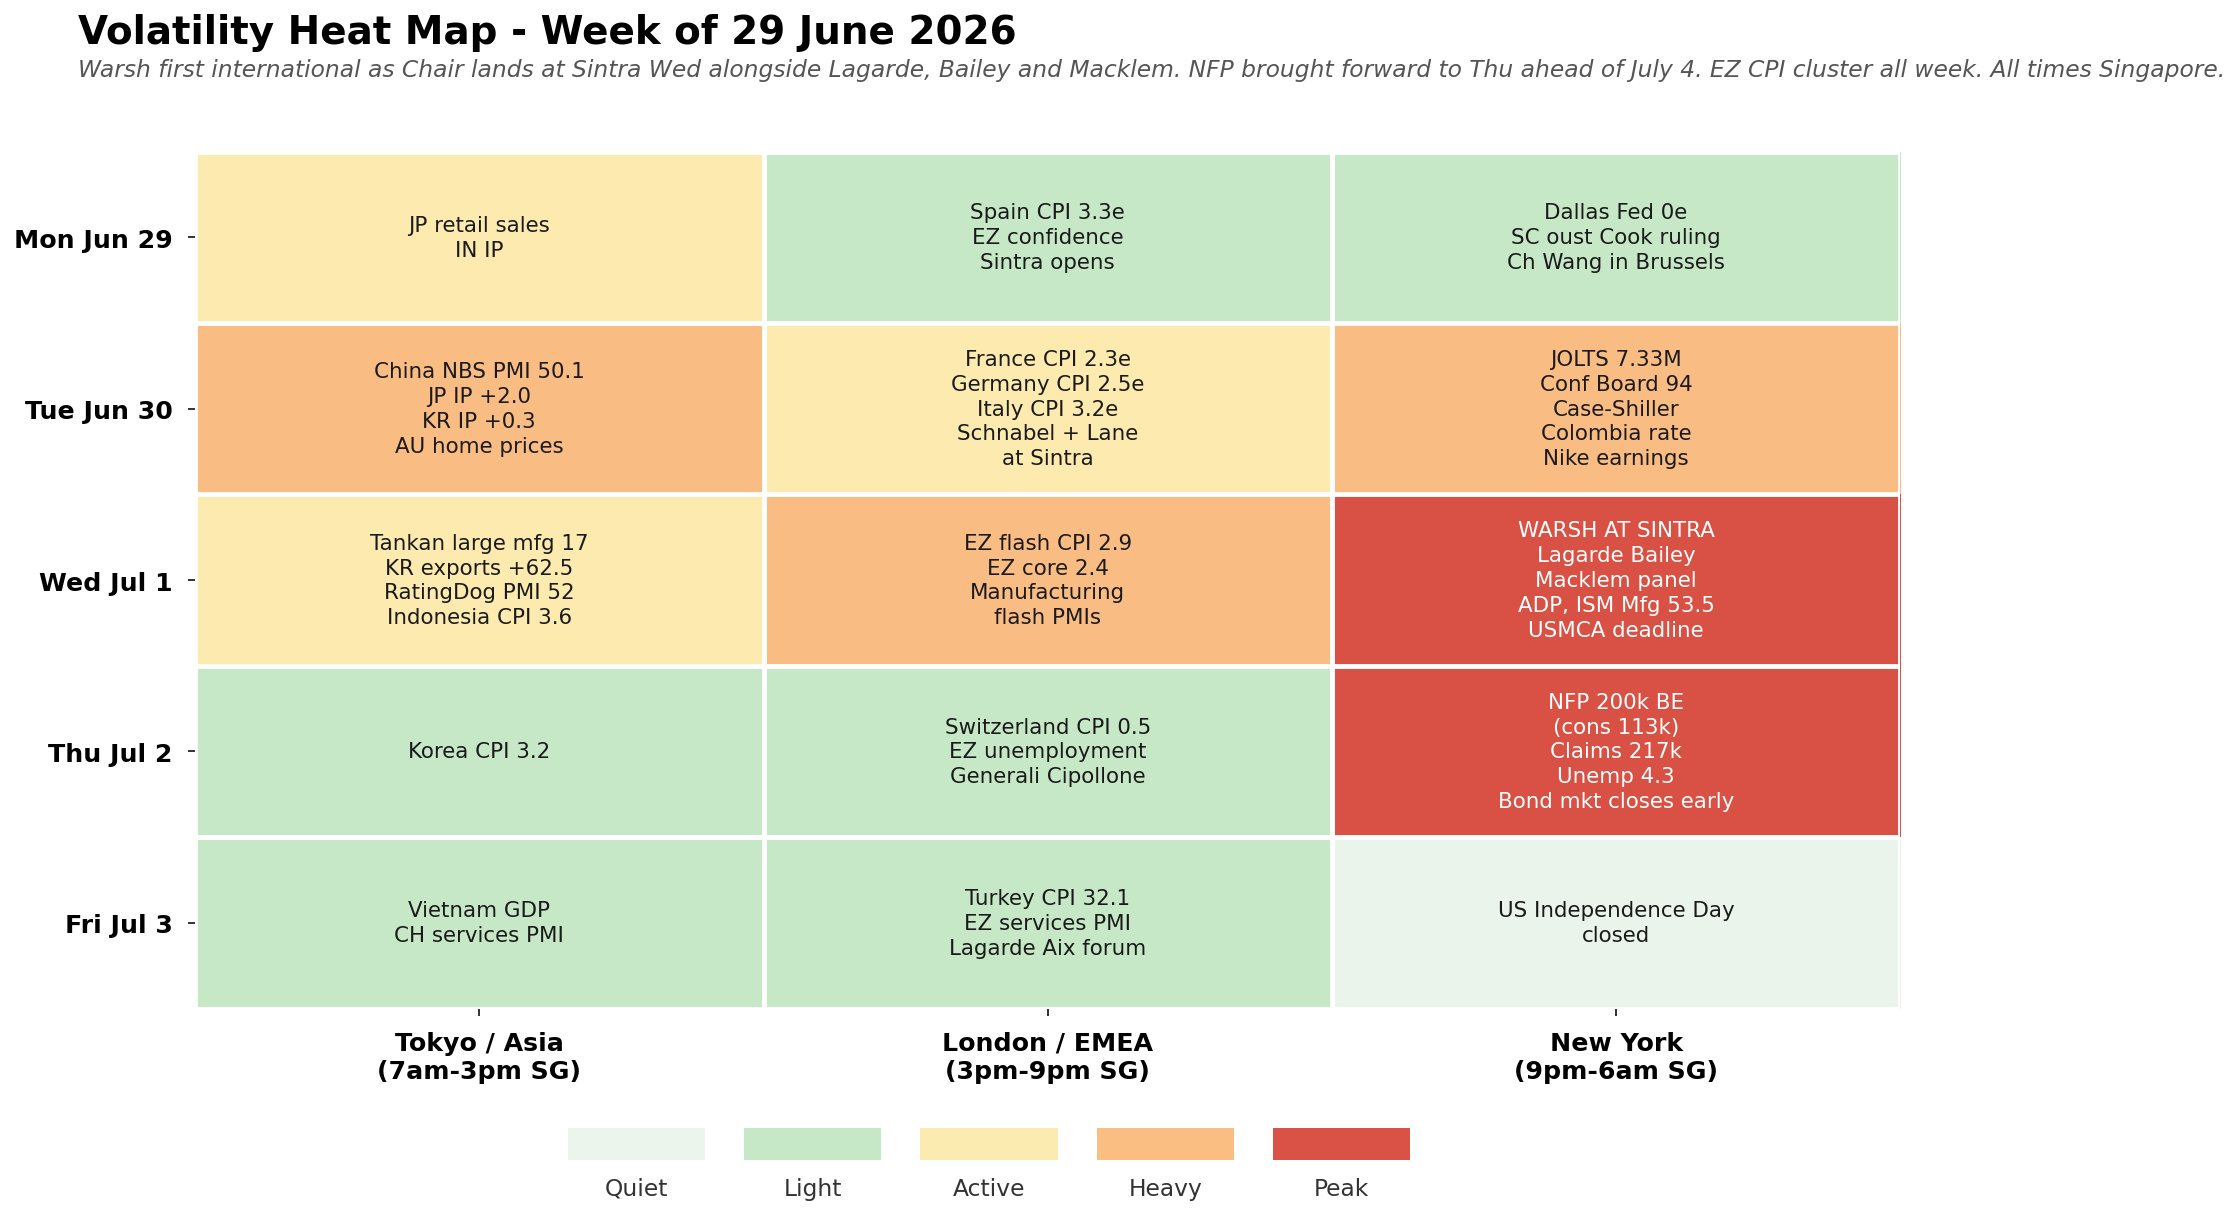
Volatility heat map for the week ahead, all times Singapore. Warsh's first international as Chair lands at the Sintra panel Wednesday alongside Lagarde, Bailey and Macklem. NFP brought forward to Thursday ahead of US July 4 holiday, BE 200k vs cons 113k. Tuesday is the eurozone CPI cluster, the China official PMI, JOLTS and Conference Board confidence. Wednesday adds EZ flash CPI, the BOJ Tankan, the RatingDog PMI, ADP and ISM Manufacturing. Friday is a US holiday wind-down.
"SpaceX raising debt so soon after a blockbuster equity issuance is a good example of markets shifting from a healthy boom, a stretched boom, into bubble territory." — Ludovic Subran, CIO of Allianz, in an interview at the FT Global Insurance Summit. The Allianz CIO speaks for the €800bn balance sheet that has to fund the AI buildout from the long-duration side. The $25bn SpaceX bond followed an $86bn IPO by ten days. The bonds began trading Wednesday and were already off roughly $305m versus Treasuries by Thursday, the fastest such weakening in recent memory. Tech high-grade spreads up to 0.79 percentage point from 0.74 at end-May. Bondholders are being asked to take obsolescence risk for decades, on a company expected to burn through $113bn of cash by end-2027. Allianz is the cautious end of the buyer base saying the price is no longer the entry price.
"The sudden restriction of certain frontier models is deeply regrettable. GLM-5.2 is fully open. Frontier intelligence belongs to everyone." — Tang Jie, co-founder and chief scientist of Zhipu AI, releasing GLM-5.2 one day after the US Commerce Department ordered the global suspension of Anthropic's Mythos and Fable 5 on June 12. GLM-5.2 hit 39% on the Semgrep IDOR vulnerability-detection benchmark, ahead of Claude Code Opus 4. The benchmark the US government cited as the justification for the June 12 export control is the exact one Zhipu chose to match, distributed under the permissive MIT licence with no regional restriction. Whether the parity claim holds on broader tasks, the open-weights model now sits inside every cloud and every laptop. The export-control envelope drawn around Anthropic in June is leaking from the day it was drawn, and the capex thesis still assumes US frontier-model dominance, an assumption being repriced in real time.
"If I seem unduly clear to you, you must have misunderstood what I said." — Alan Greenspan, US Senate Banking Committee. The line was self-deprecating when Greenspan said it. Warsh has built the post-Powell Fed around it. The June statement was dramatically shorter, the forward-guidance reference deleted, the chair himself absent from the dot plot. Yet nine of eighteen Fed officials still baked in at least one hike this year. The two-year jumped 13 basis points on the day, the largest single-session move since April 2025. Warsh chairs his first international panel on Wednesday at 14:00 Lisbon time at the ECB Forum on Central Banking in Sintra, alongside Lagarde, Bailey and Macklem, moderated by Sara Eisen. The question is whether the deliberate opacity reads as conviction or as drift in front of a room of peers who never used it themselves.
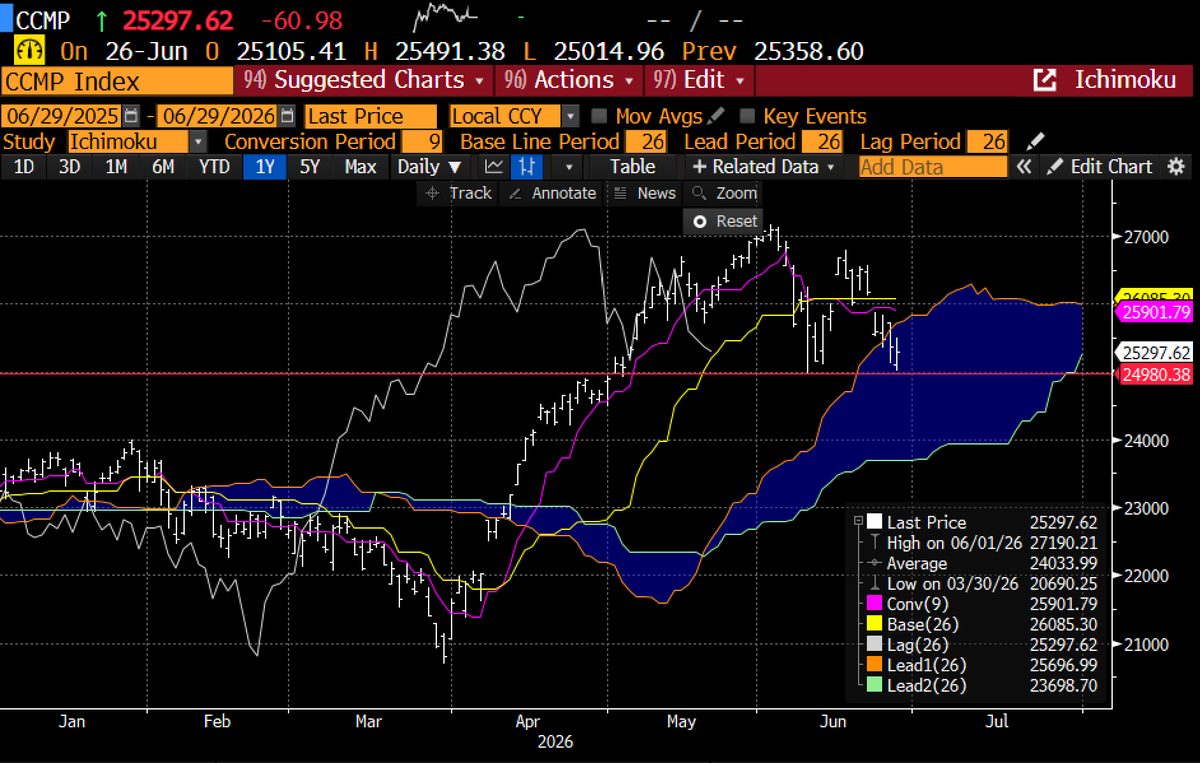
Nasdaq walking into the Ichimoku cloud, testing 25k again. The CCMP closed at 25297.62 on Friday, off 60.98 from 25358.60. Intraday low 25014.96. The conversion at 25901.79 and the base at 26085.30 have rolled over and now sit as overhead resistance. The cloud top is at 25696.99, the bottom at 23698.70. Price is testing the cloud from the inside, the bullish lag-line breakdown is the next visible event. Whether the cloud holds as the Fed talks hawkish into Sintra is the equity question that defines this week. Source: CCMP Index, ichimoku reproduction.
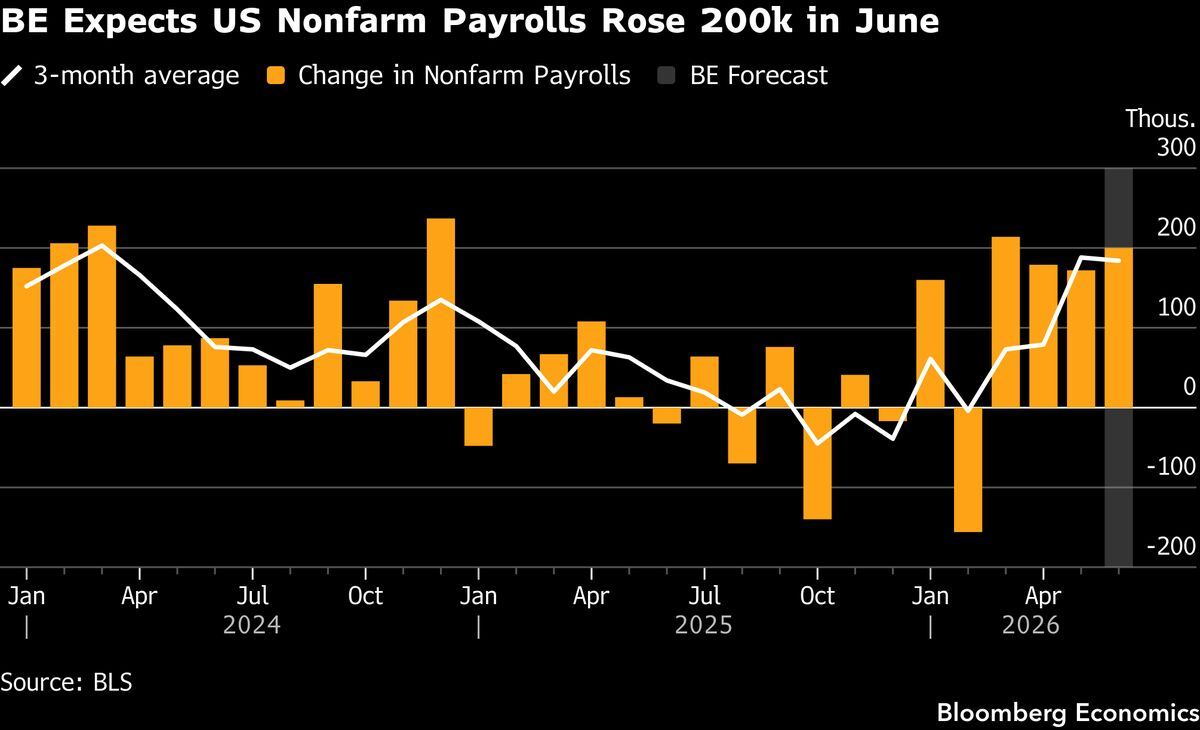
NFP Thursday — BE 200k, consensus 113k, prior 172k. The gate of the week. Government sector likely adds 80k. Education and health services the largest contributor, with leisure and hospitality boosted by World Cup hiring. Unemployment 4.3% same as May. A hot print fuels bets for hikes this year, a soft print opens the seasonal-weak window early. AHE the deciding sub-component. Source: Bloomberg Economics.
What is the plan this week?
The lower oil price action of the last few weeks was pricing in the Trump administration pushing through the Iran peace talks, and the last few days a few exchange-of-fire incidents in the Strait have started to sound like they threaten the talks. Trump called the IRGC firing on a tanker a foolish violation, but took no tangible action. The talks should still carry on. Brent is back to pre-war near $73, the curve is flat, and the contract looks like it wants to base and stick in a range from here. Global markets are repricing with the stabilisation, the question is whether the lower oil run is enough to contain the secondary effects already in train. There is some hope that China is pricing down oil-refining products and the chain pass-through softens. Hedge-fund net Brent shorts at a 10-year high near $18 billion say the consensus is already there.
The other and more important call is the Fed rate path. The new chair has signed up to pushing inflation back to 2%, or it is all talk. The market is smartly pricing the path front-loaded. The whole yield curve has flattened massively, two-year +13bp on the FOMC day, 30-year mortgage actually slipping into the rally, ten-year yields down 6-13bp last week as oil pulled the long end. If we are going to hike two to three times this year and hit terminal, is that USD bullish or USD bearish from here. Is it even so easy to call terminal. AI inflation is unstoppable. Apple has raised iPad and Mac prices 15-25% on memory chip costs and signalled iPhone moves next. Microsoft also raised consumer prices. The pass-through from AI capex into goods inflation is the persistent channel central banks cannot ease.
And then you have a small AI winter in the summer. It sounds unintuitive after a $7 trillion gain in world equity market cap year-to-date, but the SpaceX bond sale and the queue of LLM IPOs are scaring the markets a little. The Zhipu GLM-5.2 release one day after the Fable 5 takedown matches Mythos on the very benchmark the export control cited, and the open-weights model sits in every cloud now. The capex assumption is being repriced in real time, and the equity tape this past week, S&P -2%, Nasdaq -4.6%, Kospi -5.8% Friday, Nikkei -4.2%, is the first read on what that pricing looks like in volume.
A heavy four-day week sits in front of us, US closed Friday for Independence Day and the bond market closing early Thursday. The calendar is fully loaded into the short week. China official PMI Tuesday, Korea exports and the RatingDog PMI Wednesday, the BOJ Tankan Wednesday, the eurozone CPI cluster across Spain Monday and France, Germany and Italy Tuesday into the EZ flash CPI Wednesday. The Conference Board confidence and JOLTS Tuesday give the first US labour-market read, ISM Manufacturing and ADP Wednesday give the second, and NFP Thursday brought forward is the gate. BE 200k versus consensus 113k is a wide spread. Sintra in the middle of all of this, with Warsh chairing his first international panel at 14:00 Lisbon time Wednesday alongside Lagarde, Bailey and Macklem. The room is filled with chairs who built their reputations on transparency, watching one who deleted it. Worth flagging Tuesday Jun 30 also brings the MOF monthly FX intervention report covering the window through 26 June. The data report ends before last week's fresh 40-year USDJPY lows, which means any intervention this week would not surface in the official record until the end of July. The optics window is open, the incentive to act is slightly higher than the spot picture alone suggests.
The plan this week. The bigger move is short JPY crosses, EURJPY and AUDJPY, on Asia equity de-risking and the front-loaded Fed pricing. The risk-off reaction to a hawkish Sintra and a hot NFP carries the move. The USDCNH long is the best carry-vol upside trade, the DXY broken higher and the PBOC walking the fix back from CNY6.8166 toward the high side of the range, target the 6.82 break to 6.85 with a 6.78 trail stop, though hardly a straight line. AI profit-taking on Big Tech, tactical short Nasdaq against the 25901 conversion and 26085 base into Warsh and NFP, target the 24500 cloud bottom. Carry trades stay live across INR and IDR, oil exporters and importers basket continues to diverge. Zhipu's DeepSeek moment is the AI-capex tail. Stay nimble.
What did I learn last week?
Mon Jun 22: Canada May CPI +1.0% MoM, +3.2% YoY both hot. UK PM Starmer resigned, new Labour leader by September. Trump signed National Quantum Initiative Act EO, scientifically useful quantum computer mandate by 2028. US-Iran Hormuz mechanism set up via Switzerland.
Tue Jun 23: US June prelim S&P PMI Mfg 55.7 vs 54.6e, fastest output since July 2021 but fastest headcount cuts since pandemic. Treasury 2y auction tailed badly at 4.189% vs 4.071%. BOJ Summary of Opinions one member said neutral ~2%. EOG: 50% of Hormuz-shut production back in first month. FedEx beat Q4 $6.31 vs $5.91e. NVDA banned AI chips doubled on China black market to >$1.1M.
Wed Jun 24: US May new home sales 580k vs 640ke, big miss. Treasury 5y auction tailed at 4.200%. BOJ Tamura: need to raise rate every few months, neutral ~2%. Micron crushed Q3 $25.11 vs $20.98e, FY27 capex >$40B vs $27B prior, memory not catching demand until 2028. SK Hynix filed $29.4B Nasdaq ADR listing for July 10.
Thu Jun 25: IRGC attacked Singapore-flagged cargo ship off Oman. Iran proposed charging $40B/yr Hormuz "service fees". US Q1 final GDP +2.1% vs +1.6% prelim. Claims 215k vs 225ke. Atlanta Fed GDPNow Q2 cut to 2.5% from 3.0%. Apple raised iPad and Mac prices on memory costs, iPhone next. IBM unveiled sub-1nm chip technology. OpenAI considering 2027 IPO citing SpaceX volatility. Williams: delays 2% inflation target from 2027 to 2028.
Fri Jun 26: S&P -2%, DJIA +0.6%, Nasdaq -4.6% for the week. Nikkei -4.2% Friday, Kospi -5.8%. Israel-Lebanon framework confirmed. Trump threatened 100% tariff on European DST on US firms. VW may cut up to 100k jobs, spin off core passenger brand. Tokyo CPI ticked up to 1.7% the highest this year. Aug WTI off ~9% to near $69. DXY back at May 2025 highs. 10y yield fell ~13bp, post-FOMC flattening. USDJPY tested fresh 40-year lows.
What to look out for next week?
Sun Jun 28: Barkin at Aspen Ideas Festival. RBA Bullock at Per Jacobsson Lecture in Switzerland. BIS Annual Report. F1 Austrian GP. World Cup Round of 32 opens.
Mon Jun 29: Alphabet replaces Verizon in Dow at the open. Spain HICP 3.3e from 3.6%. ECB Forum opens in Sintra, Lagarde introductory remarks. US Supreme Court term-end decisions including birthright citizenship and Fed Lisa Cook ouster question. Burnham expected to give Labour leadership speech. China Commerce Minister visits Brussels. Wimbledon begins.
Tue Jun 30: Eurozone CPI cluster: France 2.3e, Italy 3.2e, Germany 2.5e. RBA meeting minutes. China NBS Mfg PMI 50.1e, non-mfg 50.1e. Colombia rate decision. Japan unemployment, IP. MOF Japan monthly FX intervention figures covering through Jun 26 (window ends right before USDJPY tested fresh 40-year lows). UK GDP. US Conference Board confidence 94.0, JOLTS 7.33M (290k drop). Nike earnings. Sintra: Vujcic, Lane, Elderson, Schnabel, Breeden speak.
Wed Jul 1: WARSH AT SINTRA PANEL with Lagarde, Bailey, Macklem at 14:00 Lisbon. EZ flash CPI 2.9e from 3.2%, core 2.4e from 2.6%. BOJ Tankan large mfg 17. Korea exports 62.5%e. China RatingDog Mfg PMI 52.0e. Indonesia CPI 3.6e. US ADP, ISM Mfg 53.5e, vehicle sales 16.0M. USMCA extension deadline. Japan triples international departure tax to ¥3,000. Ireland takes EU Council presidency.
Thu Jul 2: US NFP 200k BE / cons 113k / prior 172k, unemployment 4.3%. Initial claims 217k. South Korea CPI 3.2e. Switzerland CPI 0.5e. US bond markets close early ahead of July 4. SNB Financial Stability Report.
Fri Jul 3: US markets closed for Independence Day. China RatingDog services PMI. Eurozone services PMI. Turkey CPI 32.1e. Vietnam GDP/CPI. Lagarde, Nagel, Makhlouf, Bailey at Aix-en-Provence Forum.
All week: Warsh first international at Sintra Wednesday is the cross-asset gate. NFP Thursday brought forward. Burnham frontrunner for UK PM speaks Monday. OpenAI may delay GPT-5.6 to mid-July, DeepMind may push 3.5 Pro past month-end. World Cup Round of 32 continues. Wimbledon opens. The half-year close, second half opens with US economy resilient, AI tape under pressure, post-Powell Fed putting opacity to its first test.
Beyond next week
Jul 9: US reciprocal tariffs revert higher unless extended. Labour leadership nominations open.
Jul 10: SK Hynix US secondary listing, hoping to raise $29.4 billion.
Mid Jul: Earnings season opens — AI capex, consumer stress, memory pass-through tested in one cycle. BoC, BoE decisions mid-month.
Jul 19: FIFA World Cup final in the US.
Jul 23: ECB July decision — likely hold. Swap pricing another hike by year-end.
Jul 24: Section 122 10% tariffs expire unless renewed.
Jul 28-29: FOMC — futures price ~40% odds of an October hike. First test of post-Sintra Warsh.
Aug: UN funding cliff. Labour leadership contest to conclude by September.
Regimes
Warsh hawkish hold matures into the front-loaded path, the dollar is the carry receiver. First FOMC removed forward guidance, two-year +13bp, DXY broke to a new high since May 2025. The October-hike pricing is the live tape. The Sintra panel Wednesday is the first international stress test. evolved, week 2 under Warsh
G7 bear flattener accelerates, long-end catches an oil bid as the front backs up. Pay US short end. The 30-year mortgage rolled lower. The 2s-10s flattens from both ends as oil pulls the long and Warsh pulls the front. Same trade across UK, JGB, EU rates. evolved, week 8
AI capex regime moves to the absorption + revenue-attribution test. Tech equity sales hit $160bn in one month (Alphabet $85bn + SpaceX $75bn IPO). SpaceX bond losses already $360m vs Treasuries. JPMorgan capex through-2030 forecast up to $5.5T from $5.1T. Top-1% AI-token spend $7,448/mo vs $11 median says revenue distribution is brittle. evolved, week 10
Asia FX divergence narrows, the Korean and Japanese equity de-leveraging hits the FX leg. Kospi -5.8% Friday, Nikkei -4.2%. CNH +2.8% YTD still strongest in Asia. PBOC raised 1y MLF +5bp to 1.50% to support the bid. Local USD hoarders question turns into a margin question. evolved, week 5
UK political-fiscal regime breaks, the King-of-the-North campaign opens. Starmer resigned. Burnham frontrunner, has called for nationalisation and rejoining the EU. Labour nominations open July 9, new leader by September. Markets wary of who he names as finance minister. Gilts now carry political risk premium. new
Shifts (if → then)
If NFP prints over 180k with hot AHE Thursday → October hike pricing confirms, DXY extends, bear flattener accelerates through the 2-year, JPY crosses lower extends. new
If NFP undershoots cons 113k and AHE soft → curve eases, bear flattener pauses, the seasonal-weak window opens early, USD gives back, EM Asia FX can rally over the summer. new
If Warsh sounds dovish at Sintra Wednesday → September hike priced out, gold rallies, AI capex tape gets relief, USDCNH pulls back to 6.78. new
If Burnham speech Monday signals nationalisation push → gilts sell off, sterling under pressure, Labour leadership challenge accelerates, BoE held into a worse spot. new
If EZ flash CPI undershoots 2.9% Wednesday → September ECB hike priced out, euro pressured into Sintra panel, the divergence trade with Fed extends. new
If Zhipu parity claim holds on broader tasks → AI-capex assumption repriced harder, US frontier-model premium compresses, capex supplier rotation extends. new
If oil tanker attacks in Hormuz escalate → oil re-prices the deal-risk premium, the bear-shorts get covered, secondary inflation effects re-enter the rate path. carried
Tails
Bear flattener accelerates into forced deleveraging → positioning wrong-footed across G7 rates books, the curve shifts violently. Warsh the catalyst at Sintra. week 4, evolved
Hormuz physical reopening lags the MOU headline → IRGC fires at Singapore-flagged ship Thursday, Trump calls it foolish but takes no action. EOG sees 50% back in first month and 90-95% in 3-4 months. week 13
JPY intervention returns with US Treasury cooperation this time → USDJPY tested fresh 40-year lows last week, dollar puts being bought as polls of capital buy intervention insurance. BOJ rate hike delivered, US may be more supportive. The MOF FX intervention report Tuesday Jun 30 covers data through Jun 26, so any action this week would not surface until end-July, the optics window is open. week 4, evolved
AI capex bubble pops → SpaceX bond losses at $305m within days. Hyperscaler FCF compressing on capex. Top-1% token spend points to brittle revenue distribution. Cerebras as a public company missed first. week 4, evolved
UK political instability bleeds into gilts and sterling → Sixth PM in a decade. Burnham frontrunner with calls for nationalisation. Government borrowing in May highest since pandemic. week 1, new
China weaponises rare earths and magnets further → No tungsten exported to Japan since start of year. G7 only targeting 60% reduction by 2030. Refineries take years not quarters to build outside China. week 1, new
Super El Niño into 2027 → NOAA probability ramp to majority Very-Strong from Sept. The agricultural inflation channel reopens at exactly the moment headline numbers were supposed to cooperate. week 2, carried
Manic Monday
Asia opens with the Alphabet-replaces-Verizon Dow rebalance live at the US open Monday. India IP and Japan retail sales early Singapore morning. Spain HICP 8am London the first of the eurozone CPI cluster. UK mortgage approvals through the morning. Eurozone economic and consumer confidence pre-noon London. The Sintra Forum opens with Lagarde’s introductory remarks. US Supreme Court issues final decisions of term including birthright citizenship and the Fed Lisa Cook question. Burnham speech the same day, markets wary of the Labour leadership opener. Quiet calendar in New York. Dallas Fed survey 10:30am EST a small flag.
Turnaround Tuesday
China NBS PMI 9:30am Singapore the Asia anchor. Japan IP +2.0% MoM, Korea IP +0.3% MoM. Australia home prices late Singapore evening. France CPI 2.3e the second print of the eurozone cluster, Germany 2.5e, Italy 3.2e. Sintra panel day one: Vujcic, Lane, Elderson, Schnabel speak. US Conference Board confidence and JOLTS 10am New York. Case-Shiller home prices 9am. Colombia rate decision late New York. Nike earnings post-close. Colorado primary.
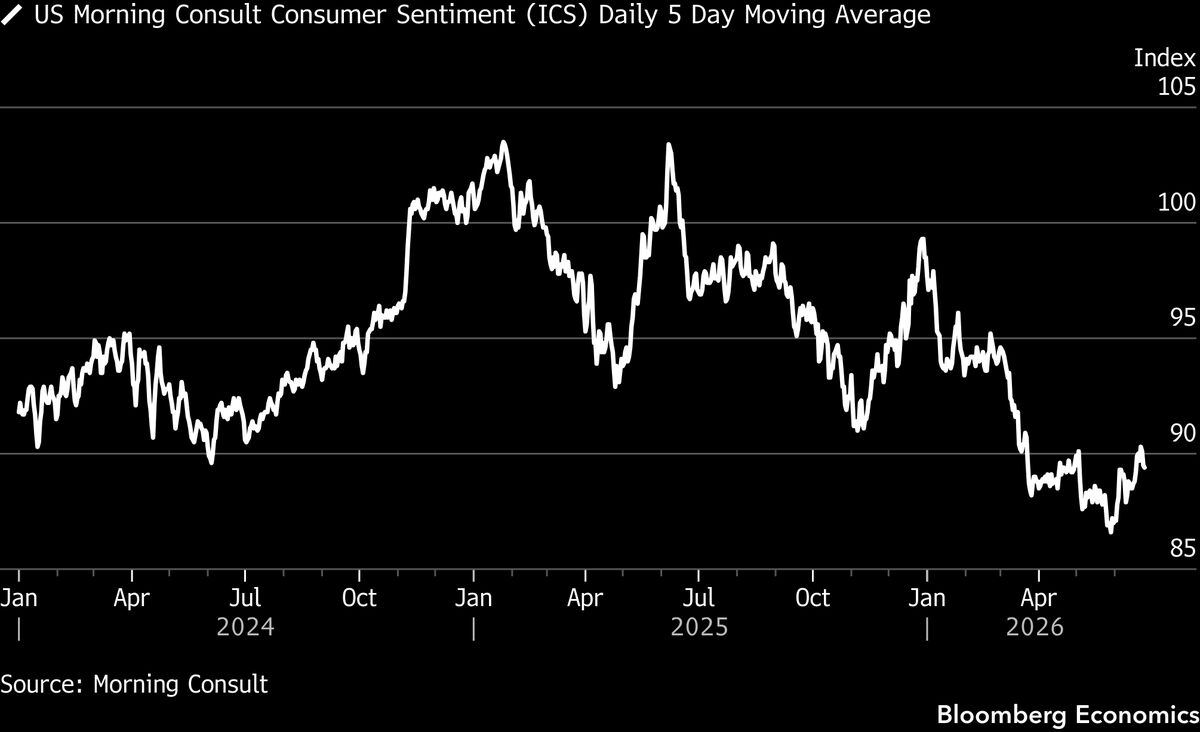
Consumer Confidence Tuesday — likely lifted to 94.0 from 93.1 on the post-MOU oil pullback and easing fuel costs at the pump. Geopolitical de-escalation is the headline driver, even though the strait closure is not fully behind us. The labour market remains the anchor, but elevated gasoline still weighs on the lower-income confidence segment. The print sets up Conference Board sentiment ahead of NFP Thursday. Source: Bloomberg Economics.
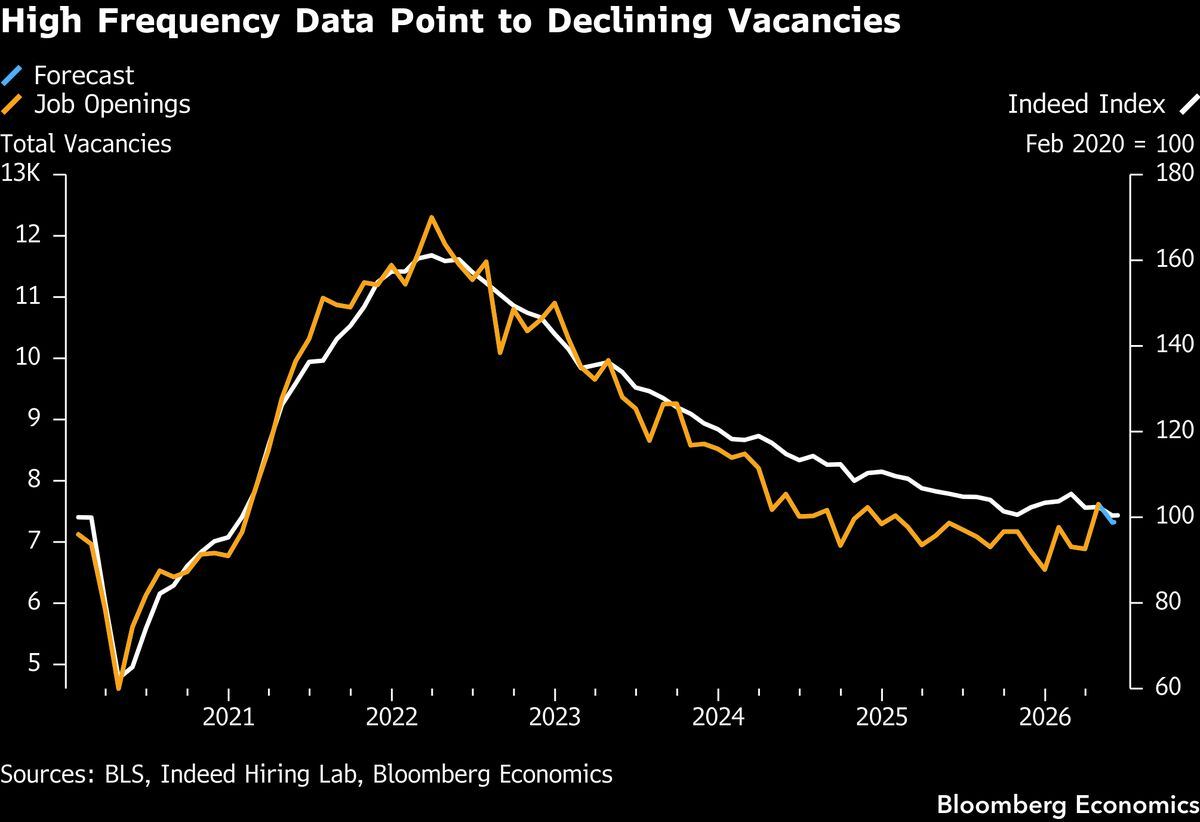
JOLTS Tuesday — vacancies likely dropped 290k to 7.33M in May. The fall is concentrated in larger firms reporting lower hiring intentions late in the month. The quits rate flutters around 2.0%, with worker turnover doing little to lift wages. Layoff and discharge rate may tick back up to 1.2% from the May jobless-claims pickup. Still inside an above-1.0 vacancies-per-unemployed reading. Source: Bloomberg Economics.
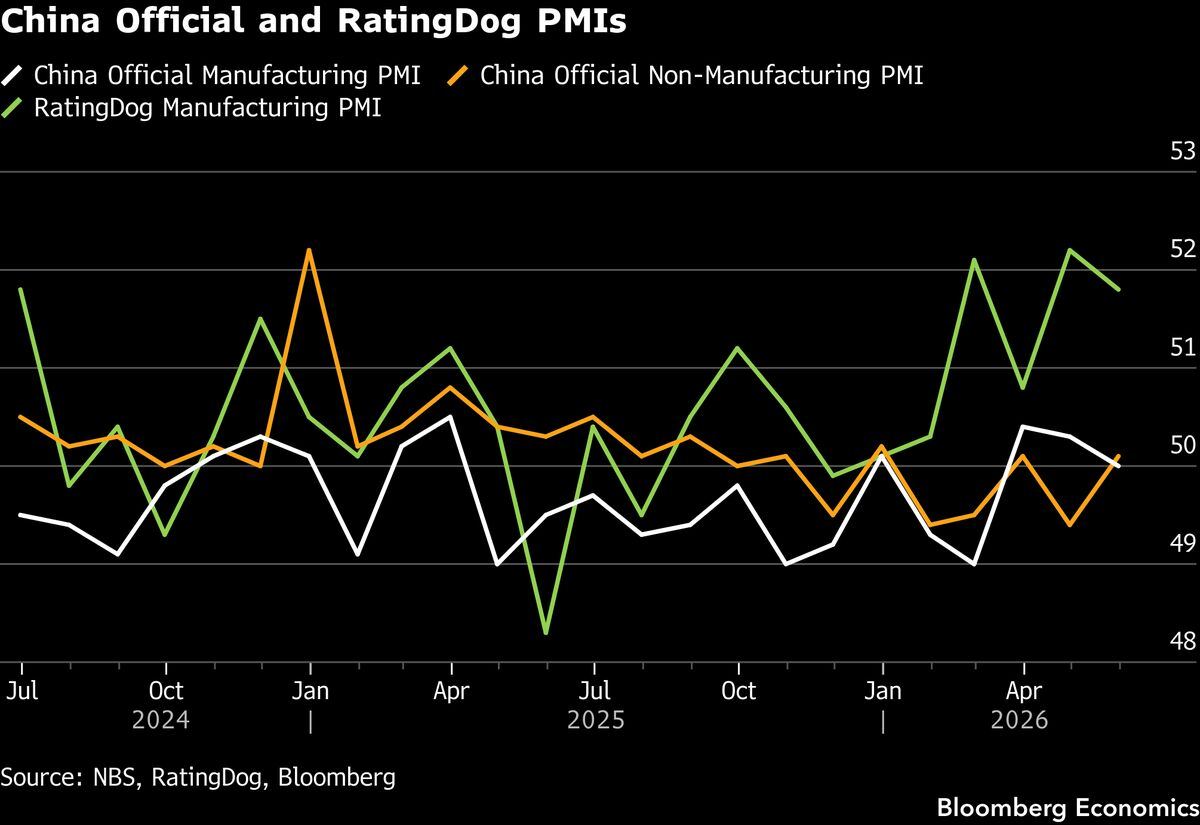
China official manufacturing PMI Tuesday — likely 50.1 from 50.0, the headline barely in expansion. The two-speed economy persists, external demand the bright spot on AI-tied goods, domestic demand soft, housing sales stalled after a brief recovery, discretionary big-ticket spending subdued. The non-manufacturing PMI likely holds at 50.1. Source: Bloomberg Economics.
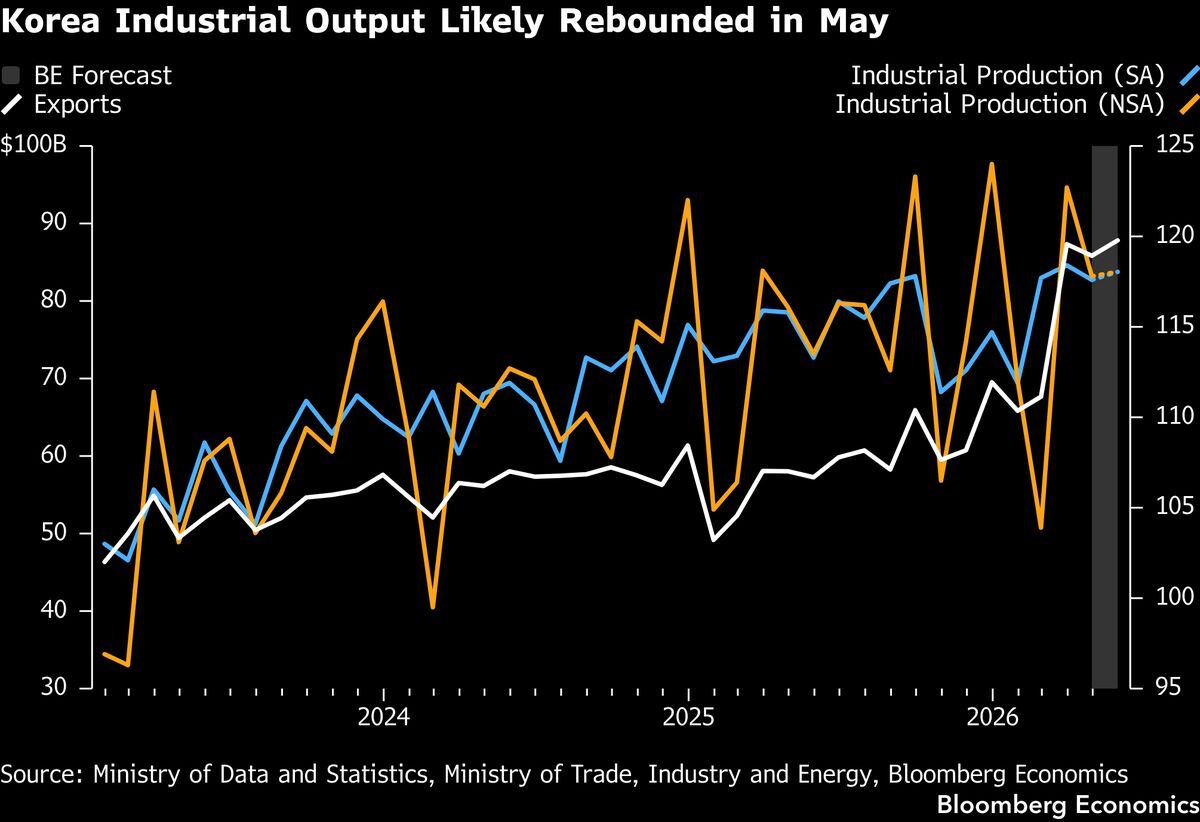
South Korea industrial production Tuesday — likely +0.3% MoM as the Iran-war energy disruptions ease. Petrochemicals and refining recover from the crude and naphtha shortages. Semiconductor exports still booming (+169% YoY chip shipments) but moderated from April's +173% as production lines retool. Auto production still weak. Year-on-year IP +4.0%, accelerating from +1.5%. Source: Bloomberg Economics.
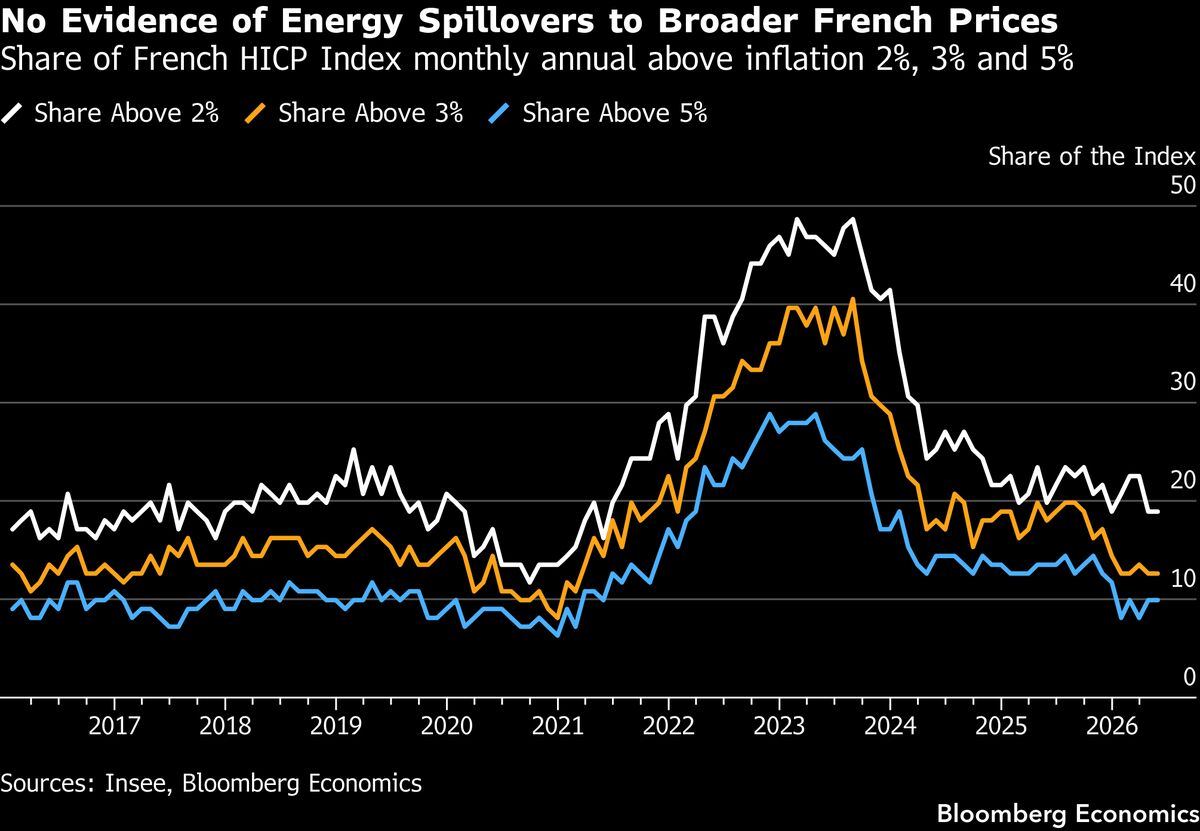
France CPI Tuesday — likely fell to 2.3% from 2.8% on a base effect from a longer sales period this year and lower fuel pump prices since the US-Iran peace progress. No broadening of inflation across the index, sentiment data shows price pressures cooling since late May. Monthly figures expected to grind higher through year-end, averaging 2.2% for the year. Source: Bloomberg Economics.
Waiting Wednesday
The Warsh panel Wednesday is the cross-asset gate of the week, 14:00 Lisbon, alongside Lagarde, Bailey and Macklem. BOJ Tankan 7:50am Singapore opens Asia. Korea exports the AI-chip read, BE +62.5% YoY. China RatingDog 9:45am Singapore, BE 52.0 from 51.8. Indonesia CPI lunchtime. Eurozone flash CPI 10am London, BE 2.9% headline / 2.4% core. US ADP, ISM Manufacturing BE 53.5, vehicle sales and construction spending through New York morning. USMCA extension deadline ticks at midnight.
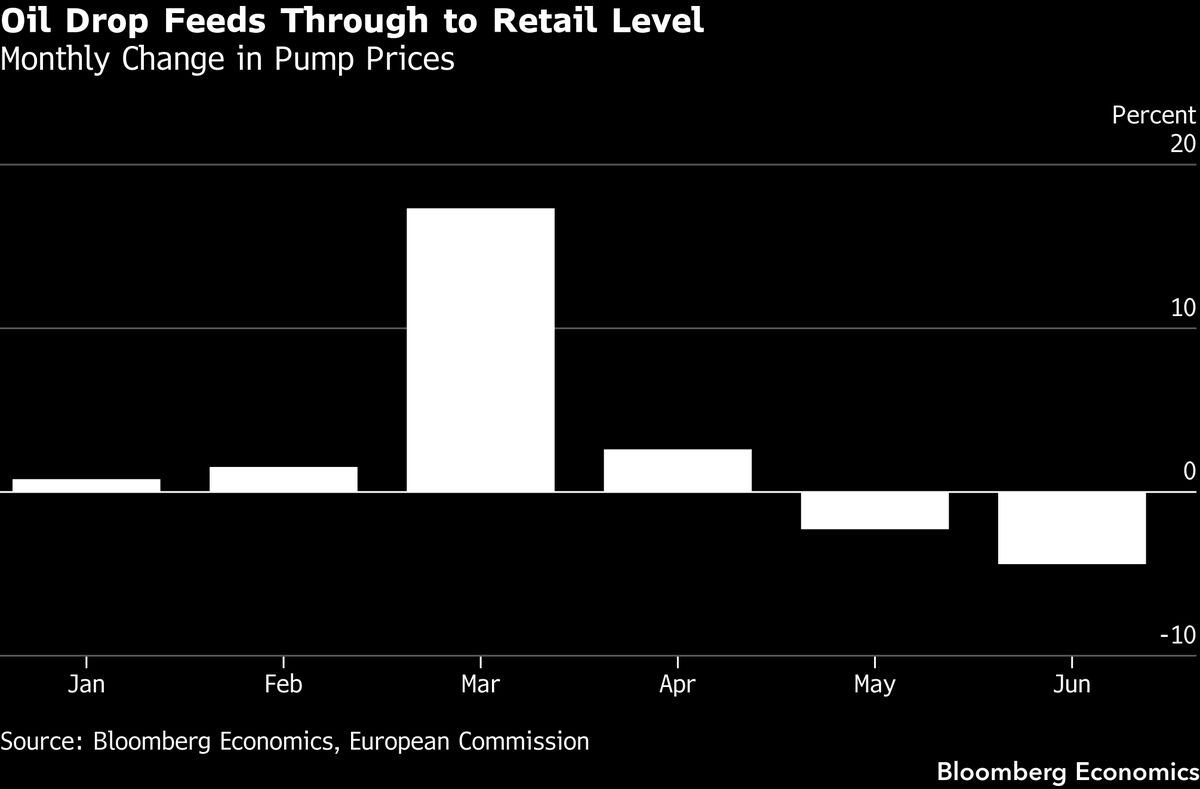
Eurozone flash CPI Wednesday — likely 2.9% from 3.2%, core 2.4% from 2.6%. Fuel costs the largest pull on headline. The rise of restaurant and hotels prices last year creates a base effect lowering core. Headline lower than the ECB staff economists' baseline of 3.0%. If the commodity-price decline triggered by the MOU is sustained, the risk to the September-hike call shifts to the downside. Source: Bloomberg Economics.
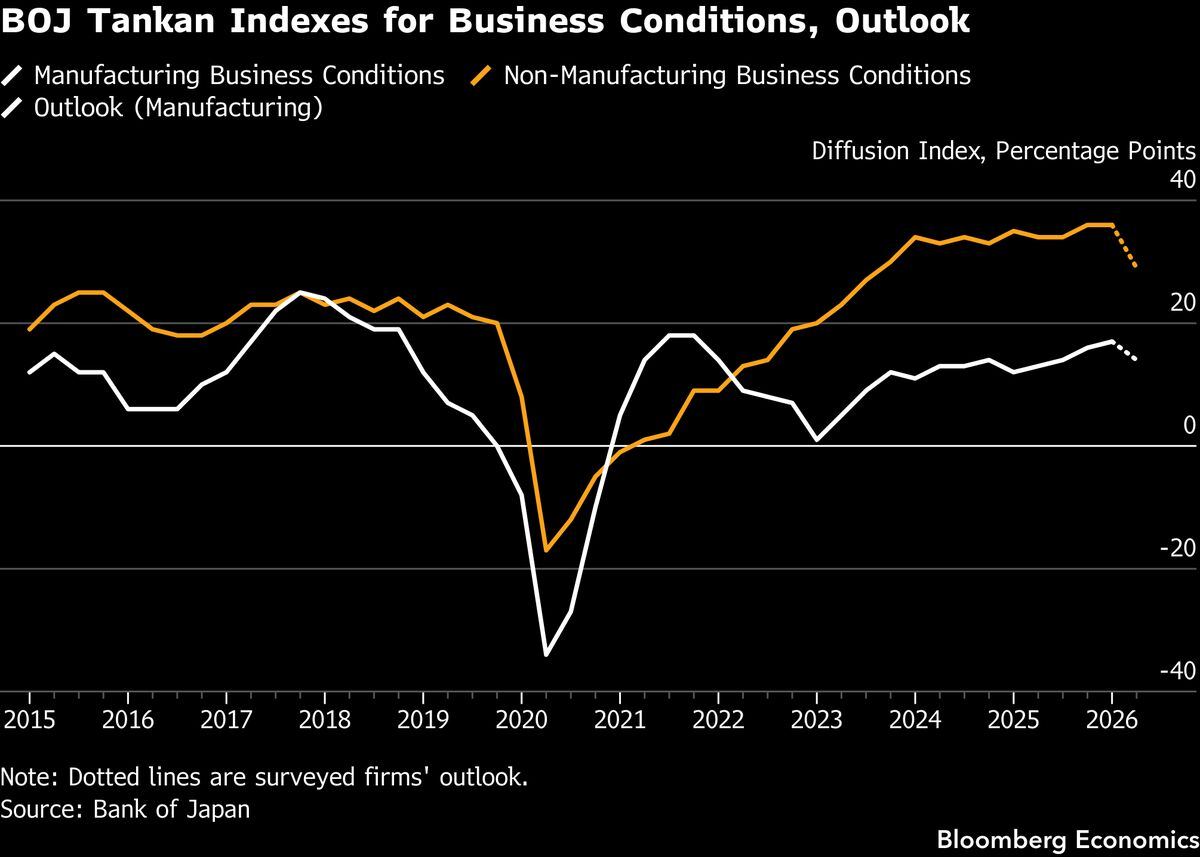
BOJ Tankan Wednesday — large manufacturers' index likely holds at 17. Solid auto and AI-related demand offsetting higher energy costs. The non-manufacturers' gauge ticks up to 37 from 36. Price gauges should point to firmer inflation momentum driven by higher energy and labour costs, with five-year-ahead inflation expectations climbing further above the 2% target. Another signal for the BOJ to continue paring stimulus. Source: Bloomberg Economics.
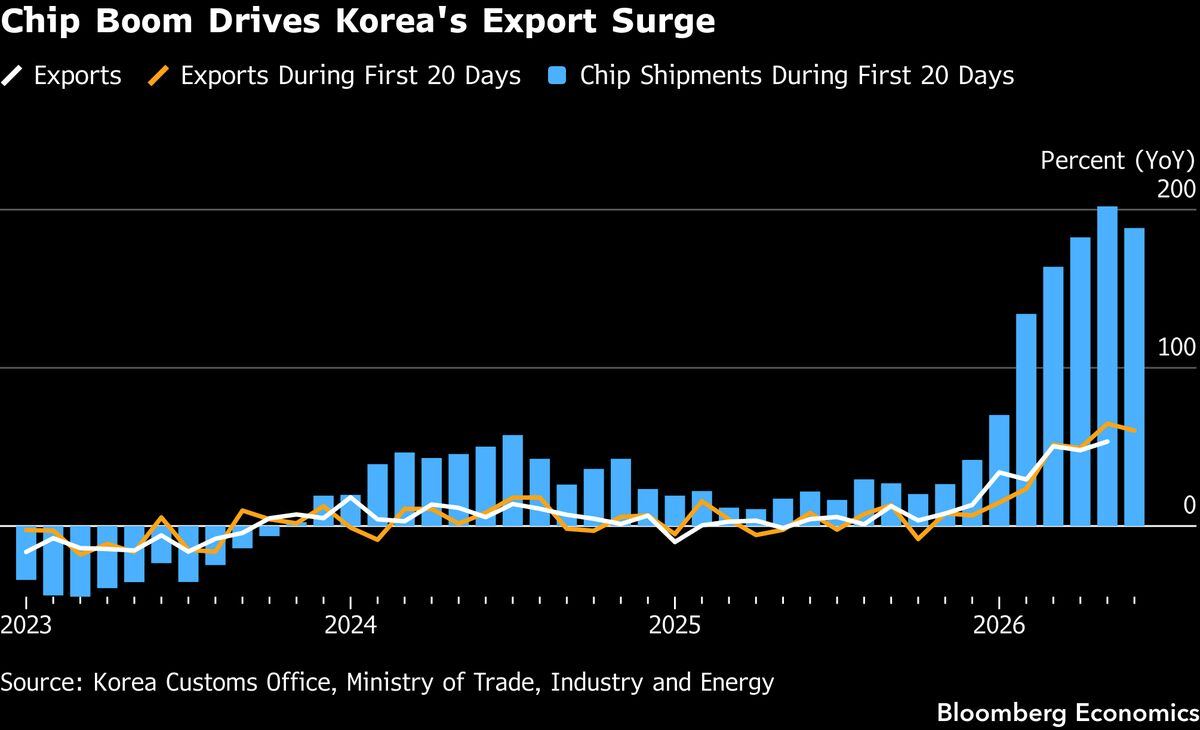
South Korea exports Wednesday — likely +62.5% YoY in June, propelled by AI-chip demand. Chips +188% in the first 20 days of June, computer peripherals +293%, refined petroleum +39%. Trade surplus widens to $34B from $27B. The leading indicator for the entire Asian AI hardware export complex. Source: Bloomberg Economics.
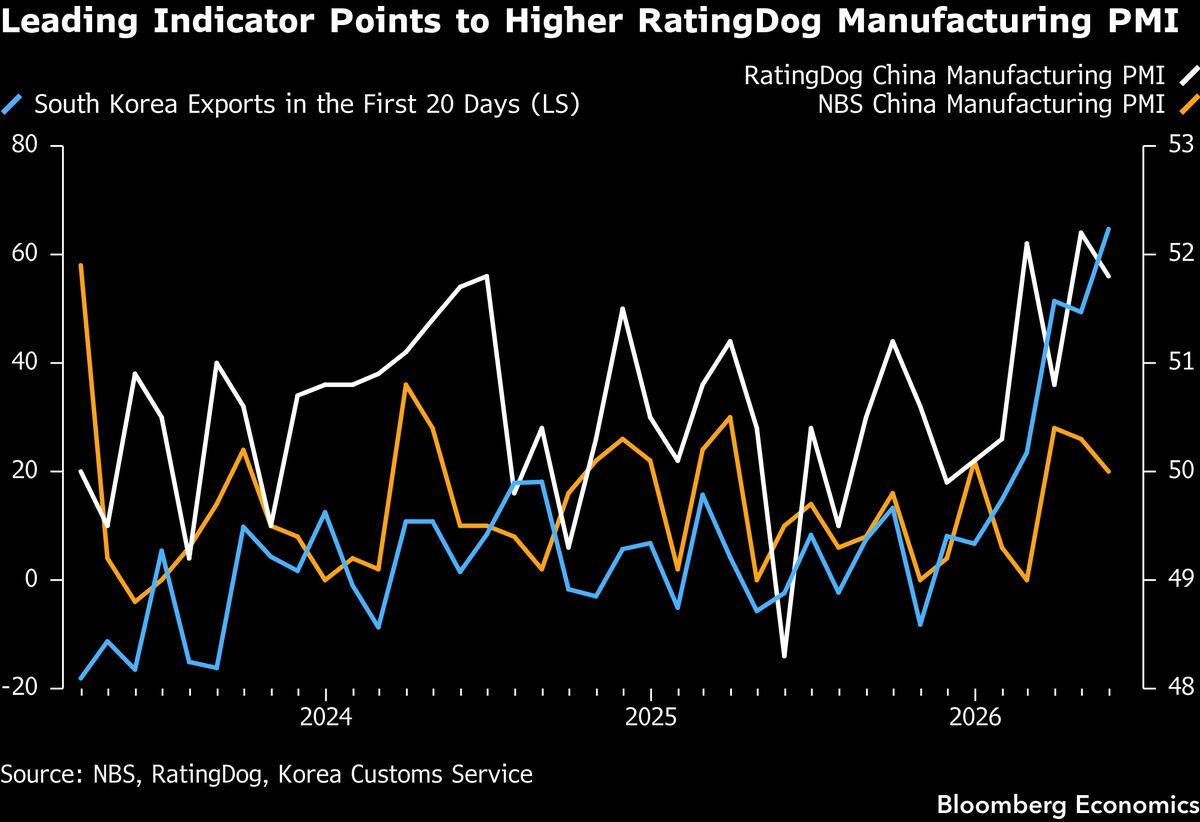
China RatingDog manufacturing PMI Wednesday — likely 52.0 from 51.8, the export-oriented gauge climbing further into expansion. High-frequency indicators flag a pickup in IP as oil supply improves and weekly port data points to continued export growth, mostly AI- and tech-related. The reading is the leading indicator for Asia industrial momentum. Source: Bloomberg Economics.
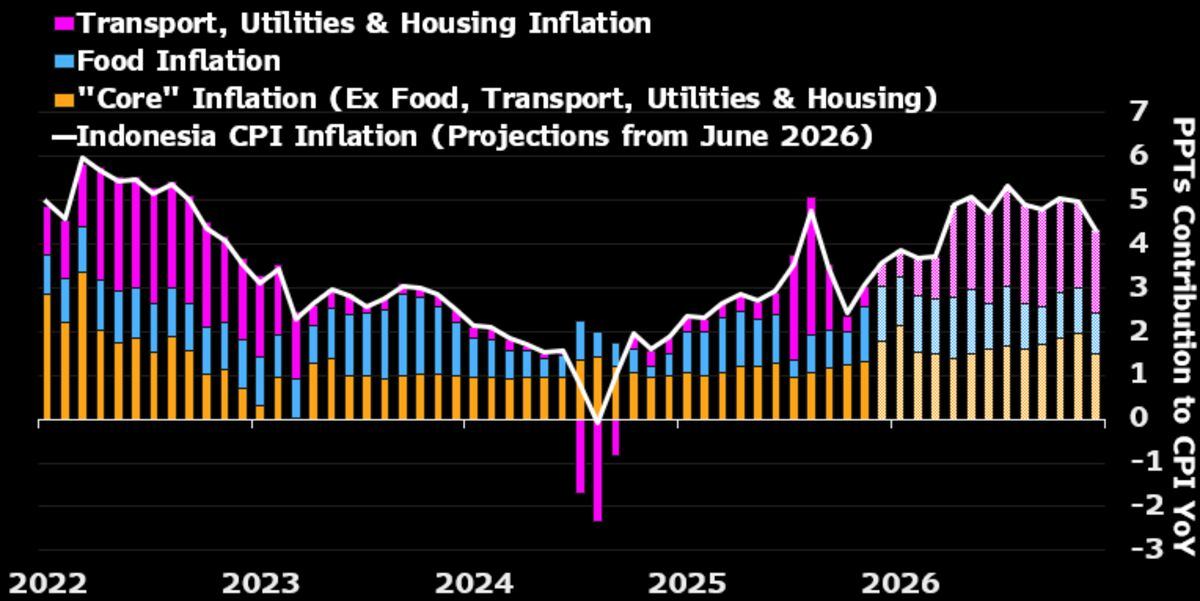
Indonesia CPI Wednesday — likely 3.6% from 3.08% as the oil shock pass-through builds. Inflation likely climbs further above the central bank's 1.5-3.5% target in the second half. Oil prices retreated but the earlier spike still works its way along the global supply chain. The rupiah weakness adds to imported-goods cost. Source: Bloomberg Economics.
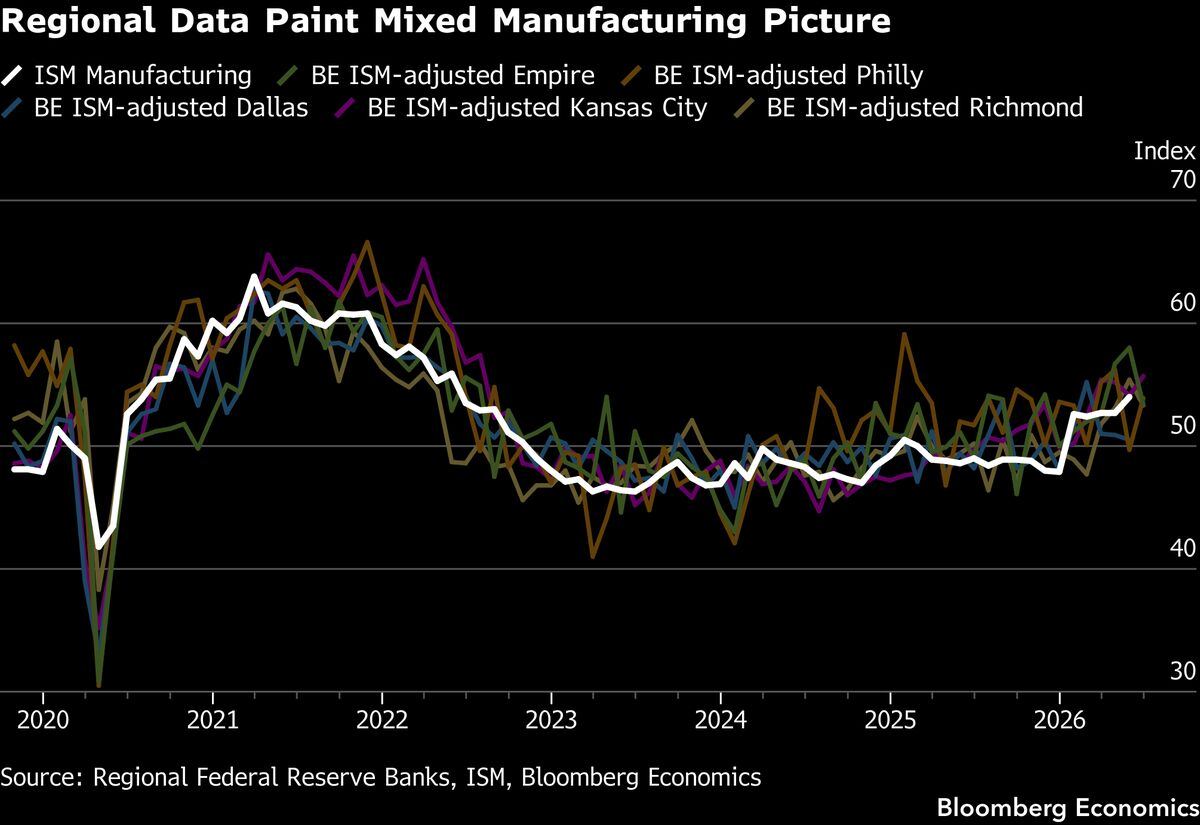
ISM Manufacturing Wednesday — likely 53.5 from 54.0, a modest tick down. Regional Fed surveys are mixed — half showed orders and shipments increasing in June, half not. Inventories declined per most regional data, weighing on the PMI. Supplier deliveries the swing factor, with less supply-chain stress now weighing. Declining energy prices likely soften pipeline price pressures. Source: Bloomberg Economics.
AI Winter in Summer
Before NFP Thursday, the equity tape leftover from last week. Tech equity sales hit $160bn in one month between the Alphabet $85bn share sale and the SpaceX $75bn IPO. SpaceX bond losses crystallised by Friday at $360m versus Treasuries. JPMorgan now expects $5.5T of AI/data-centre capex through 2030 from $5.1T in November. Apple raised iPad and Mac prices 15-25% on the memory shock. Microsoft also announced consumer price increases. The Big Tech free-cash-flow chart making the rounds is a capex investment story, not a deterioration story, but the bond pile sitting against it has decades of obsolescence risk attached. Top 1% of corporate AI-token users spend $7,448 a month, the median $11, a brittle revenue distribution. Brent hedge-fund net shorts at a 10-year high near $18bn say the oil-bear is already a crowded carry. Alphabet replaces Verizon in the Dow at the Monday open, the flagship US equity index now five-of-seven Magnificent Seven. The other half of the S&P 500, Intuit -60% YTD, CoStar -55%, Boston Scientific -54%, is what AI is doing to the old guard quietly while the indices argued about the new.
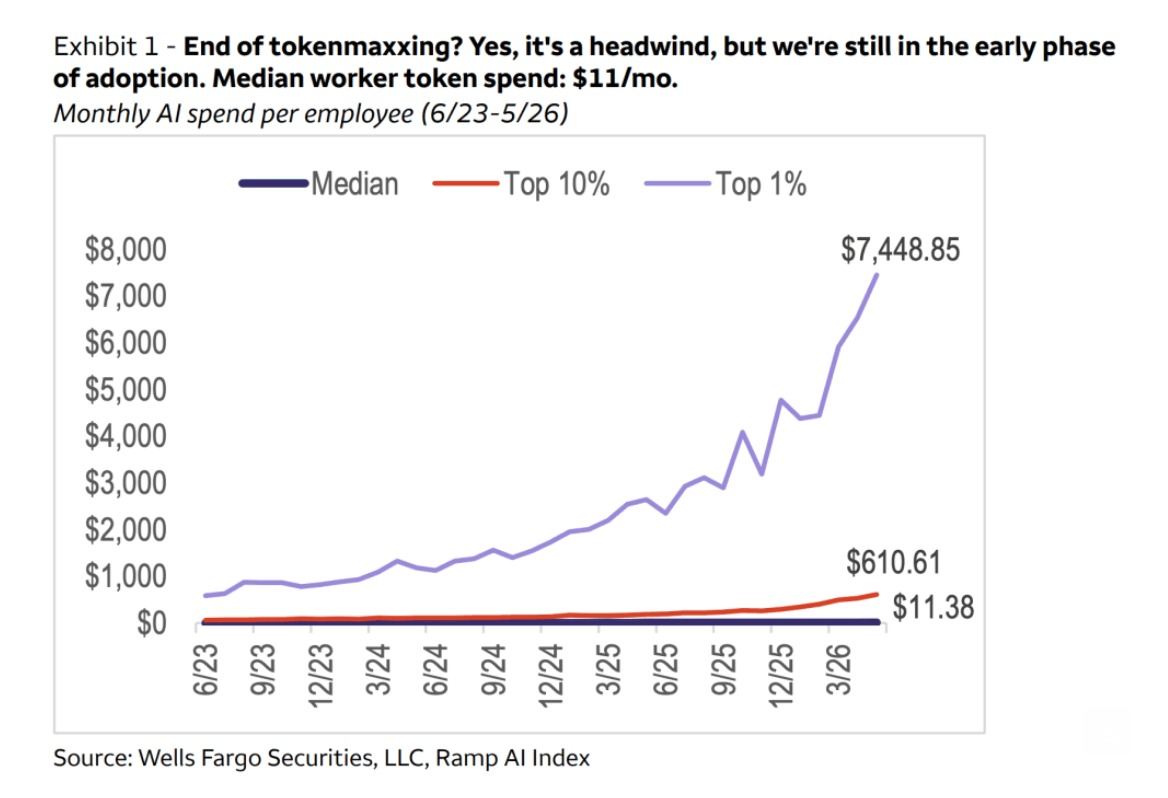
$7,448.85 per month — the average AI token spend of the top 1% of corporate users. Top 10% average $610. Median $11.28. AI token prices face downward pressure as companies start asking how much bang for their bucks. The chart is the early signal that the AI revenue-per-token assumption underwriting hyperscaler bond piles is overstated. Source: Wells Fargo Ohsung Kwon / Visual Capitalist.
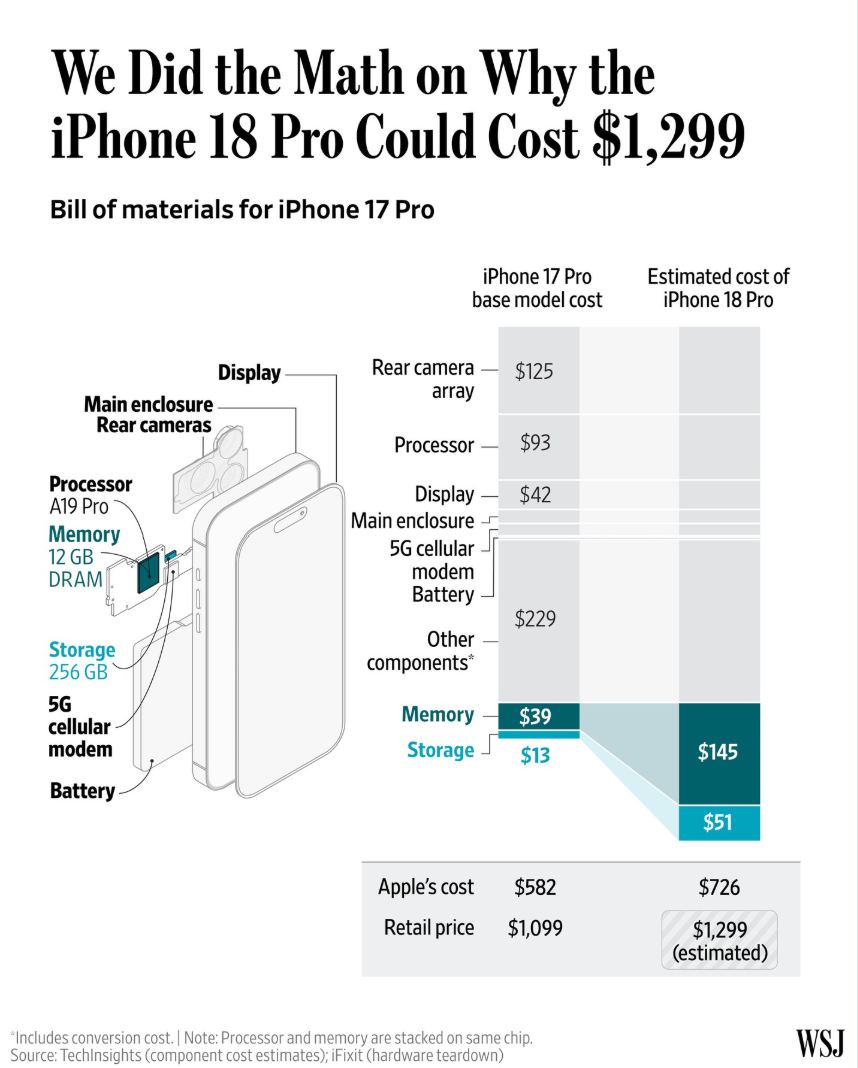
Apple raised Mac prices 15-20% and iPad prices 15-25% on memory-chip costs Thursday. iPhone prices unchanged so far. iPhone 18 Pro analysis from TechInsights points to base-model price up by $200 or more. Microsoft also announced consumer-product price increases the same week. The memory shock is now consumer-facing across the AI hardware stack. Source: Instagram.
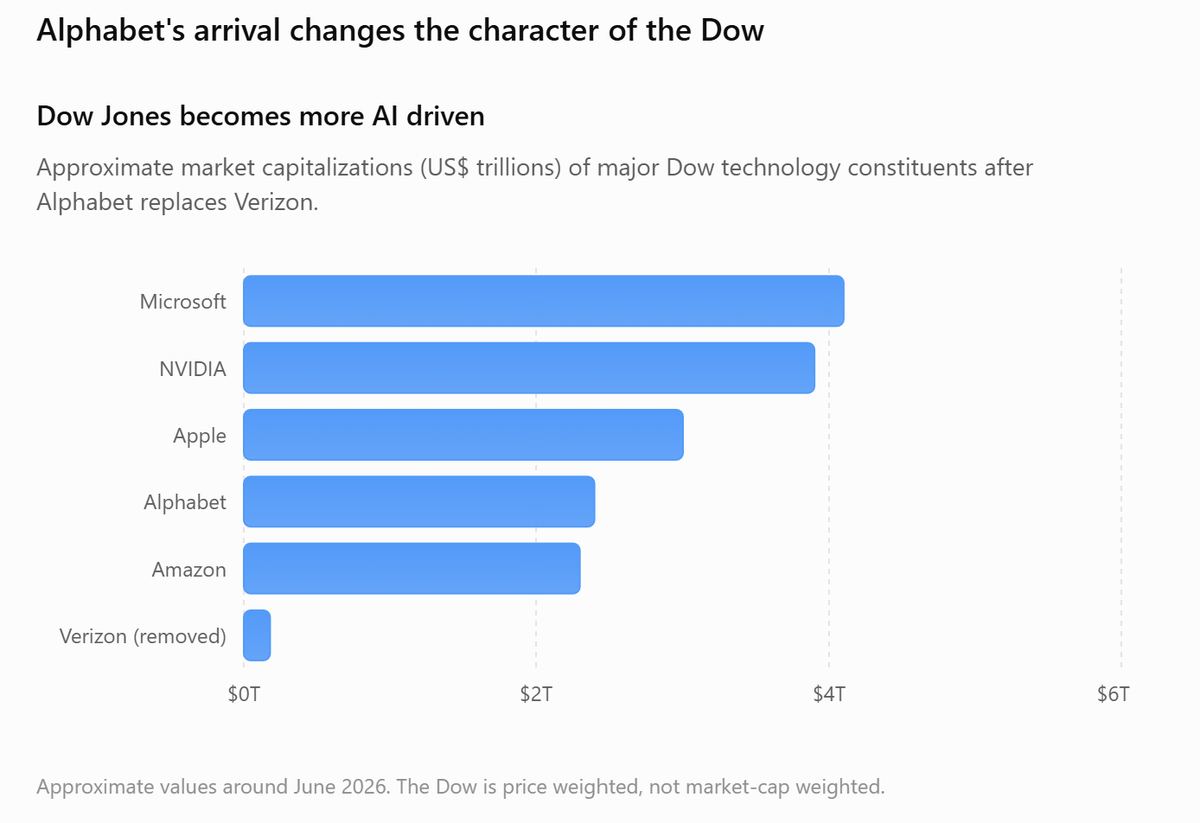
Dow Jones 2026 — Alphabet replaces Verizon at the open Monday. Intel out for Nvidia. Dow Inc out for Amazon. Five of the Magnificent Seven now sit inside the Dow (Apple, Microsoft, Amazon, Nvidia, Alphabet). The flagship US equity index has quietly transformed into an AI index over two years, legacy industrial and telecom names giving way to cloud and AI leaders. Source: Instagram.
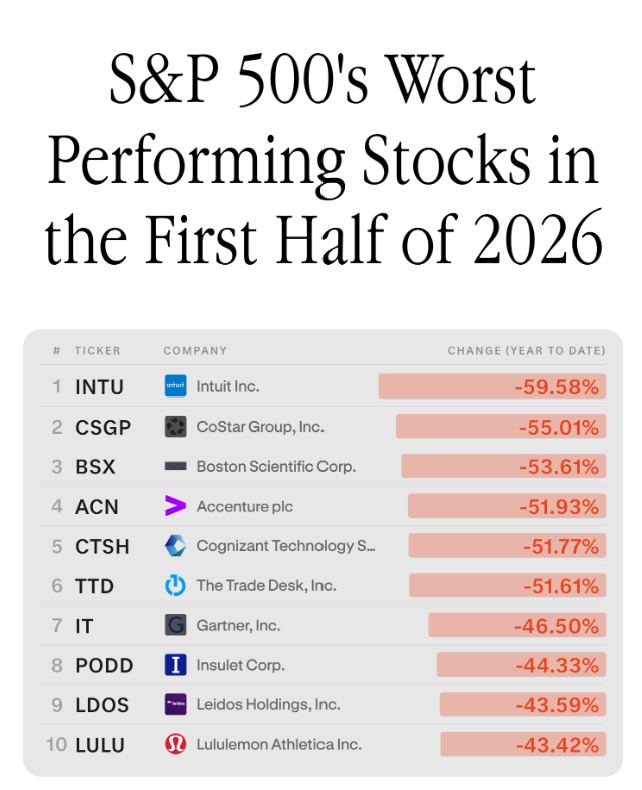
S&P 500 worst H1 2026 performers — Intuit -60%, CoStar -55%, Boston Scientific -54%. AI continues to reprice the old guard. Accenture, Cognizant, The Trade Desk each fell more than 51% as data monetisation and B2B shift in the AI age. Lululemon, Insulet, Leidos and Gartner rounded out the bottom. The other half of the equity story under the AI-tape strength. Source: Instagram.
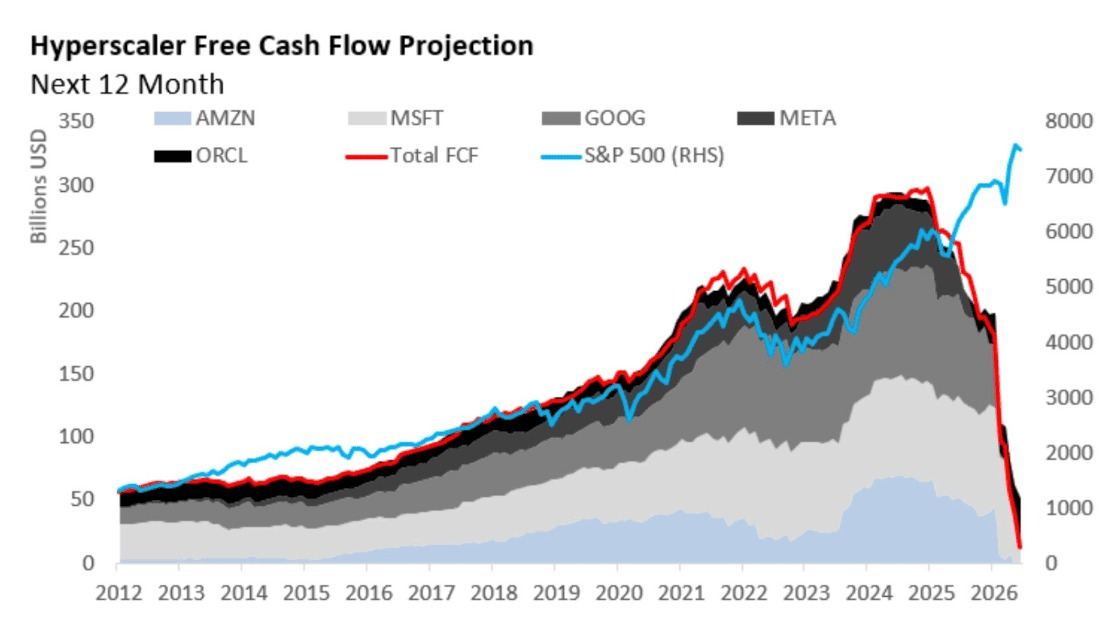
The Big Tech "free cash flow problem" is actually a capex investment story. Free cash flow falling because AI capex is exploding, not because the underlying businesses are deteriorating. Revenue still grows, operating cash flow still grows, margins still exceptional. Amazon ran the same playbook in the 2010s building AWS. The real question is not whether FCF is falling, it is whether the AI investment earns attractive returns over the next five to ten years. Source: Visual Capitalist.
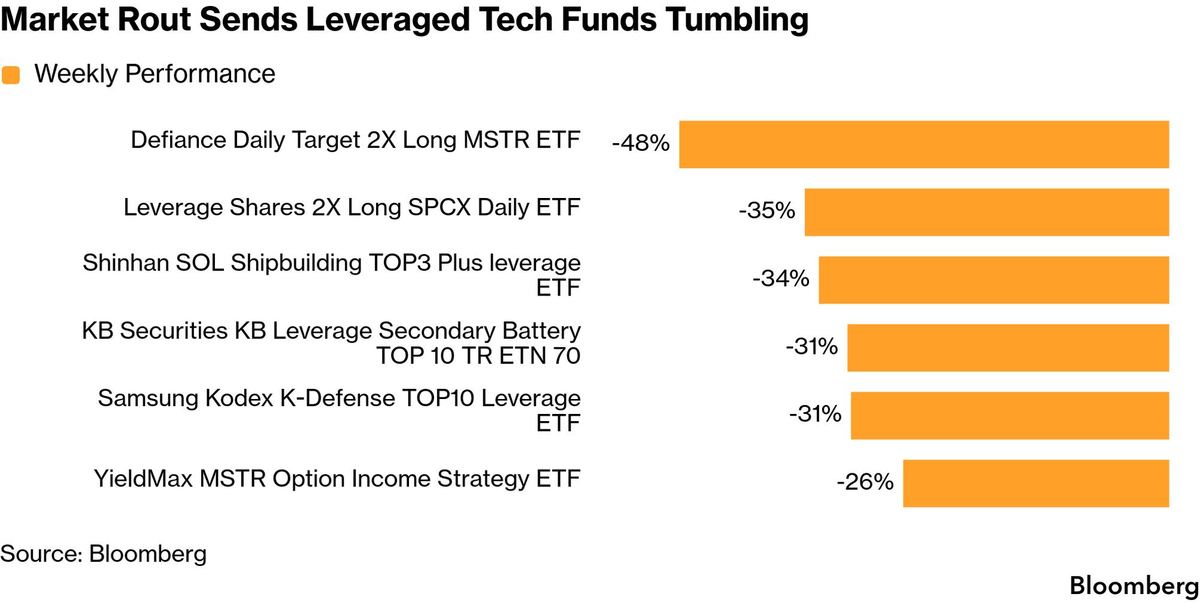
SpaceX bond losses mount — paper losses ~$305M as of late Thursday relative to Treasuries. Fast-money accounts piled in to flip the deal. The selling stands out because the equity has largely stabilised since the bonds priced Tuesday. The investment-grade rating was awarded despite years of negative cash flow expected. Bondholders are taking decades of obsolescence risk for the AI bet. Source: Bloomberg.
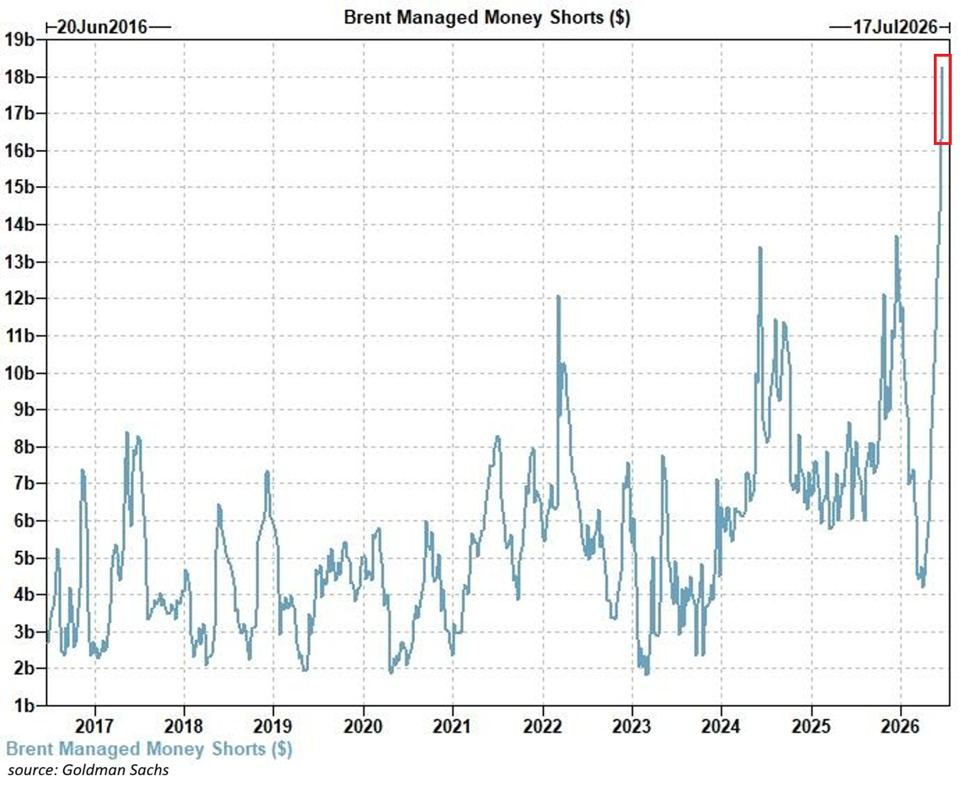
Hedge fund net short Brent positions at a 10-year high near $18B. Tripled in three months. $7.5B sold week to 16 June, the largest weekly sale since April 2025. New shorts accounted for 80% of total sales — fresh bearish bets rather than long-unwinds. Seventh consecutive weekly sale totalling $24.8B. The crowded-short signal in the oil tape. Source: Kobeissi Letter.
TP Thursday
NFP Thursday brought forward by a day on the July 4 holiday is the gate of the week. BE 200k versus consensus 113k is a wide spread. Korea CPI early Singapore morning likely 3.2% YoY, further above the BoK 2% target. Switzerland CPI 7:30am London likely 0.5% from 0.6%. Bond markets close early ahead of the holiday weekend, liquidity dies down through the New York afternoon. BOE Mann at Natixis. The day to take profit on the bear-flattener trade ahead of the long weekend.
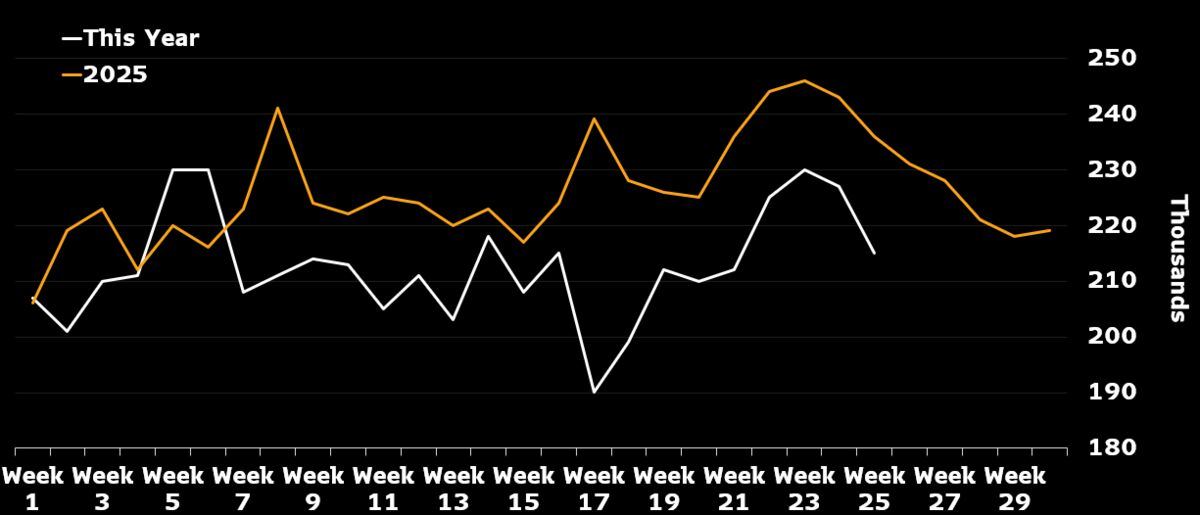
Initial jobless claims Thursday — likely 217k. Continuing claims data signals stable labour-market conditions. Employment remains a secondary concern for Fed officials focused primarily on inflation. The print stays significantly below the 231k comparable week of 2025. Source: Bloomberg Economics.
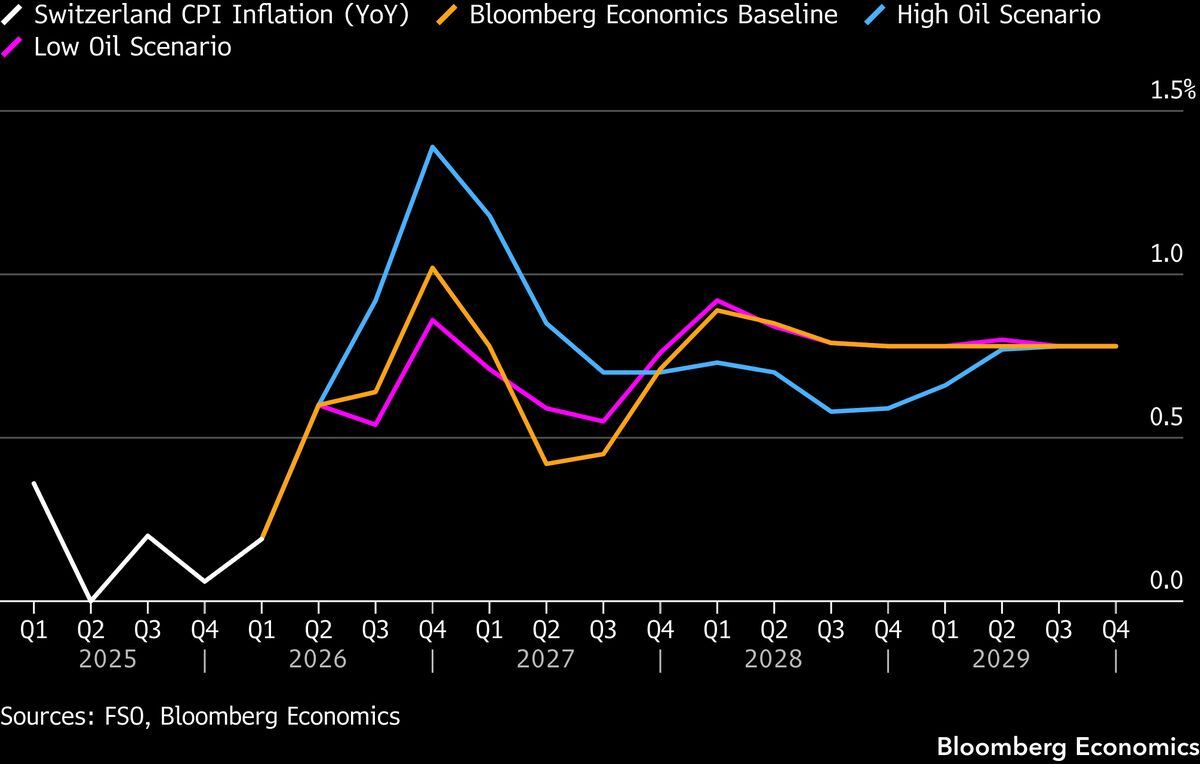
Switzerland CPI Thursday — likely 0.5% from 0.6%. The pass-through from higher oil prices slows as commodity prices fall on US-Iran peace progress. A weaker franc could dampen the impact. Negative base effects also weigh on restaurant and recreation prices. The SNB story is still negative-rate-risk if oil collapses further. Source: Bloomberg Economics.
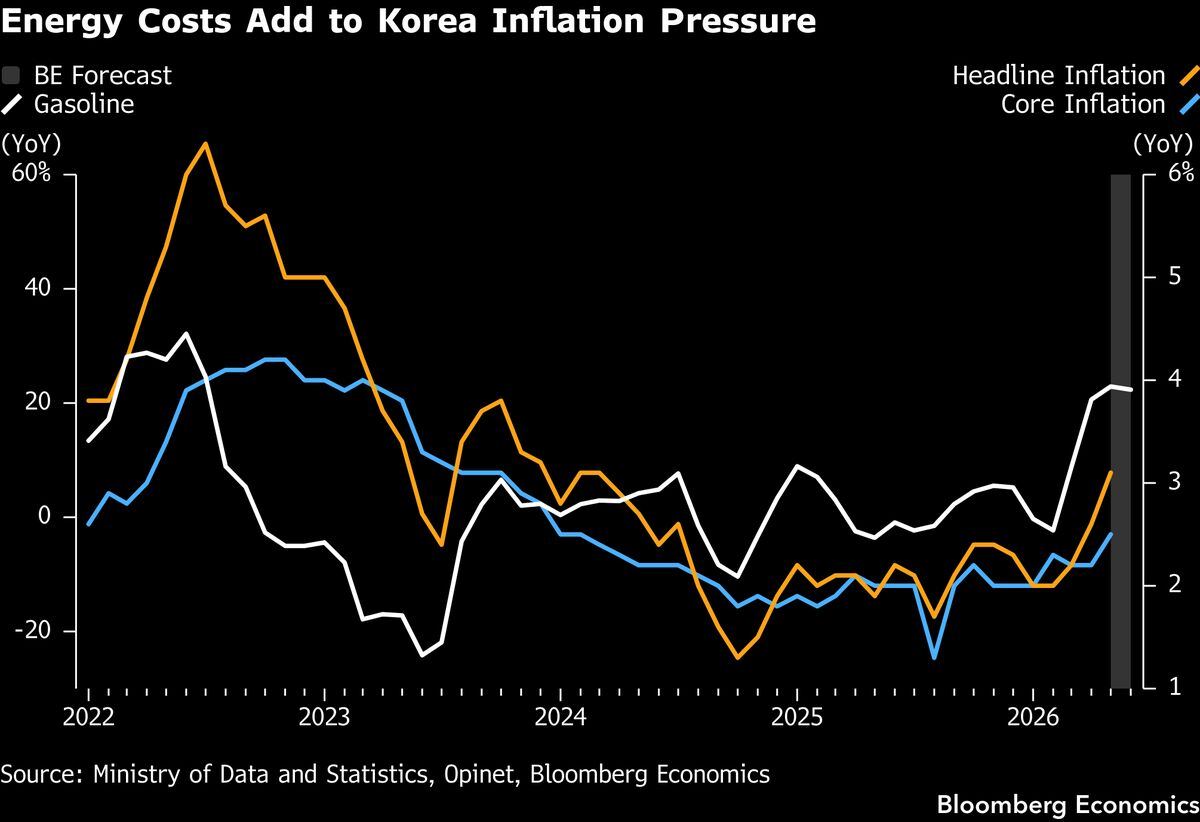
South Korea CPI Thursday — likely 3.2% from 3.1%, further above the BoK's 2% target. Higher oil costs continue to feed through despite lower crude as retail fuel prices remain elevated under the fuel-price cap. Core +2.6% from +2.5%. The BoK expected to begin raising rates in July with another hike in Q4, taking the base rate to 3.0%. Source: Bloomberg Economics.
Friday Fade
US closed for Independence Day. Light calendar. China RatingDog services PMI early Singapore morning. Eurozone services PMI through London. Turkey CPI likely eased to 32.1%. Vietnam GDP, CPI and trade through Asia. Lagarde, Nagel, Makhlouf and Bailey at the Aix-en-Provence Economic Forum, Colombia monetary policy minutes the late session. A quiet end into the half-year close and the long US weekend.
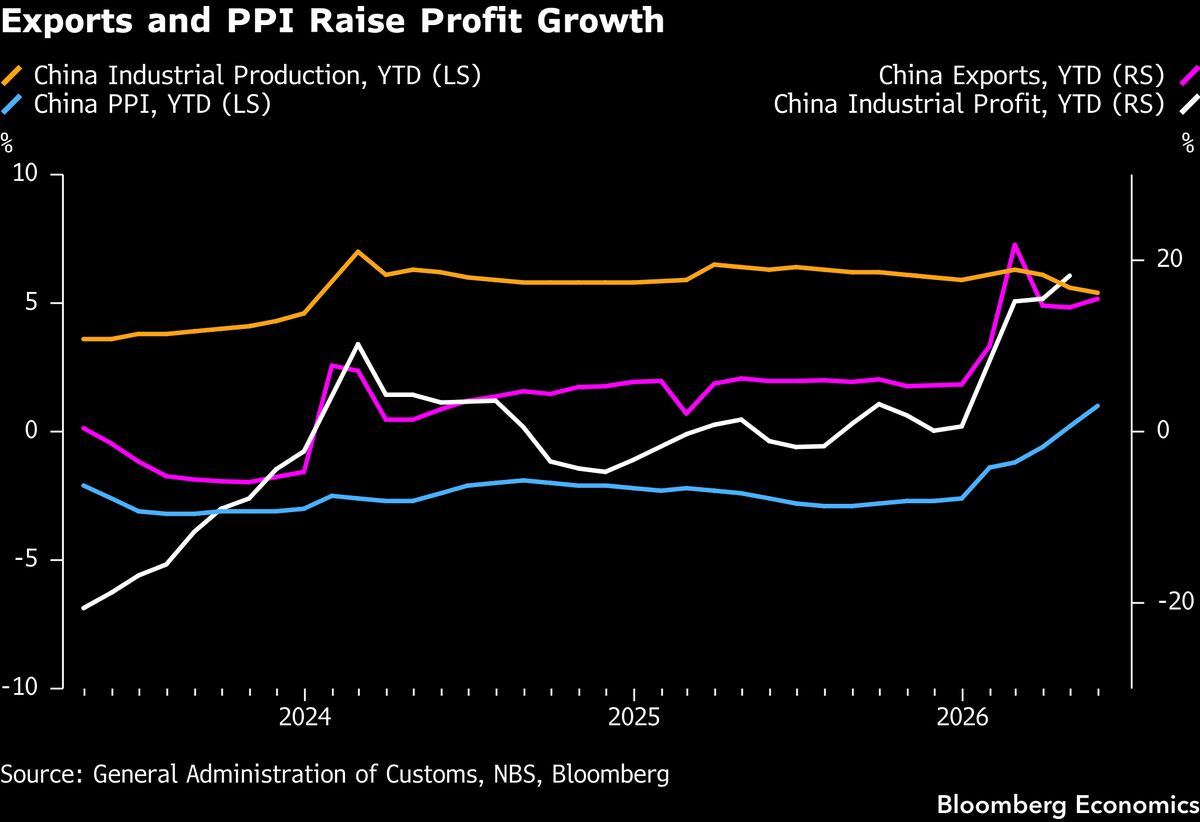
China industrial profits — likely +19.0% YTD YoY in the first five months from +18.2% in the first four. PPI accelerated to +3.9% YoY in May from +2.8% in April. The AI-tied exports propel earnings in tech and materials sectors. Slowdown in IP and sluggish domestic demand offset by the export boom. Source: Bloomberg Economics.
VC+ Special Dispatch — The Great Demographic Divide
An eight-chart dispatch on where the world is growing and where it is growing old. The throughline: the world passed 8.2 billion people in 2024 and is projected to peak near 10.3 billion in the 2080s before it begins to shrink. The 2.1 replacement line now cuts the world in two. Asia, with 4.4 billion people but a fertility rate of 1.7, is the world's demographic centre of gravity, and that centre is itself aging. The next half-century of capital flows is being written by the curves on these charts. Credit to the VC+ team.
Above and Below the Replacement Line
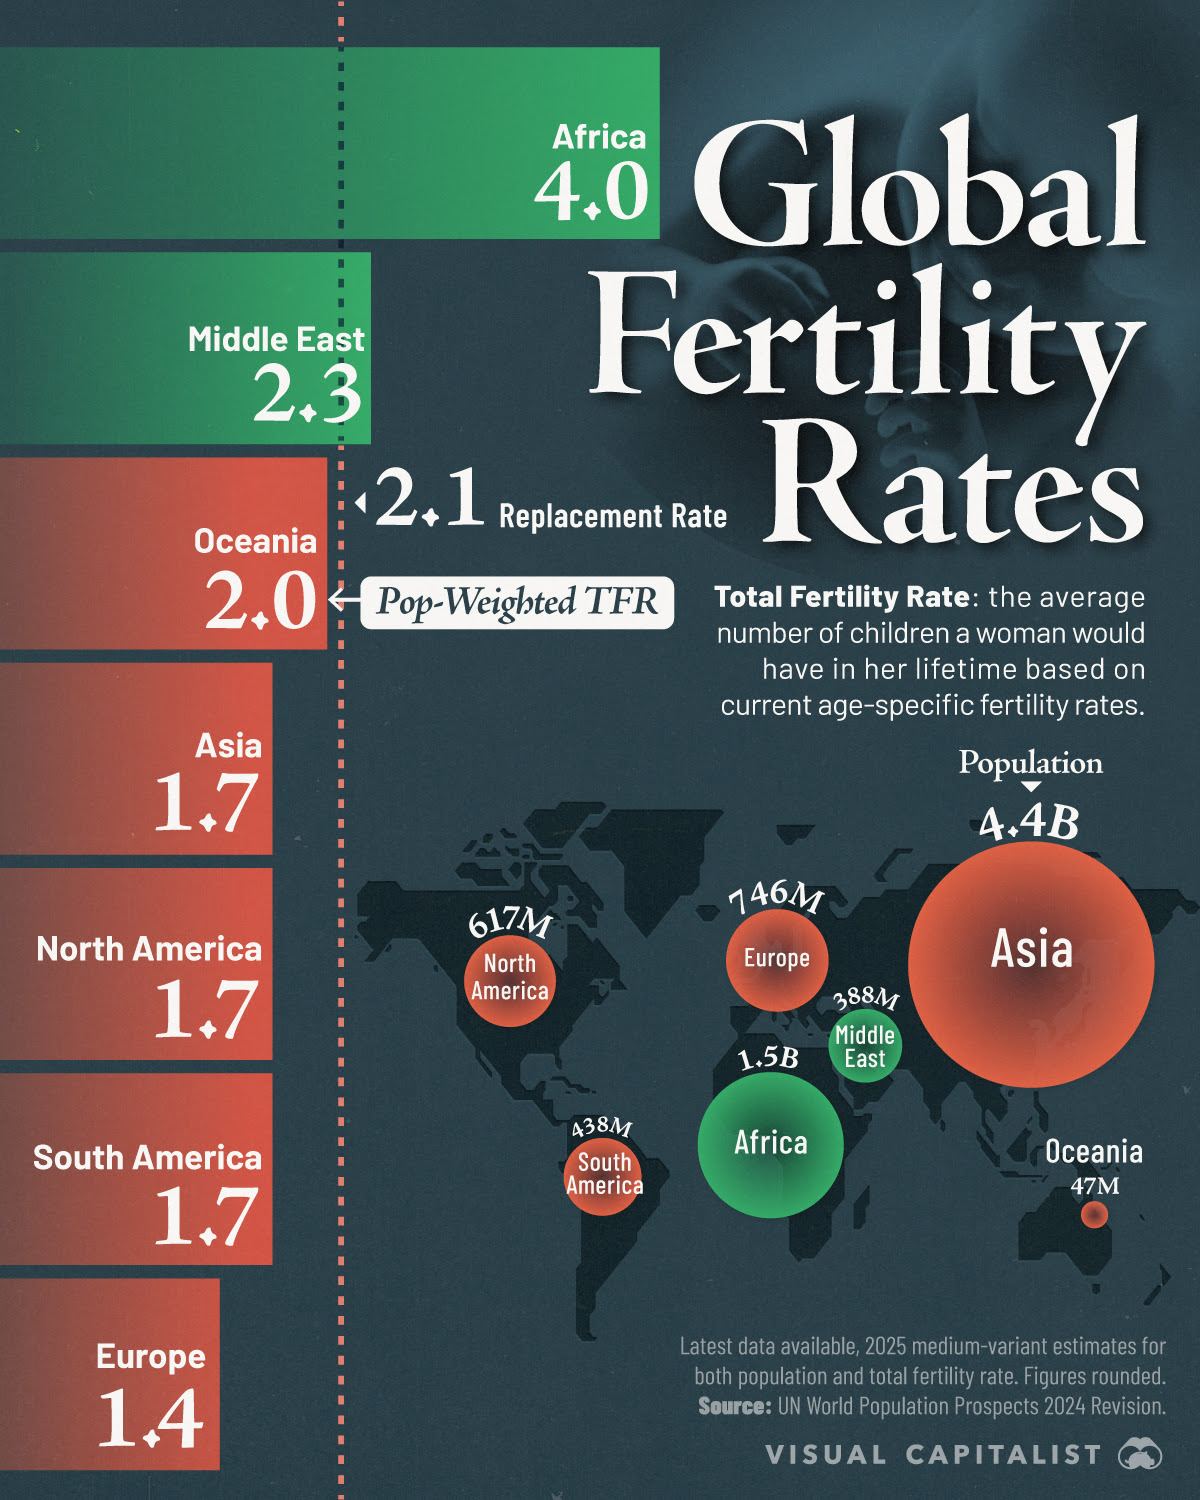
Africa averages 4.0 births per woman, Europe sits at 1.4. The 2.1 replacement line cuts the world in two. Asia 4.4B people but at 1.7, below replacement — the world's demographic centre of gravity is itself aging. Africa the outlier at 1.5B people still climbing fast. The geography of human reproduction has decoupled from the geography of capital. Source: Visual Capitalist.
Most of the World Has Stopped Replacing Itself
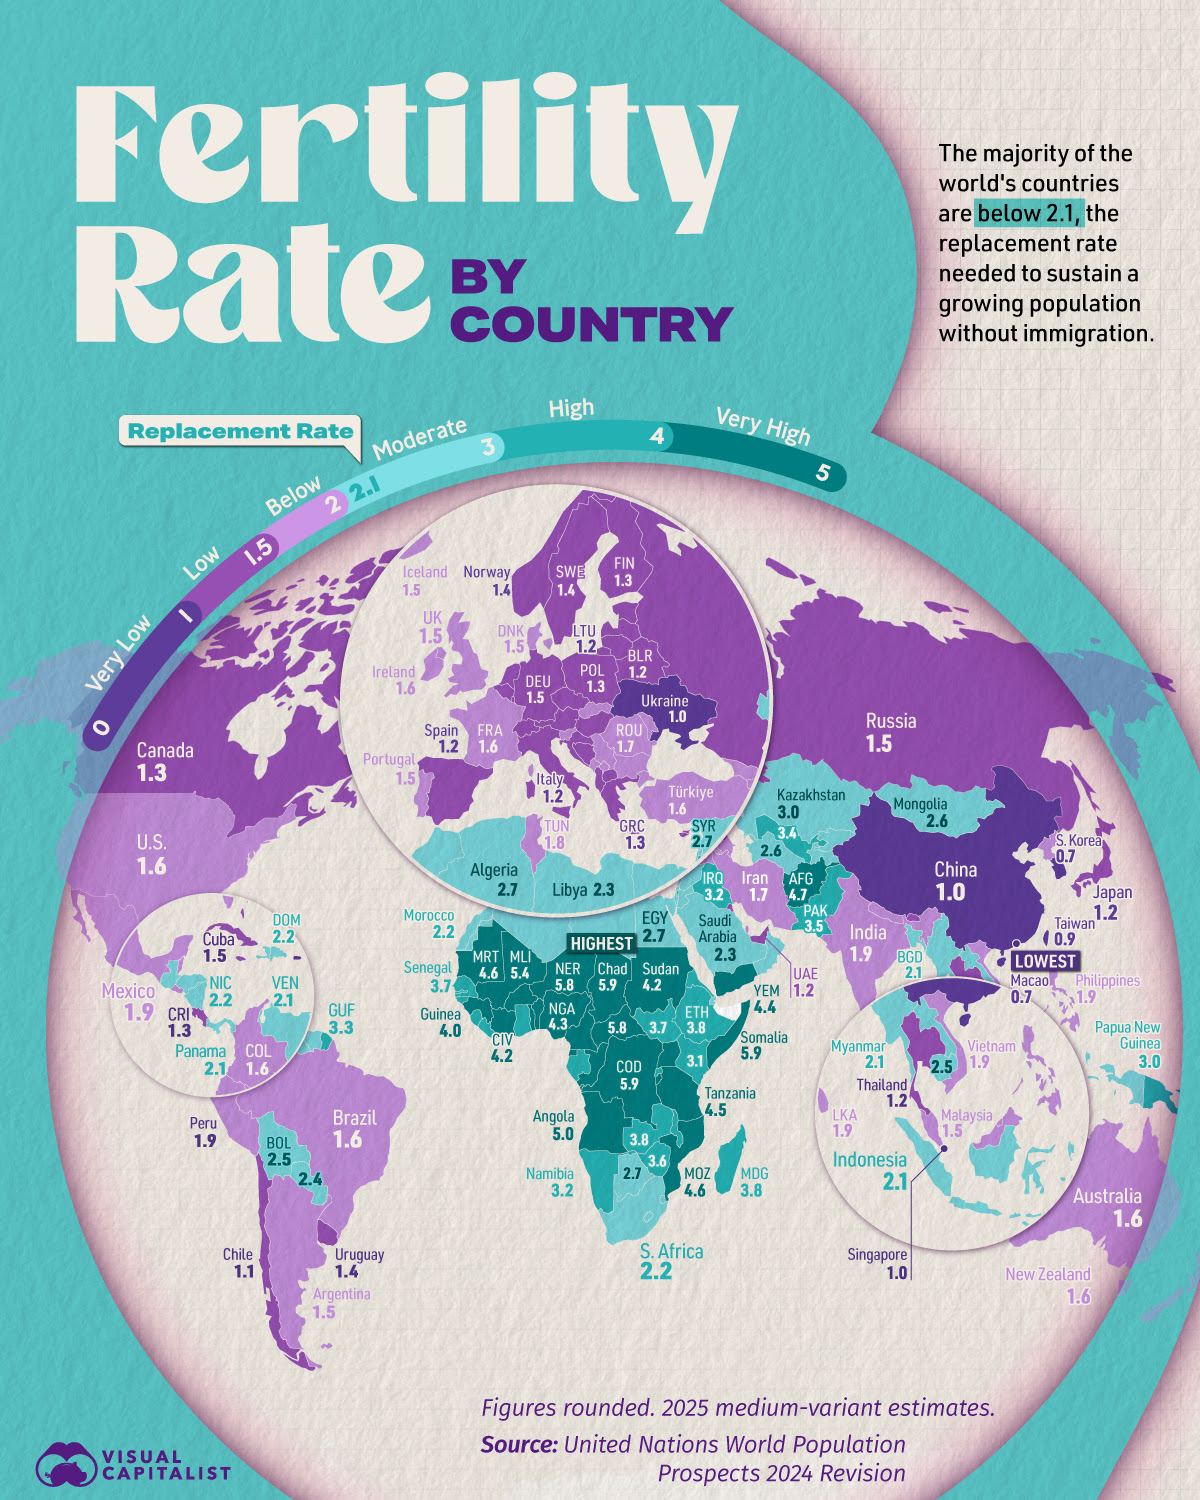
Most of the world has stopped replacing itself. South Korea 0.7, Thailand 1.2, Chile 1.1, Brazil 1.6, China 1.0, India 1.9 — middle-income economies have joined Europe and East Asia below replacement. Chad and Niger approach 6. Outside sub-Saharan Africa the vast majority of nations now share the same below-replacement reality, regardless of income. Source: Visual Capitalist.
The Low-Fertility Giants
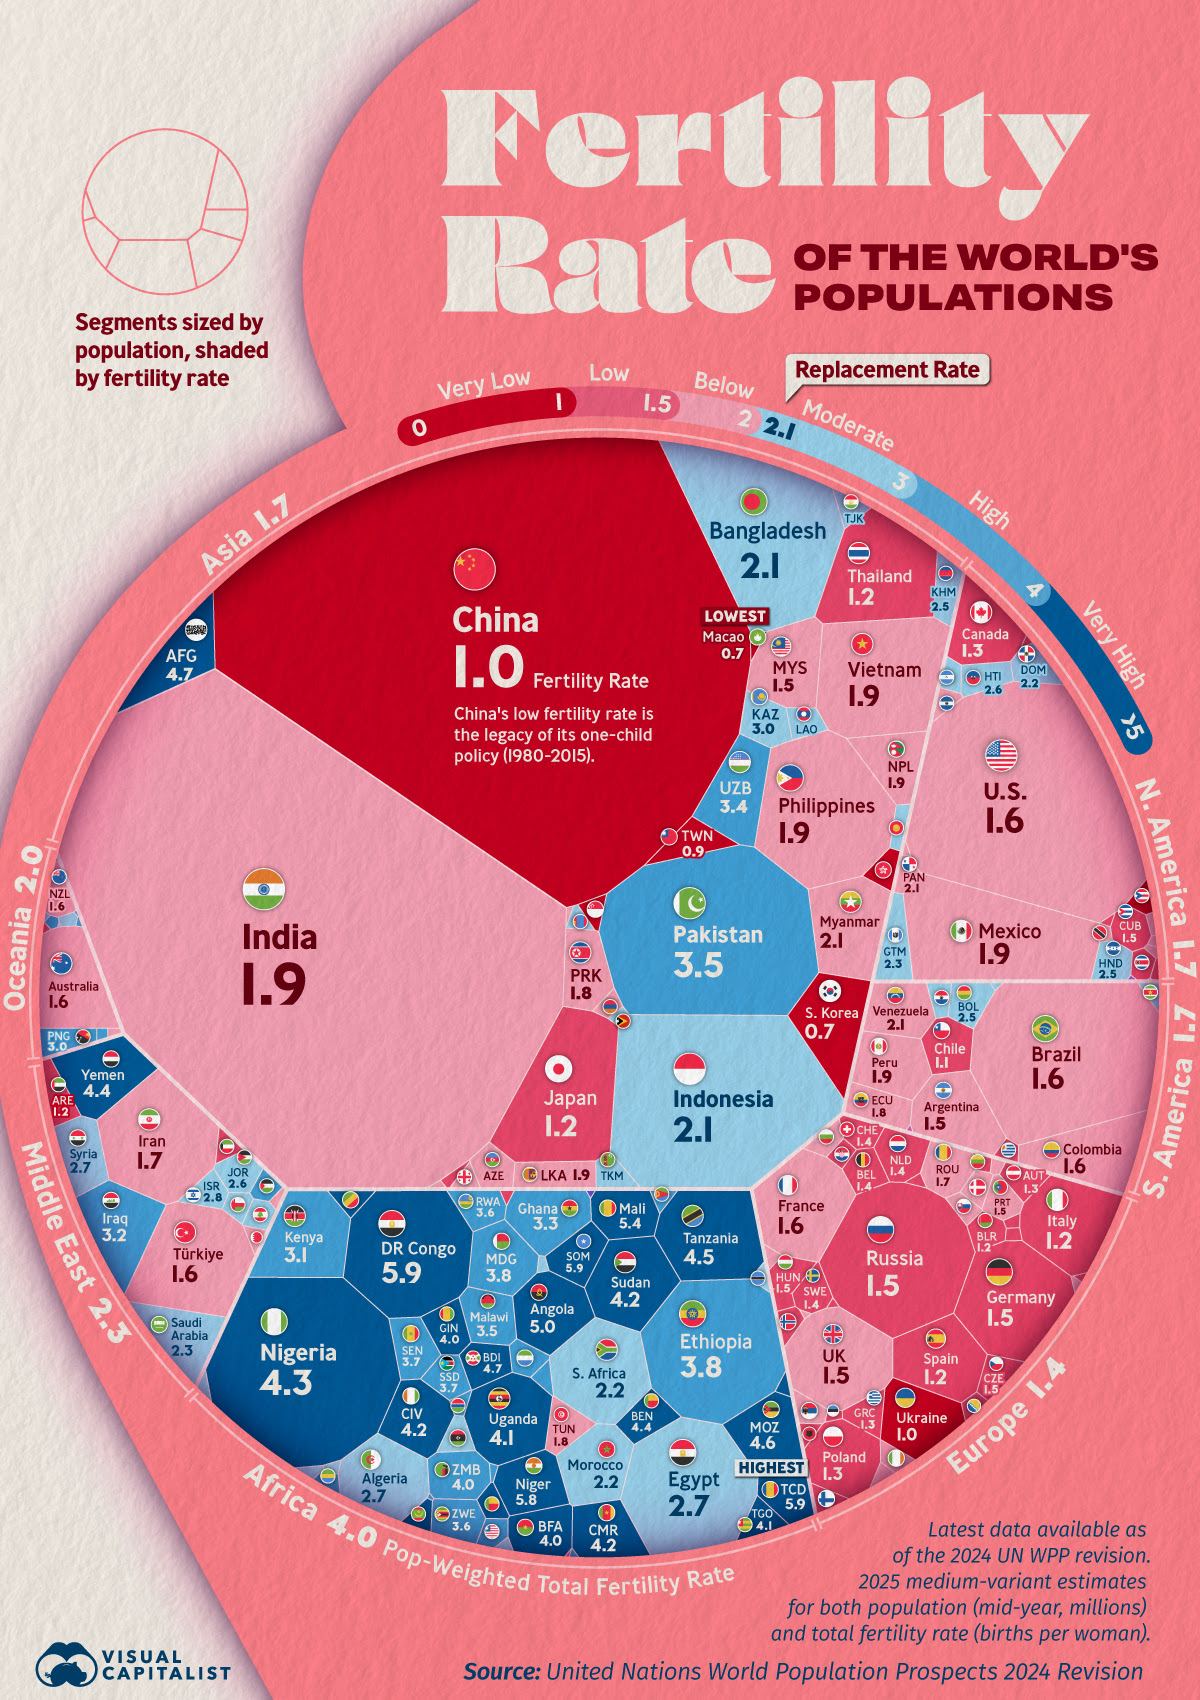
The low-fertility giants. China at 1.0 and India at 1.9 mean the two largest countries on Earth both sit below replacement. China's population fell for a fourth straight year in 2025, deaths now outpacing births by more than 3M a year. India still growing even though fertility has slipped below replacement. Source: Visual Capitalist.
The Fastest-Growing Countries, Measured Two Ways
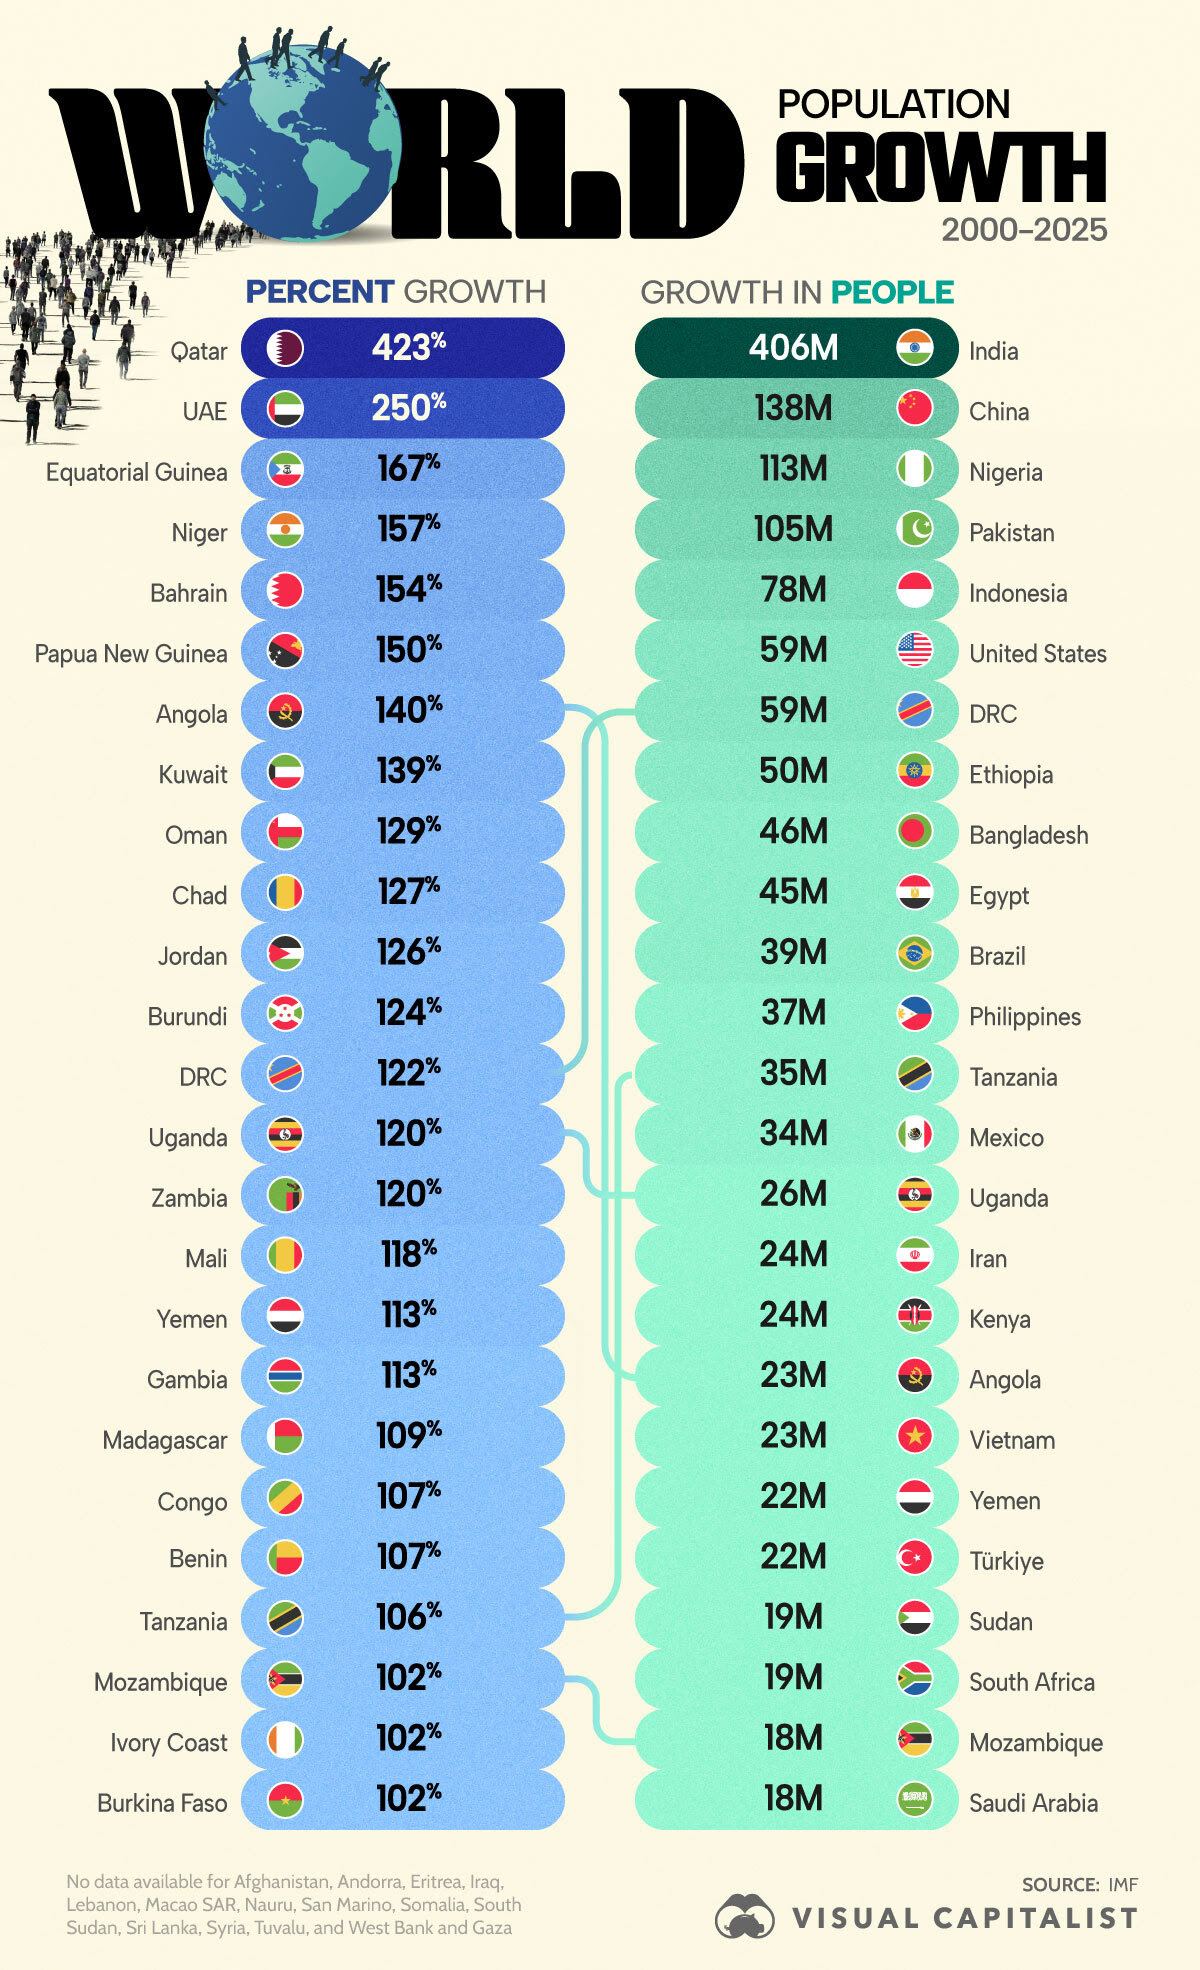
The fastest-growing countries, measured two ways. Qatar's population +423% over 2000-2025 in percentage terms, powered by migrant labour. In absolute terms India added 406M people in 25 years, more than the entire current US population. Sub-Saharan Africa and South Asia dominate the absolute ranking, a preview of where future growth will concentrate. Source: Visual Capitalist.
Where Tomorrow’s Babies Will Be Born
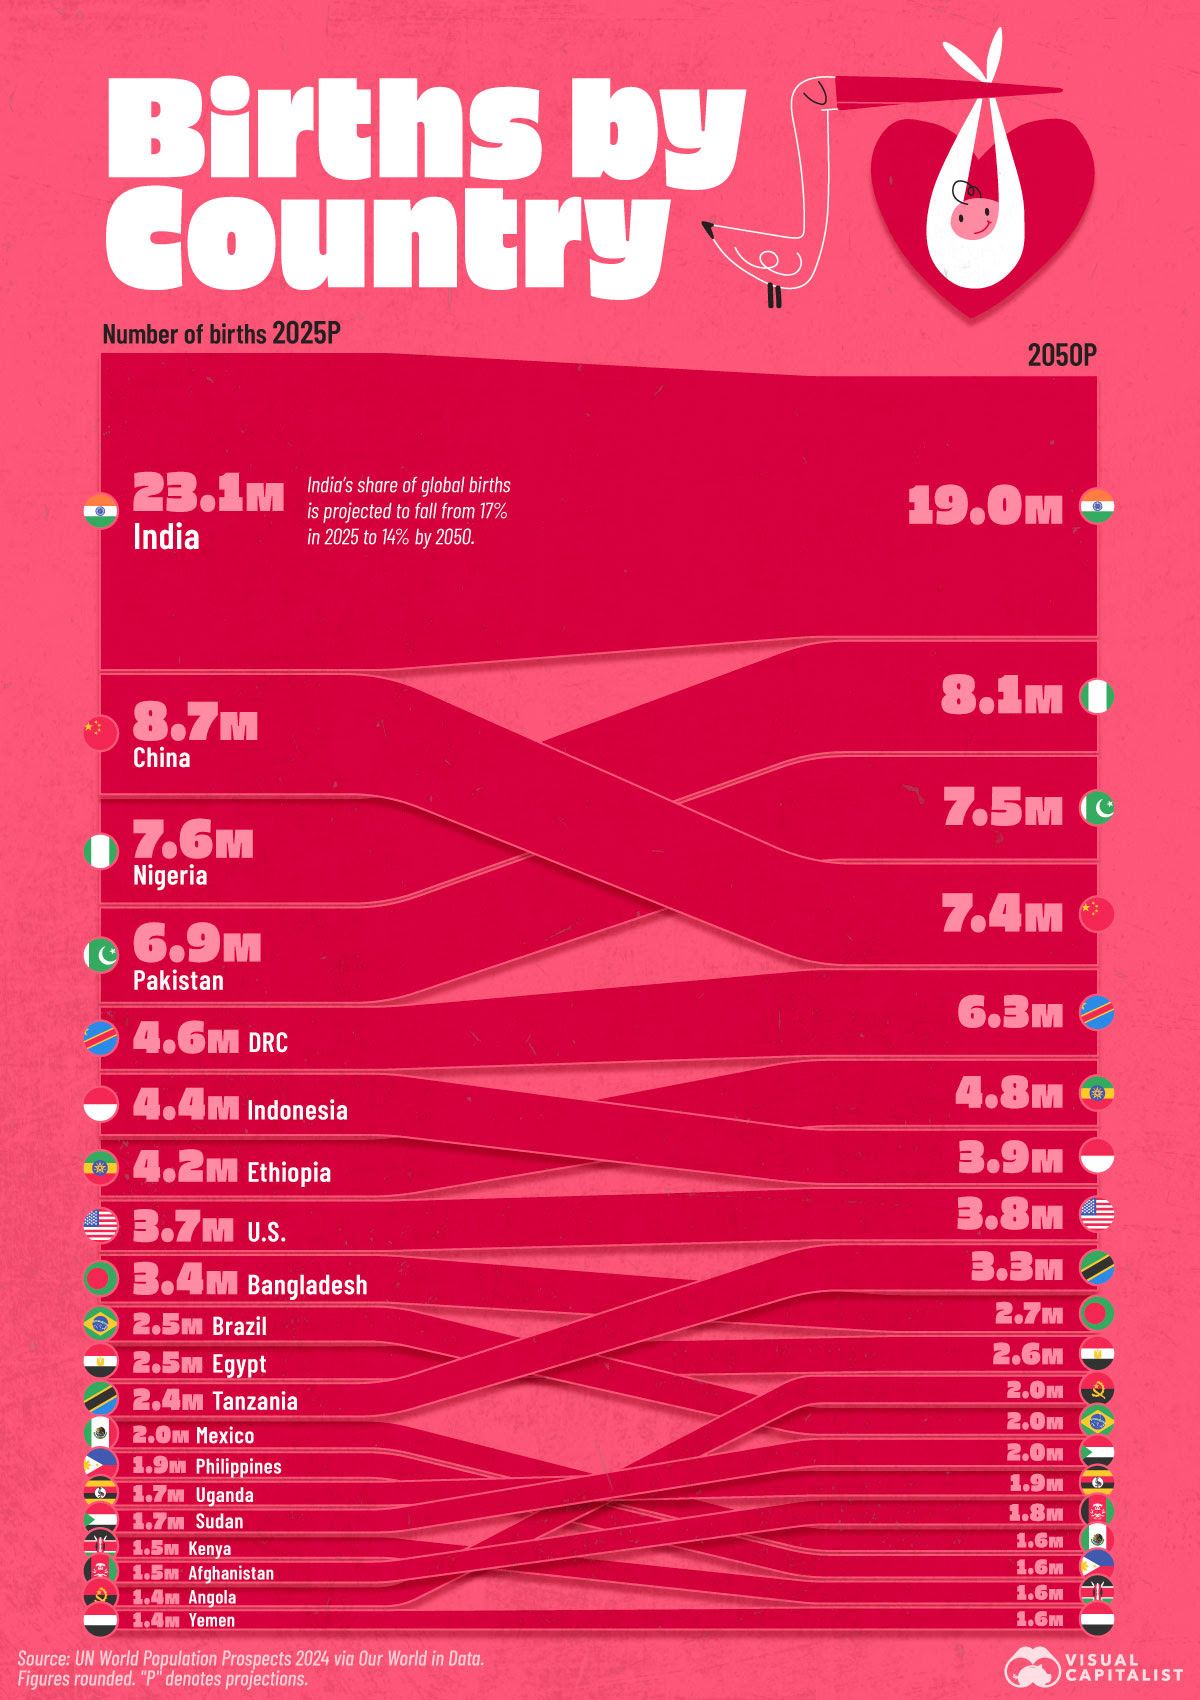
Where tomorrow's babies will be born. India still leads with 23.1M births projected for 2025. By 2050 falls to 19M, share down from 17% to 14%. Nigeria and Pakistan project to overtake China by 2050, which slips from second to fourth. Ethiopia and Tanzania climb. The geography of human birth shifting decisively toward sub-Saharan Africa. Source: Visual Capitalist.
Booming in Africa, Shrinking in East Asia
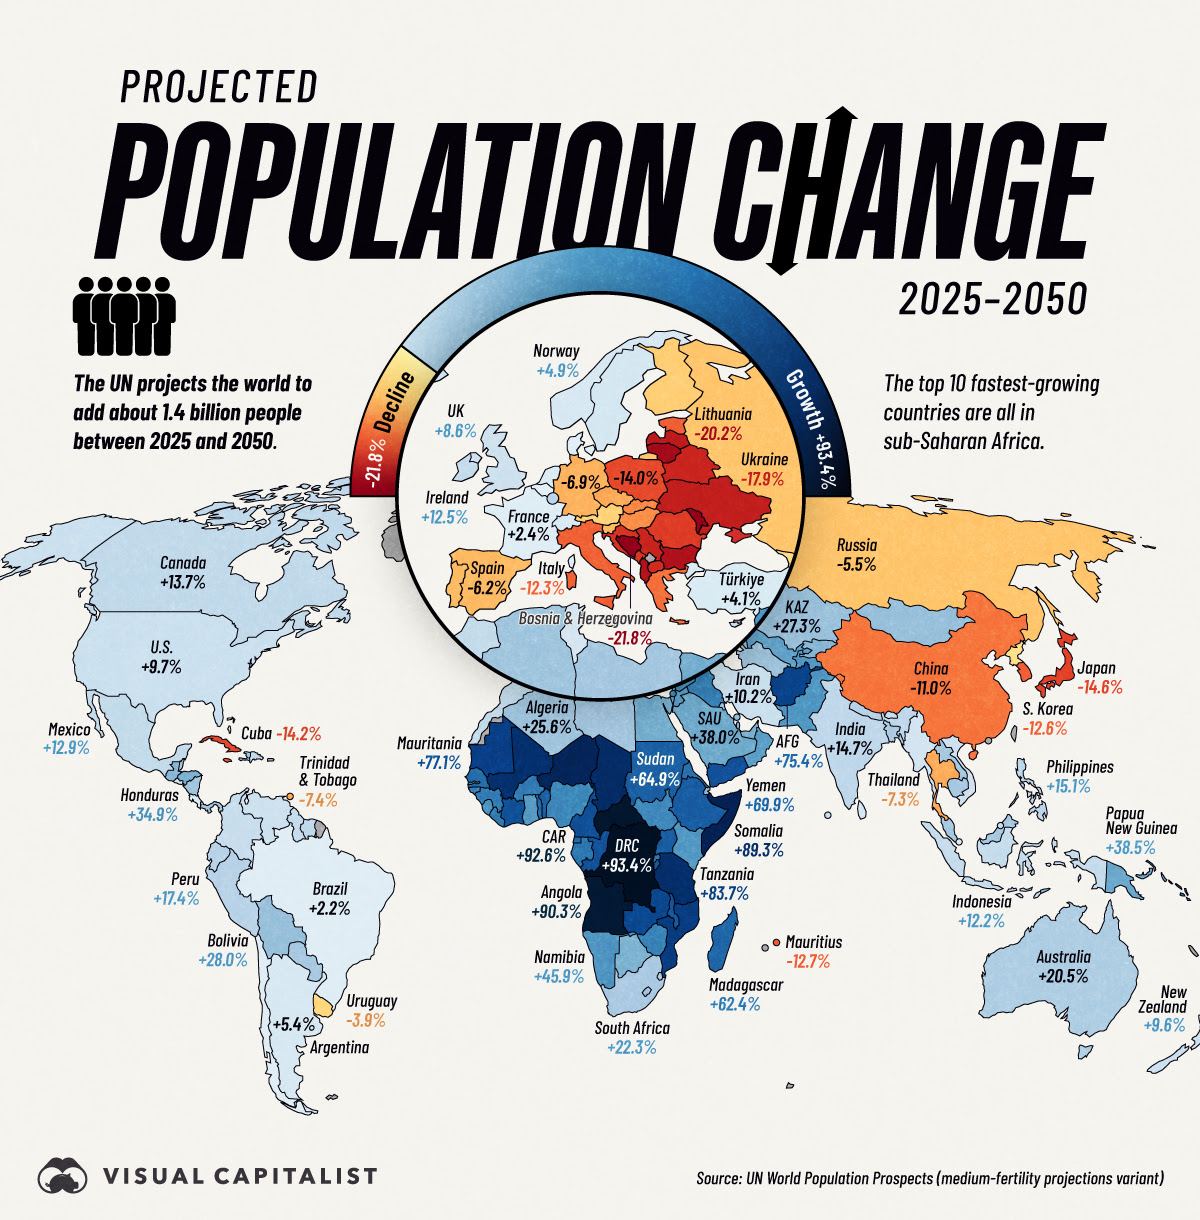
Booming in Africa, shrinking in East Asia. UN projects +1.4B people 2025-2050. The 10 fastest-growing countries all in sub-Saharan Africa, DRC +93%, Central African Republic, Angola, Somalia close behind. Decline concentrated in East Asia and Eastern Europe — China -11%, Japan, Ukraine, Baltic and Balkan states fall faster. Population mass shifts from aging North to youthful South. Source: Visual Capitalist.
The Graying of the Major Economies
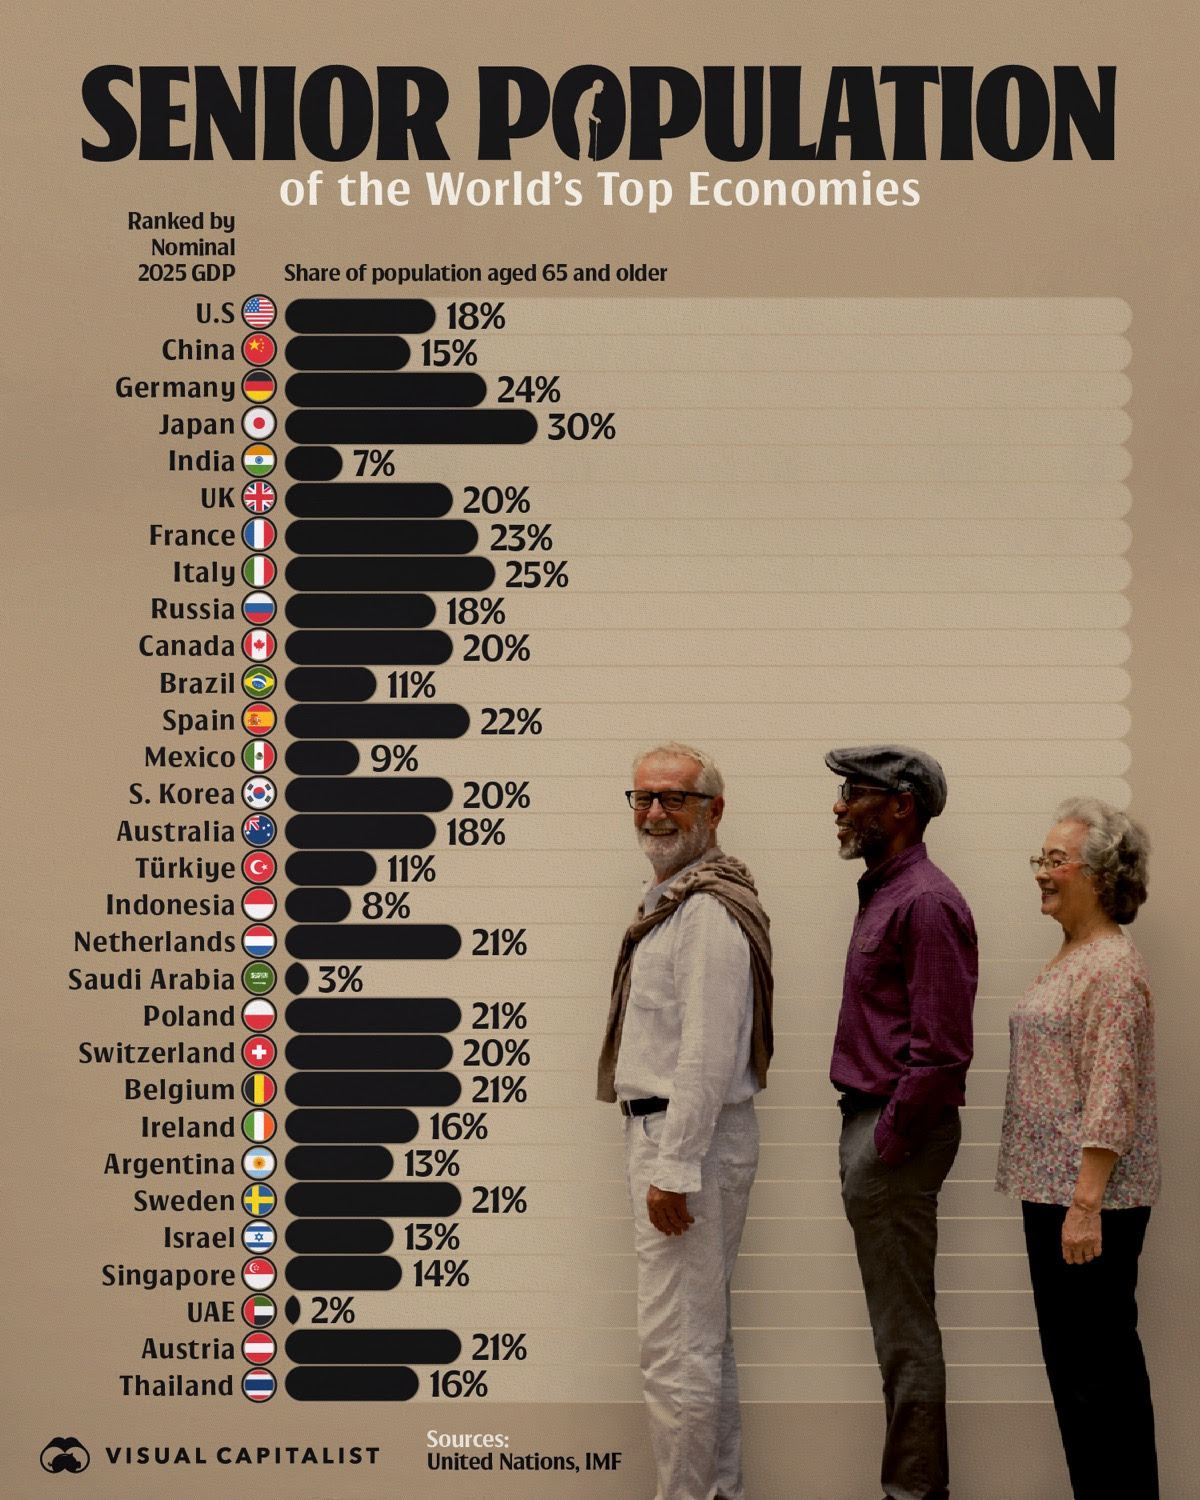
The graying of the major economies. Japan 30% aged 65+, Italy 25%, Germany 24%. A glimpse of where the rest of the rich world is heading. Japan's births dropped below 700k in 2024 for the first time on record, deaths a postwar high. India 7%, Saudi Arabia 3% — a workforce advantage that could last decades. Source: Visual Capitalist.
Living Longer, at Every Income Level
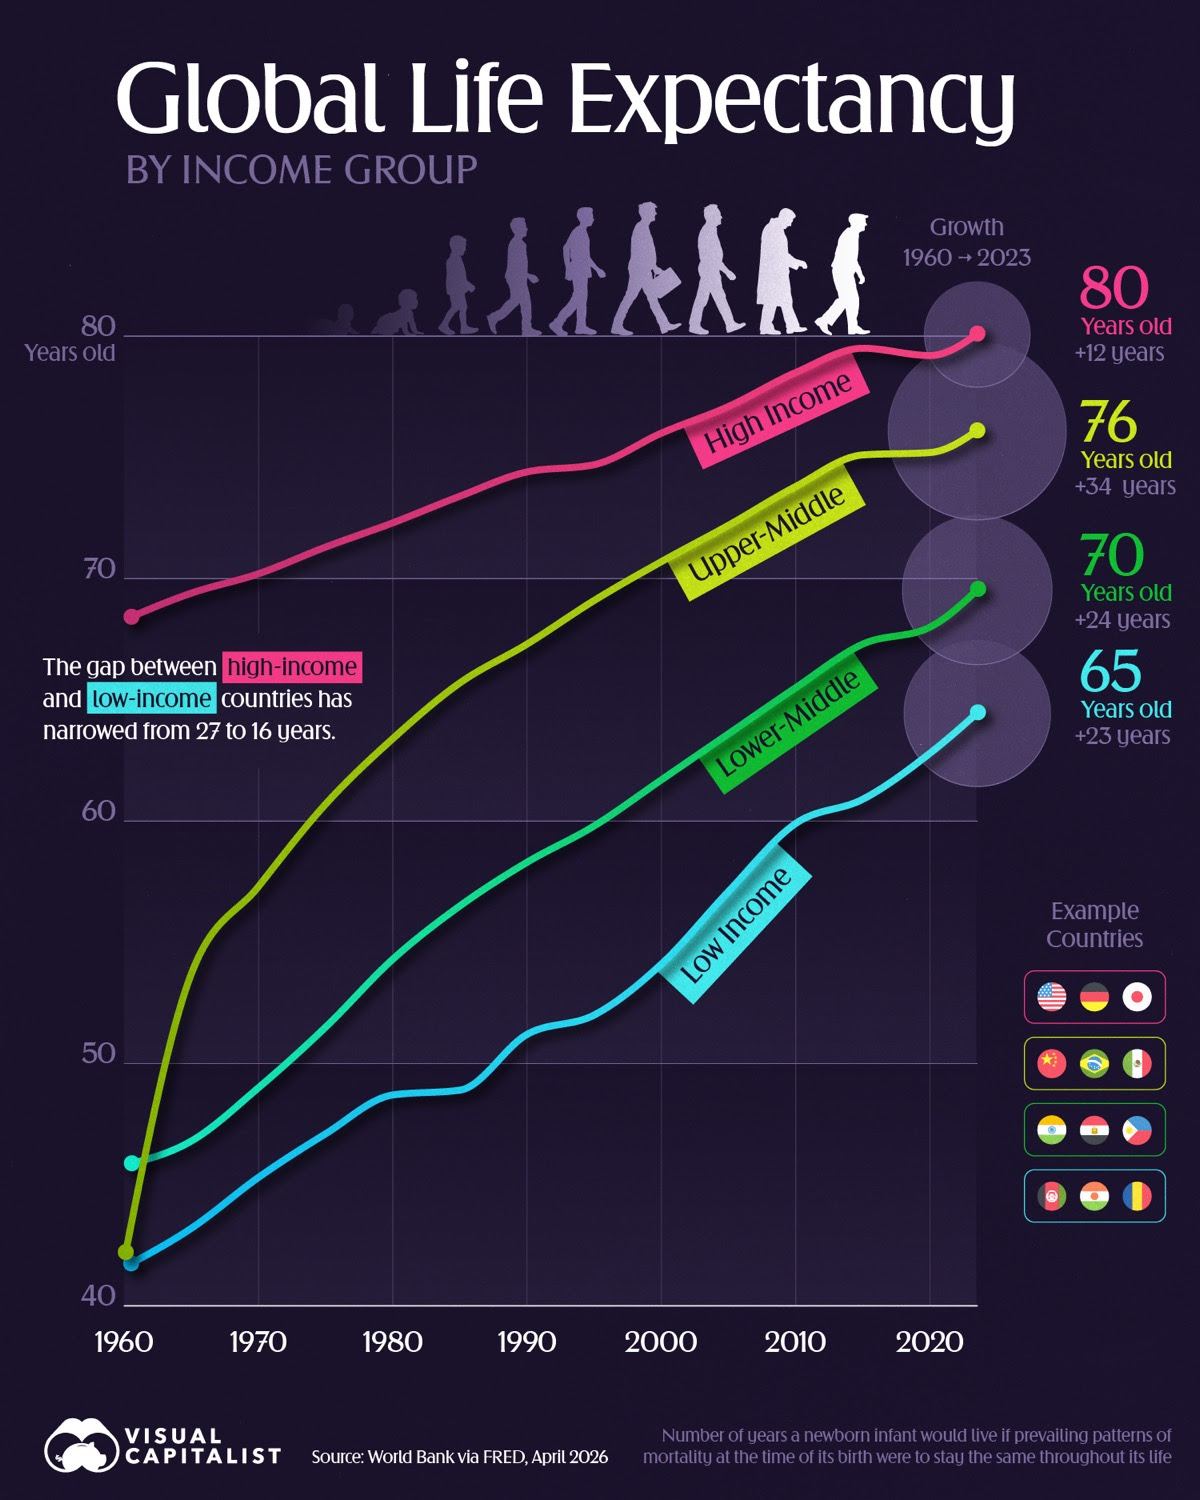
Living longer at every income level. Low-income countries gained 23 years of life expectancy since 1960, the gap to rich nations narrowed from 27 to 16 years. Longer lives a public-health triumph, but they deepen the demographic squeeze — fewer babies plus more elders means working-age adults supporting each retiree keeps falling. The defining challenge of the century ahead. Source: Visual Capitalist.
The Good Wrap
What is left at the close. Chinese TV brands now hold 35% of Indonesia, 36% of Malaysia, 23% of the Philippines, the visible side of the China consumer-export shift that the official PMI bright spot only hints at. The Food for Peace program, dismantled from USAID and moved to the USDA under DOGE, now sends American grain to El Salvador and Rwanda while Sudan, Afghanistan, Lebanon and Yemen are passed over. The trade-over-aid pivot is the soft-power retreat that the rest of the world is now scoring into its read of the United States. The half-year ends here.
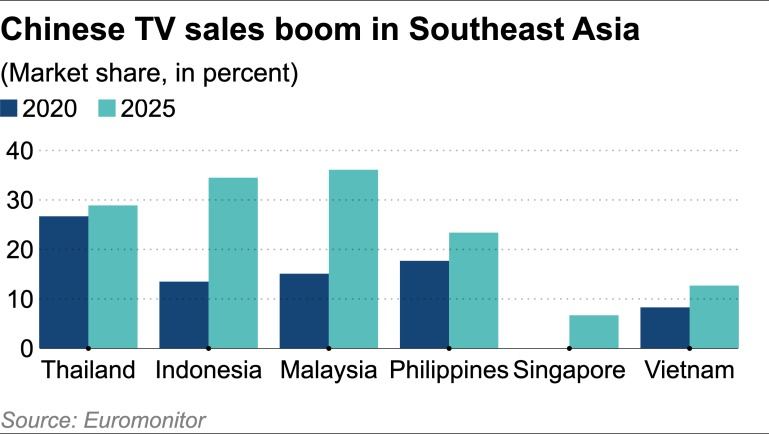
Chinese TV sales boom in Southeast Asia. Market share doubled in five years across Indonesia (35% from 14%), Malaysia (36% from 15%), Vietnam (13% from 8%). The visible side of the China-consumer-export shift that the official PMI bright spot only hints at. Southeast Asia is the laboratory for the next decade of China-brand globalisation. Source: Euromonitor / FT.
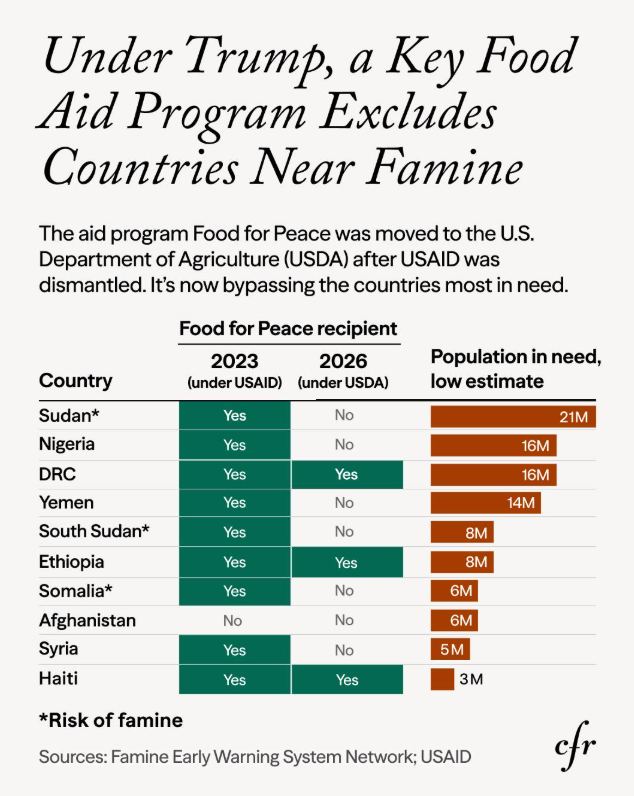
Food for Peace dismantled and moved from USAID to USDA, an agency with no crisis-response expertise. Seven countries selected by USDA for American grain, five legitimate (DRC, Ethiopia, Guatemala, Haiti, Kenya), two not (El Salvador, Rwanda). Sudan, Afghanistan, Lebanon and Yemen passed over. "Feeding hungry people is a means, not an end" per the writer. The trade-over-aid pivot is the macro signal of soft-power retreat. Source: Instagram via Sam Vigersky.
Best,
Hoelon
WITPTW is a personal publication. Everything here is personal opinion and market commentary, written in a personal capacity. It is not investment advice and not a recommendation to buy or sell any security. It is not associated with, endorsed by, or representative of any employer, fund or company. Charts and images are reproduced from their original publishers, credited to their sources for commentary and discussion; all rights remain with the respective copyright holders.